Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 566

The iron law of building wealth

I like the chart below. It shows how when we’re born, we have infinite paths that we can take. Our experiences and decisions take us via a certain route to where we are today. And from now, there are similarly a lot of different directions that we can travel. The question is: what’s the best path for us?
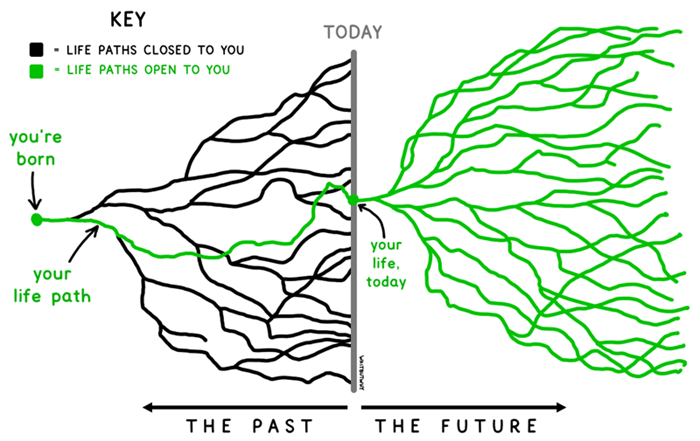

Source: Tim Urban

To make it easier, it can be worthwhile to think about the above diagram in terms of one key aspect of our lives: financial, social, health, perhaps spiritual. And, to consider the best ways to make the most of this part of our lives. To increase the odds of success, if you like.

The future is inherently uncertain. There’s no guarantee that we’ll end up where we want even if we make the right decisions along the way. However, there are ways to lift the probabilities of achieving our goals.

Inverting the problem

How do we this? One strategy can be to turn the question around 180 degrees and look at how not to do it.

Take our health for example. Most of us want to be healthy, to have a good quality of life as well to possibly extend our lifespan. Yet, we often pursue things that will never allow us to reach our goals.

Have you ever dieted before? I know some people who’ve tried every diet there is. Mediterranean, Atkins, high protein, Paleo, Keto, low-fat, intermittent fasting, and the list goes on.

The problem with dieting is it isn’t sustainable. It’s not something that we’ll be able to maintain for the rest of our lives.

The same goes for fitness. Have you ever signed up for a gym membership, and given up after a few weeks? Or go to the gym for a more extended period, then give up for a while, before getting back into it, and then letting the membership lapse again? I know I have.

For many of us, going to the gym isn’t sustainable either. It’s not something we’ll continue over the very long-term, for any variety of reasons.

Often the solution is to look at things that are more sustainable. With diet, it’s perhaps not trying a radical solution but a more incremental one. Instead of going for the Atkins diet, it’s committing to eating a salad for lunch each day. Doing that consistently could do wonders for your health.

Or instead of going to the gym, committing to a sport that you like for 2-3 days each week. Or walking for 30 minutes each day. Anything that you could see yourself doing not only today, but in 10-, 20- or 50-years’ time.

How this applies to investing

How does this relate to investing? The biggest mistake that I see investors make is constantly switching strategies. One minute, they’ll chase the speculative pharmaceutical stock that they’re sure will soon get FDA approval for a certain drug, or the mining company that’s about to make the next big find, or the next bit of market momentum. And the next minute, they’ll chase the investment manager that’s recently shot the lights out, and we all know what usually happens then.

This flip-flopping leads to predictable results. Numerous studies show that the average retail investor underperforms indices by a wide margin.
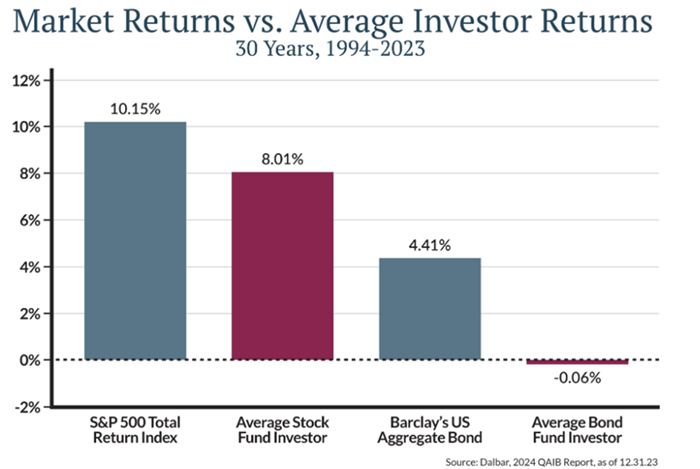
The chart above reveals the average stock investor has trailed the index in the US by more than 2% each year over the past decade. This may be generous as prior studies have found worse outcomes.
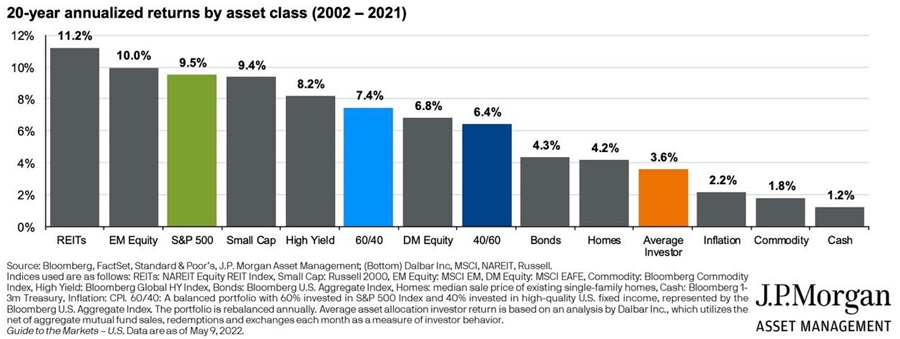
The next chart shows part of the reason why this happens.
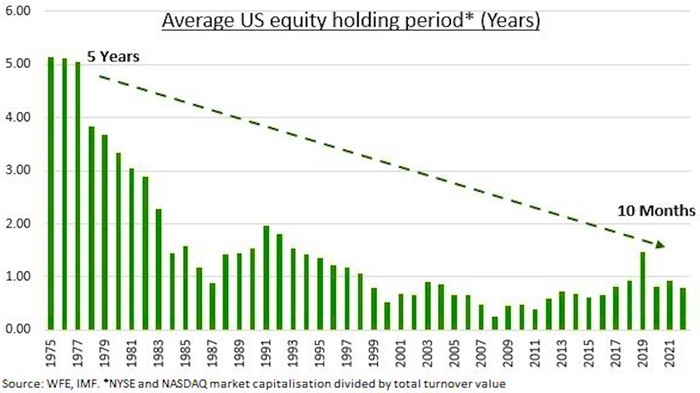
Trading and flip-flopping between strategies are what I call lottery investing. There’s a small chance that you can hit it big, but the odds are against you.

How to tilt the odds in your favour

What can improve the probabilities of building wealth? As with our health, the answer usually revolves around what is sustainable, or timeless. What is an investment strategy that you feel comfortable pursuing in the long-term? Framing the issue this way has several advantages:

  • It gets you thinking long-term rather than trying to find the next ‘lottery stock’.
  • It makes you consider what strategy may suit you best. It’s not about what suits others, but you. Your goals, preferences, and personality.
  • It can help identify your investing edge versus others. Warren Buffett once said: “If you've been playing poker for half an hour and you still don't know who the patsy is, you're the patsy.” This can help you avoid being the patsy!
  • It can help you ride through short-term market noise and market gyrations, both of which undo a lot of investors.

Notice how I haven’t mentioned any specific investing style or strategy worth pursuing, because really that’s up to the individual.

Possible objections

There are a few potential objections to the strategy of timeless investing:

  1. Doesn’t it mean sticking with a strategy that’s static and not moving with the times?
  2. Didn’t Buffett change his style and go on to become successful?
  3. What if my strategy isn’t working? What do I then?

To the first question, it certainly does mean sticking with strategy – that’s the whole idea.

While it’s true that Buffett did change his investment style, there was a specific reason for that. As you may know, Buffett was a deep value investor when he ran his own fund, before buying into Berkshire Hathaway. Meeting Charlie Munger helped Buffett move towards more of a growth style of investing, which led to famous stock purchases such as Washington Post, Coca-Cola, and more recently, Apple.

What’s little acknowledged is that Buffett was forced to evolve his strategy as he grew Berkshire. He foresaw that what worked previously with a small amount of money wasn’t going to work with a large pot of cash.

As to the last question, that’s a tricky one though it makes it even more critical to ensure your original choice of a strategy is the correct one.


James Gruber is Editor at Firstlinks and Morningstar.


  •   26 June 2024
  • 5
  •      
  •   
5 Comments
Stephen E
June 27, 2024

As Charlie Munger said, invert, always invert.

BeenThereB4
June 27, 2024

About 20 years ago, about Melbourne Cup time, I concocted my Investment Trifecta:

Buy/Hold shares in companies that
1. Receive Revenue from sale of goods or services
2. Earn Profits, and
3. Pay Dividends

The above eliminates 75%-to-80% of companies listed on the ASX.

Above avoids wannabees like early stage pharma and mining hopefuls.

One can the dig into P/E ratios, gearing, bona fides of directors etc

Just saying

G-Pete
June 30, 2024

And, BeenThereB4, your result is…..?

David O
June 30, 2024

“invert”, what does it mean when investing?

Chris
July 03, 2024

Always flip the situation on its head and first determine the outcomes you wish to avoid. Eliminating stupid mistakes is easier than trying to execute brilliance.

Munger said “All I want to know is where I’m going to die, so I’ll never go there.”; inspired by the German mathematician Carl Gustav Jacob Jacobi. Jacobi often solved difficult problems by following a simple strategy: “man muss immer umkehren” (or loosely translated, “invert, always invert.”)

He knew that it is in the nature of things that many hard problems are best solved when they are addressed backward. It is not enough to think about difficult problems one way. You need to think about them forwards and backward. Inversion often forces you to uncover hidden beliefs about the problem you are trying to solve; “many problems can’t be solved forward.”


Leave a Comment:

RELATED ARTICLES

The new capital gains tax trap for your portfolio

The investing rule that explains the next market crash

Market entry – dip your toe or jump in all at once?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.