Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 331

Welcome to Firstlinks Edition 331

  •   6 November 2019
  • 3
  •      
  •   

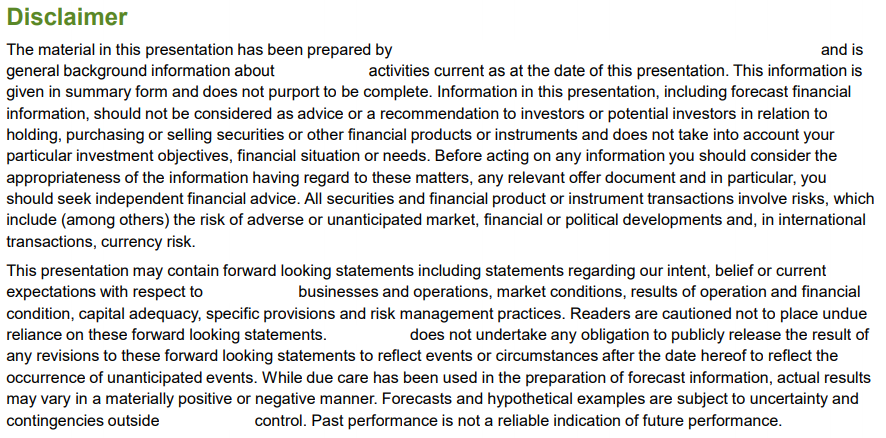
Sludge. Well done ASIC for calling out the meaningless warnings, disclosures and disclaimers in financial presentations and offer documents. ASIC even says they are often harmful to client outcomes. Consider the dreaded disclaimers at the start of every talk. They interrupt well-crafted and strong introductions, and they are usually the butt of jokes by presenters, along the lines of "You've all read that, right? Good, now I'll get on with what really matters."

Nobody reads them. Hundreds of words appear on the screen for a few seconds. I'm waiting for the day when someone shouts out, "I'd like to read that, please. What are you saying? Perhaps it's like the T&Cs for Facebook where I give away my rights." In Product Disclosure Statements, endless and useless warnings can overwhelm the valuable content.

The ASIC survey found that mandated disclosures and warnings are often ineffective, and may contribute to consumer harm. Deputy Chair, Karen Chester, said:

"It's time to 'call time' on disclosure as the default consumer protection. It's not the 'silver bullet' once thought, nor should it be relied upon as one. Disclosure can and has backfired in unexpected and harmful ways ... the over reliance on disclosure in some ways proved an enabler of poor conduct and poor consumer outcomes revealed by the Financial Services Royal Commission."

Here is a random example taken from a fund manager presentation with the identity removed. It's more about protecting the company than warning the consumer. As ASIC says, in practice, we ignore, overlook or misunderstand warnings.
Our first article follows a similar theme of misunderstanding an audience. At least 75% of Firstlinks' readers are over 55, and it is generally a well-off and engaged group. Rose Herceg reports research on how marketers and brands ignore the over 50s audience (and while few people look forward to ageing, a recent Ipsos study says Australians consider 'old' starts at about 66). The over 50 segment is active and enthusiastic and our readers are finding new ways to plan for their so-called 'retirement' every week. We need another word.

While bond funds have been available in the unlisted space for decades, there is a new range of listed options bringing fixed interest to a broader group of investors. We explain the choices.

Mercer has ranked Australia's retirement system third in the world but at a B grade, and David Knox describes the changes needed to create an A grade system.

I recently met with a financial adviser for the first time in many years, and I can attest to the merit of the input. Daniel Reyes weighs in with four reasons to engage an adviser.

We tend to look to the US as the engine for global growth, but George Toubia shows how the future will be increasingly Asian. Continuing this theme, the White Paper this week is Fidelity's confirmation that the region will shine. It's a perfect reminder in the week when Prime Minister Scott Morrison signed a trade agreement with 15 Asian-Pacific countries.

The market's rejection of WeWork is the highest-profile IPO failure this year, a welcome reminder to investment banks that they need to deliver better quality. The $12 billion total raised on the ASX this year is a quarter of the average for the last five years. Damien Klassen reveals some of the tricks sellers may use to inflate the value of their offers.

Last week's survey on including the home in the pension assets test drew a strong response, and Leisa Bell compiles the results and selects from the vast range of comments received. While the Firstlinks' audience is not a random sample of the Australian electorate, could this be a policy measure with far more support than the Government believes, done the right way?


Graham Hand, Managing Editor

For a PDF version of this week’s newsletter articles, click here.


  •   6 November 2019
  • 3
  •      
  •   
3 Comments
AS
November 06, 2019

Thanks Graham. Interesting read again.

I read with interest a quote from Australian Institute of Superannuation Trustees chief executive Eva Scheerlinck on the topic of PDS disclosure for super funds.

"It is the role of regulation and legislation to ensure that members are getting fair value for money, rather than relying on members' ability to compare funds through disclosure."

I just can’t see how the role of regulation and legislation (assuming she means the regulation and legislation around PDS disclosure) is to ensure that members are getting fair value for money. I would have thought this is the role of competition. It is interesting to read the differing views on this.

Warren Bird
November 06, 2019

Further to my comment on the "Retire retirement' article, I note Graham's quick summary here.

It's interesting about people thinking that 'old' is 66.

When I was in hospital for a month just before I turned 60 and had some time on my hands to discover new things, I became a fan of Ed Sheeran. One of his great songs, "Thinking Out Loud" includes a line "darling I'll be loving you until we're 70". So it seems that young people like Ed think that 70 = old.

This happens to be just over 10 years less than the average life expectancy in Britain these days. So it would seem that young folk like Ed Sheeran think that you are old about a decade before your expected end.

My thoughts turned to another song, from my younger days, about being old. Ringo Starr once wondered in song, 'will you still need me, will you still feed me, when I'm .... " You all know the number. 64.

Interesting, but back in the 1960's life expectancy (at least in the UK) was 72. Ringo and the Beatles thought you were old when you had just under a decade of life expectancy left. So not much has changed! Young people's perceptions have, at least, kept up with the actuarial statistics!

At the rate life expectancy is increasing, however, I guess it won't be too long before the next Ed Sheeran sings about still being in love when we're 90 or a 100.
Still, as long as the songs are as good as this one, what does it matter! Click on the link, hit play and enjoy one of the great love songs of the 21st century.
https://www.youtube.com/watch?v=lp-EO5I60KA&sns=fb&fbclid=IwAR2RjXKwWKcBl-9NPnaZ_O8oT0dQ6dJjt-YNphjV2ECEKwbmZ-m1Caw3Ajg

Ramani
November 09, 2019

A comment on ASIC's new-found enthusiasm about disclosures that confound rather than clarify.
About time, from the agency that till some time ago treated disclosure as the panacea, the whole panacea and nothing but the panacea. This ignored the truism that unless it makes sense to the intended audience all disclosure is in Swahili translated into Sanskrit. No doubt the system is being gamed through incomprehensible and irrelevant drivel loaded onto illiterate and inertia-bound targets of witting ignorance.
Not clear how this will be addressed: would opaque disclosures be treated as non-disclosures and prosecuted by the Hayne-convertee 'Litigate first, Negotiate later' regulators?
As we go about cleaning this mess up, there is another elephant room that we have been impervious to: the pervasive disclaimer of every professional adviser to the world at large 'This may not be suitable to you, seek professional advice'. What do they think we are doing when we engage them: social intercourse?
ASIC, ACCC and the other authorities must require every professional adviser to specify which professional advice they have in mind when they say so, and more critically, explicitly accept liability for their own expertise instead of the usual 'we disclaim...'
Sludge it is - and there is more to be mined before we change into consumer-facing from the current consumer defacing.
Shangri La!


Leave a Comment:

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.