Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 75

The best and worst managed fund of all

Anyone who was invested in a listed property fund throughout the GFC experienced a rapid destruction of wealth. Many former high flyers of the property world, such as Centro, Allco, MFS and City Pacific, had become highly geared in complex structures, and in the severe market disruption, were unable to rollover their debt. They faced years of complicated legal battles and capital restructuring.

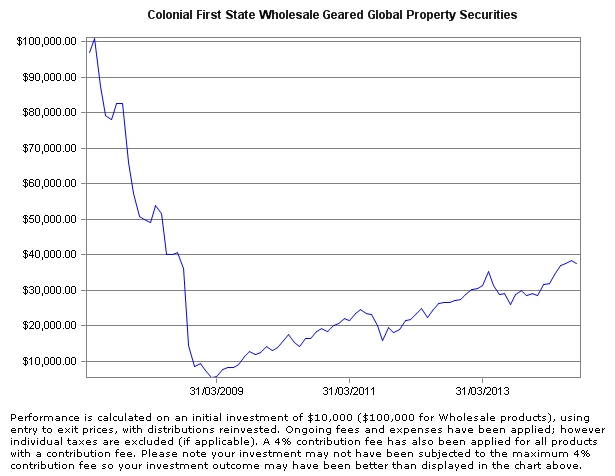
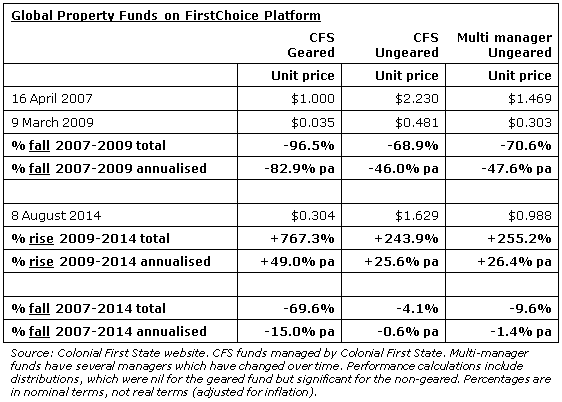
Amid this imbroglio, the wildest ride of all was the Colonial First State Geared Global Property Securities Fund. Launched in April 2007 at $1, it had lost almost 97% of its value less than two years later in March 2009, when it touched 3.5 cents. It has since risen to over 30 cents. It has almost become, as they say in the trade, an ‘eight-bagger’ – a return of 767% since the bottom of the market.

These changes in value show that the debate about SMSFs borrowing should not be confined to structures where the fund itself is the borrower. It’s the total leveraged exposure and the underlying assets that matter most, not where the borrowing resides. SMSFs investing in this fund had no borrowing in their own name.

Depending on investor timing, and defining ‘worst’ as biggest fall and ‘best’ as biggest rise, this is either the best or worst managed fund in Australia. Here’s the impact on $100,000 since 2007.
Of course, some other investments in Australia have lost all investor capital, but they are usually a single asset or share, or due to some fraudulent activity. This is a managed fund with rules about maximum investment in one stock and portfolio diversification, and these rules were not breached. Colonial First State has strict investment management compliance and any straying from the investment criteria is immediately corrected. And surely property is something you can see and kick, it’s not small resources and it’s not technology. How is it possible for a managed fund to go from 100 cents to 3.5 cents in less than two years?

There are two main reasons: first, any geared fund will amplify the losses of an ungeared equivalent fund. For an explanation of how this works, see this article. Second, the underlying assets themselves were highly geared, and while this may have been fine in normal market conditions, it was a volatile combination during the GFC. The strong market conditions of 2003 to 2007 created false confidence for the managers of both property securities funds and their investee companies.

As the table indicates, even the ungeared version of this fund fell 69% over two years. A multi manager fund in the same asset class over the same period fell 71%, despite an investment strategy which was:

“To invest in a diversified portfolio of property securities. The investments are managed by a number of leading global property securities managers, which is designed to deliver more consistent returns with less risk than would be achieved if investing with a single investment manager. The portfolio aims to hedge currency risk.”
What are some of the lessons from this experience?

  • Any gearing structure should watch for gearing on gearing. Although almost all listed companies have some level of borrowing, property funds were historically highly geared going into the GFC, and the major feature of their subsequent restructuring has been to move to lower gearing levels.
  • Internally geared funds have a role to play in a portfolio only where the investor fully understands and accepts the potential downside as well as upside. In general, a fund geared at 50% ($1 of debt for every $2 of assets) will have double the price volatility of an equivalent ungeared fund.
  • Investors need far better performance to recover from a fall than the percentage fall itself. For example, if a $1 investment goes to 50 cents, it has fallen by 50%. But to recover from 50 cents to $1, it must rise 100%. In this geared property case, although it has risen an amazing 767%, it is still down 70% due to the 96.5% fall. The ungeared funds have risen far less but they fell less. On an annualised basis and including distributions, the ungeared funds are not far from their 2007 values in nominal terms (not adjusted for inflation).
  • Excellent investment opportunities can come from periods of crisis. Most property funds rebuilt their balance sheets by issuing shares at fire sale prices, below Net Asset Values, and investors with the cash to fund this recovery have usually had great results.
  • Perhaps most important, there are insights for the current debate about SMSF borrowing, where the primary focus has been on the SMSF itself borrowing to invest in residential real estate. The experience with internally geared funds (and assets which themselves are highly geared) shows it is the total amount of leveraged exposure that matters, not the vehicle in which the borrowing resides.


Property securities have given investors a wild ride over the last seven years, and the most amazing thing about the best and worst managed fund in Australian history is that it’s the same fund.


Graham Hand was General Manager, Capital Markets at Commonwealth Bank; Deputy Treasurer at State Bank of NSW; Managing Director Treasury at NatWest Markets and General Manager, Funding & Alliances at Colonial First State, where he was responsible for gearing management (not asset selection). Nothing in this article constitutes personal financial advice.


  •   15 August 2014
  • 3
  •      
  •   
3 Comments
Graeme
August 14, 2014

At least Colonial stayed for the long haul. Some other managers, who having heavily geared their property trusts (management fees charged on gross assets?) deserted the ship when things hit bottom.

This enabled the departing managers to preserve their reputations by pretending it never happened, while the new managers after a couple of years could crow about short term performance from the inevitable recovery.

The big problem of course with ill advised borrowing in a SMSF is that the manager (you), can't simply pass it on and walk away unharmed. You'll have to live, probably very frugally, with the consequences.

Tony
August 15, 2014

Many Managers have had the 'bottle' to freeze clients funds, open up new funds and attract more money. A shame for the clients who got caught not being able to acess their money. Many still can't and have to wait for small distributions or for the manager to sell a property before they see any capital. My only hope is that it doesn't happen again, but my guess is it will!

Alan
October 16, 2014

My managed fund investment in mid 2006 had declined 97% in value by 31 March 2009.
As at Oct 2014 the investment is still just worth 11% of the original sum and unit prices are flat-lining.
For a professional investment company to reduce the funds entrusted to it by 97% of the value in just three years has to be an accomplishment worthy of a case study in flawed investment strategies, poor decision making and a failure to protect investor's funds. Ask if that is not incompetence.
Lessons learned: 1. Don't trust performance figures of managed funds. 2. The volatility of REITs is not worth the risk. 3. Invest directly in diverse shares using own judgement and common sense.


Leave a Comment:

RELATED ARTICLES

Duh! Of course geared funds won, but know the risks

The case for gearing beyond property

Financial leverage in real estate: friend or foe?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.