Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 260

CBA waves white flag on wealth management

In 2000, when CBA bought Colonial State Bank and its wealth manager, Colonial First State (CFS), CBA hired me as a consultant on the deal. One of my roles was to determine how much funding CBA could source from CFS portfolios. CBA expected CFS fund managers to invest more into CBA deposits.

It showed a fundamental misunderstanding of the responsibility of a fund manager to act in the best interest of its investors, not the bank's shareholders. The CFS fundies explained their fiduciary duty and told me where to stick my bank balance sheet. Ouch!

The confusion arises because a banker is not a fiduciary in its customer relationships. A bank is entitled to prefer its own interests above those of its customers, and the bank generally has no duty to advise customers of a more advantageous deal. Banks offer lower deposit rates and higher lending rates to existing customers than new customers without any compunction.

There is therefore inherent conflict when banks own wealth management businesses. To some extent, it can be managed by strict rules about conflicts of interest, but there are cultural differences. In 2011 when CBA paid $373 million for Count Financial, it was driven by the assumption that Count clients would go into CFS funds and platforms. It never happened, and now CBA has run up the white flag and given up on wealth management. CEO Matt Comyn explained:

"(CFS Group) will benefit from independence and the capacity to focus on new growth options without the constraints of being part of a large banking group ... It also responds to continuing shifts in the external environment and community expectations, and addresses the concerns regarding banks owning wealth management businesses."

In fact, it does not address the main vertical integration concerns about funds management, platforms and advice in the same corporate structure, and it passes that problem to the next management team. In commenting on the word 'independent', ASIC said that under s923A of the Corporations Act, a licensee can only describe itself as independent if it is operating without any conflicts of interest.

Following the FOFA legislation, advice scandals and the Royal Commission, CFS staff who manage the FirstChoice platform must go through a more arduous process to include in-house funds than those of external managers. Internal compliance demands evidence that funds from Colonial First State Global Asset Managers, and alliances such as Realindex, Aspect Capital and Generation, are both cost and performance competitive. It's a way of managing the vertical integration conflicts, but it does increase the compliance, legal and administrative work on selecting funds for the platform.

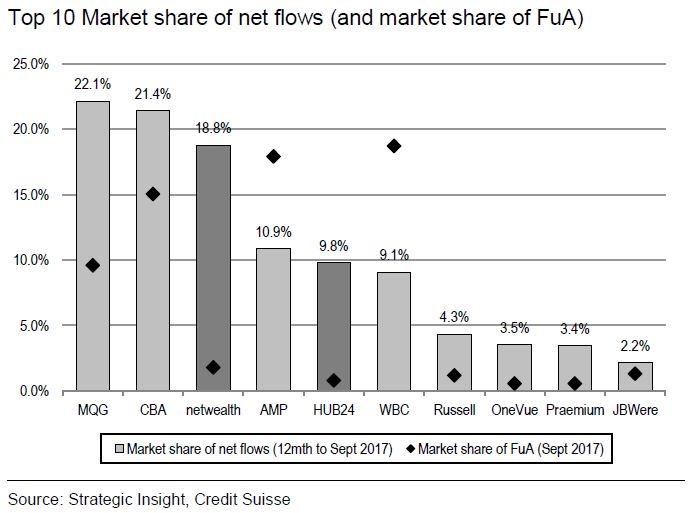
CBA had a harder decision than ANZ and NAB, as its wealth business is more substantial and successful. As the following chart shows, CBA entities not only have a much larger market share of funds, but they are doing well on new flows. The chart also shows why Hub24, netwealth, OneVue and Praemium are sharemarket darlings, gaining more flows than their market share.
wealth management

wealth management

Matt Comyn wants to go back to banking basics, and he threw Aussie Home Loans and Mortgage Choice into the demerged entity to avoid further Royal Commission fallout. But nobody is asking why he kept broker CommSec in CBA. Probably because he once ran CommSec and feels he understands it, but it barely qualifies in the "focus on its core banking businesses". The separation ends the 'bancassurance' and 'allfinanz' models that bankers loved in the 1990s.


Graham Hand is Managing Editor of Cuffelinks.


  •   28 June 2018
  • 4
  •      
  •   
4 Comments
GG
June 28, 2018

Graham,

That's a great recollection re CommBank and CFS. Dead right, IMO.

I bought my house in Surry Hills back at the beginning of 2000, literally just as CBA swallowed Colonial. I remember agreeing to a CFS mortgage and coming home with a CommBank one.

David
June 28, 2018

The other reason Matt Comyn is happy to keep CommSec is probably because the fiduciary relationship owed to a client in managed funds does not apply in stockbroking. So it's the same culture as the bank in shareholder priority.

Warren Bird
June 29, 2018

I believe that I was one of the people who told you where to go back then, Graham!

Purely a personal opinion, but I was never happy with the way CBA handled Colonial after their acquisition. Senior management at CFS argued with David Murray at the time that our success was built on being an end-to-end business that could set its own spending priorities (especially on IT) and determine its own business development strategy. He rejected that idea and CFS went into the competitive pool for resources.

We argued that our success was built on not having aligned financial planners, which would compromise our service delivery to independent financial planners. Not only conflicts of interest, but also the fact that planners could dump us and use other managers kept us focussed and sharp. He rejected that - and the consequences are there for all to see with the cultural compromise forced upon CFS.

And then there was the expectation that you've written about that, having won funds away from bank TD's we'd just recycle that back to them! (Mind you, on that matter we'd already had some practice because the former Colonial State Bank had also tried the same thing a couple of years earlier.)

The proposed CFS Group is more like what we originally put to the CBA as a better structure. (Not with mortgage broking of course!) It's only taken them 18 years to work out that Chris Cuffe and his team did have a clue about how to run a wealth management business after all!

Graham Hand
June 29, 2018

Hi Warren, indeed, you were one of the fund managers who put me in my place. "Does he know who he's talking to?" I thought, and apparently, you did.


Leave a Comment:

RELATED ARTICLES

CBA or global banks?

Can Aussie banks rediscover their glory days?

A six-chart snapshot of June 2022 lending data

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.