Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 548

Clock is ticking on a super free kick

The early part of each year is often a good time to review your investing strategy for the calendar year ahead and beyond.

And, with less than six months to go before 30 June, it’s also a good time to consider shorter-term opportunities. Sometimes it can be a case of use them or lose them.

Take this financial year, for example. For some Australians, there’s a concessionally taxed superannuation investment opportunity specifically hinged to the 2018-19 financial year that will expire on 30 June this year. By 1 July it will be gone.

The catch-up opportunity

Working Australians are allowed to contribute a maximum of $27,500 into their super each financial year at a concessionally taxed rate of 15%.

It’s a capped amount that includes the mandated super payments made by your employer plus any additional personal super contributions you choose to make to your super fund. However, in any given financial year, many people are unable to take advantage of the full $27,500 concessionally taxed contributions limit.

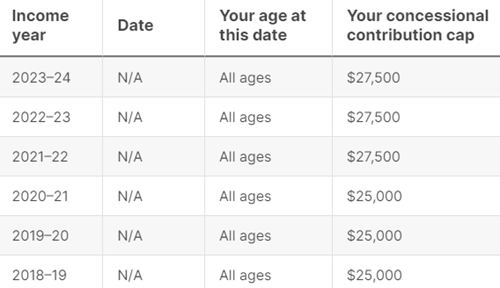
Back in 2016-17 the then federal government announced that from the start of the 2018-19 financial year it would allow eligible Australians to carry forward any unused annual concessional contribution amounts they have for up to five financial years.

Source: ATO

As such, the deadline for taking advantage of any unused concessionally taxed entitlements from the 2018-19 financial year is the end of 2023-24.

In many respects it’s a super free kick that’s there for the taking, at least for those Australians who are legally and financially able to do so.

Eligibility requirements

There are eligibility requirements for being able to take advantage of carry forward contributions from previous financial years.

To be eligible, you must:

  • have a total super balance of less than $500,000 at 30 June of the previous financial year.
  • have unused concessional contributions cap amounts available.

The good news is that if you are eligible, there’s nothing you really need to do. If you have the ability to make extra super contributions this financial year above the concessionally taxed $27,500 annual limit, any carry forward concessional cap amounts from previous financial years will be automatically applied by the Australian Tax Office (ATO).

If you haven’t used them already, the ATO will first apply any amounts from the 2018-19 financial year. It will then progressively apply any unused amounts from subsequent financial years.

A carry forward example

Let’s say you are still under the $500,000 total super balance and have some accumulated savings you’re willing to put into your super fund. Maybe you’ve recently sold an asset and now have some extra cash in the bank.

In the 2018-19 financial year you made $15,000 in concessional super contributions. Because the annual concessional contributions limit back then was $25,000, you would therefore have a $10,000 unused amount from that financial year. The annual concessional contributions limit wasn’t lifted to $27,500 until the start of 2021-22.

In each subsequent financial year you made $20,000 in concessional contributions, so you also have $10,000 from both 2019-20 and 2020-21, and $7,500 from both 2021-22 and 2022-23.

That gives you a grand total of $45,000 in unused concessionally taxed contributions spanning five financial years plus this financial year’s $27,500 limit.

If you were to exceed this financial year’s $27,500 by between $1 and $10,000, the extra contributions would be deducted from your 2018-19 carry forward amount. Any amounts over $10,000 would be deducted from 2019-20, and so on.

How do I find out if I have unused amounts?

You can easily check if you have unused concessional contribution amounts online via your myGov account by linking to the ATO.

After logging in, select Super - Information - Carry forward concessional contributions, and your unused balances by financial year should be viewable.

The caveats are that you must not have made concessional contributions in the financial year that exceeded your general concessional contributions cap and, as noted, your total super balance must be below $500,000 as at 30 June of the previous financial year.

Even though we’re now only around midway through the current financial year, it’s worth considering whether you can use this super free kick before 30 June 2024.

Consider an adviser

Super and retirement planning is a complex area. Take care to understand the contribution types and limits carefully as there are significant tax penalties for exceeding the applicable contributions caps. If you’re unsure about your super options before 30 June and need some advice, consider consulting a licensed financial adviser.


Tony Kaye is a Senior Personal Finance Writer at Vanguard Australia, a sponsor of Firstlinks. This article is for general information purposes only and does not consider the circumstances of any individual.

For more articles and papers from Vanguard Investments Australia, please click here.


  •   21 February 2024
  • 7
  •      
  •   
7 Comments
Alistair Mailer
February 22, 2024

Thanks for the article; Probable error in the 'carry forward' example :
In each of the 2019-2020 & 2020-2021 years there is only $5,000 available as unused carryover amount available ($25,000 limit less $20,000 contribution), not the $10,000 in each of these years as stated in your example. Hence grand total of only $35,000 in unused concessionally taxed contributions, not the $45,000 stated.

Tony Kaye
February 24, 2024

Alistair, apologies for my convoluted example. Here's my arithmetic:
2018-19 - Contribution of $15k left $10k to carry forward under previous cap (will roll off this financial year);
2019-20 - Contribution of $15k left $10k to carry forward under previous cap;
2020-21 - Contribution of $15k left $10k to carry forward under previous cap;
2021-22 - Contribution of $20k left $7,500 to carry forward under the current cap
2022-23 - Contribution of $20k left $7,500 to carry forward under the current cap
Total: $45k

Alistair Mailer
February 29, 2024

Hi Tony,
... But your article specifies a $20,00 contribution in the two years mentioned (2019-20 & 2020-21); quote from the article:
" In each subsequent financial year you made $20,000 in concessional contributions, so you also have $10,000 from both 2019-20 and 2020-21, and $7,500 from both 2021-22 and 2022-23."

Alistair Mailer

Jack McCartney
February 23, 2024

An interesting article. I followed your instructions regarding logging in to the myGov account and couldn’t find any details regarding the c/fwd concessional contributions for prior years per your steps above.
Could you advise how I can derive please.

Tony Kaye
February 24, 2024

Hi Jack, here's a step by step guide to see if you have any unused concessional contributions:
1 Login into the my.gov.au website
2 Click through to the Australian Tax Office (linked to your my.gov.au account)
3 Click Super in the menu
4 Click Information
5 Click Carry-forward concessional contributions
6 Scroll down the page to see any unused concessional contributions cap amounts available by financial year.

Jason mc
February 23, 2024

Who made Super so complex

Lee
February 25, 2024

Thank you, this was a great article Tony. I followed your steps, found I had an unused balance and adjusted my super contributions accordingly. Thanks again. :)


Leave a Comment:

RELATED ARTICLES

2024/25 super thresholds – key changes and implications

When losses in super become irreplaceable

Overcoming the fear of running out of money in retirement

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.