Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 409

Is crypto a currency or a collectible?

It is widely accepted that distributed ledger technology, such as blockchain, has enormous potential. It could be truly transformational for many industries and have a meaningful impact on how business is conducted globally. Bitcoin, the world’s largest cryptocurrency, is perhaps the most well-known example of something which makes use of this technology, and whilst there are strong opinions on both sides of the fence with regards to the merits of the technology, that conversation is best left for a different time.

Instead, the focus for investors at this point of the current crypto price cycle should be on how best to value cryptocurrencies and what a reasonable expected long-term return should look like.

The price that you pay for any asset is what really matters over the long-term for an investor and has also proven to be a reliable indicator for future returns. But how should you as an investor attempt to estimate what something such as Bitcoin is really worth?

A reasonable starting point would be to treat cryptocurrencies like any other asset and use the common valuation methods available to us. These typically include a discounted cash flow method or a sum-of-the-parts/asset-based approach. Unfortunately, given cryptocurrencies don’t pay any cash flows or own any tangible assets, neither approach is very helpful. Historical prices are also not useful, given many cryptocurrencies are new and the first Bitcoin was only traded in 2009. As a result, this makes cryptocurrencies difficult to value and therefore prone to speculation.

What is a reasonable return for currencies and collectibles over the long-term?

There are perhaps two useful ways to think about the long-term returns that you should expect from cryptocurrencies.

The first is to view them as a currency such as the US dollar, British pound or gold. Over the last 120 years (1900-2020), cash in the US and UK have achieved returns of around inflation plus 0.8% and 1% p.a. in US dollars respectively. Similarly, over the same time period, gold has produced a return of inflation plus 0.7% in US dollars.

The second argument commonly used is that the supply of something such as Bitcoin is limited and therefore there should be a premium for this scarcity. The same is of course true for your favourite antique watch or real estate in Greenland – just because it’s scarce doesn’t mean it’s valuable. However, let’s be charitable and assume that cryptocurrencies fall in the same bucket as rare stamps, coins, art, or diamonds. In other words, let’s treat cryptocurrencies as a collectible. Over the period 1900-2017, collectibles delivered a return of inflation plus 2% p.a. in US dollars. Therefore, if you believe that cryptocurrencies are either a currency or a collectible, history suggests that you should expect a return over the long-term of between inflation plus 1 to 2% p.a. in US dollars.

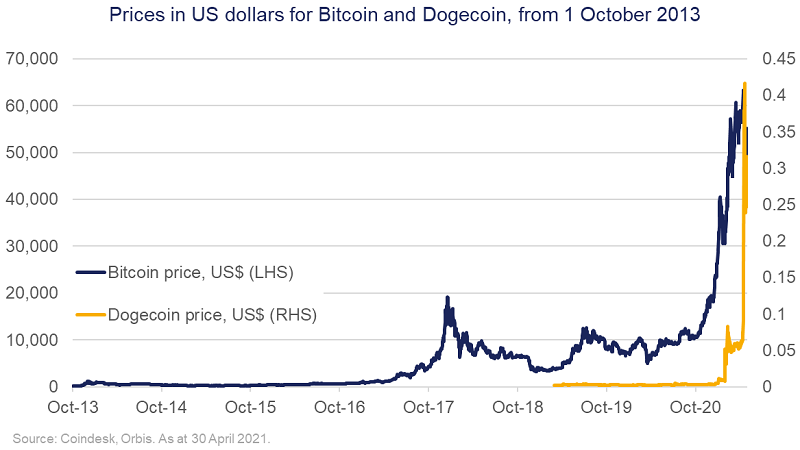
The graph below shows the price history in US dollars of both Bitcoin and Dogecoin. As you can see (this article was written before the full extent of the recent fall in Bitcoin and Dogecoin), they have both recently experienced enormous price increases. These returns are much higher than history would suggest is a ‘normal’ range for both currencies and collectibles, as explained above. This is particularly remarkable for Dogecoin given that it started as a joke on social media. At the time of writing, the market cap of Dogecoin was around US$60 billion, approximately the same size as ASX-listed companies, ANZ and Fortescue Metals, despite Dogecoin not producing any cash flows, products or owning any tangible assets.
What are the key ingredients required to form a speculative bubble?

As a result of these remarkable returns, many inexperienced investors have been attracted to cryptocurrencies, including people who have never invested before. And this creates a virtuous flywheel: new people join the game, prices rise, they talk about it, the fear of missing out or ‘FOMO’ attracts more investors, and prices rise further.

According to a recent Harris Poll, nearly 1 in 10 Americans used their stimulus cheques to invest in cryptocurrencies. Perhaps the speculative behavior seen in parts of financial markets more recently, such as cryptocurrencies, shouldn’t come as any surprise.

You could argue that we have created the perfect recipe to encourage speculation with three key ingredients.

Firstly, there is an abundance of liquidity. Globally, there are many people who are either unemployed or underemployed, but unusually they also have money in their pockets thanks to government and central bank support. Moody’s estimates that there is currently around US$5.4 trillion or more than 6% of global gross domestic product (GDP) in excess savings. In other words, savings that people would not have if the COVID-19 pandemic had not occurred.

The second feature is lockdowns. As a result of the COVID-19 pandemic, many parts of the world either have had or currently have lockdowns. People therefore haven’t been able to spend this excess money in the usual places given that travel is banned, restaurants and bars are shut, cinemas and theme parks have been disrupted, and casinos have also been closed. Live sport (and as a result sports betting) has also been halted in many parts of the world. However, financial markets is one area that people have still been able to participate (and speculate) in.

And finally, perhaps the most important recipe for a speculative bubble to form is something new and shiny to attract an investor’s attention. If one looks at past speculative periods, one thing you will notice is that many of these periods were associated with things that were brand new. For example, new flowers in the Dutch Tulip Mania in the 1600s, new forms of transport in the Canal and Railway Manias in the 1790s and 1840s, and the creation of the internet in the Dotcom bubble in the late 1990s.

Perhaps we will look back in time and say that in the 2020s, it was digital currencies. But investors should always be wary whenever an asset delivers a return which is well above what history would suggest is ‘normal’.

When investors all head in one direction, it can often be safer to go the other way. Of course, this is highly uncomfortable but as contrarians we believe that discomfort is the reason so few do it. Those who go the other way may be highly rewarded, although remaining disciplined in an environment like this of such excess returns isn’t easy. 


Shane Woldendorp, Investment Specialist, Orbis Investments, a sponsor of Firstlinks. This report contains general information only and not personal financial or investment advice. It does not take into account the specific investment objectives, financial situation or individual needs of any particular person.

For more articles and papers from Orbis, please click here.


  •   26 May 2021
  • 8
  •      
  •   
8 Comments
Anthony Asher
May 26, 2021

A bit unfair to blame the unemployed. As an ex-lecturer I am rather ashamed to find that some graduates have fallen for this nonsense. There is no real value in cryptocurrencies; they are a scam perpetrated and perpetuated by existing holders and those making money from the exchange of real currency. Part of the problem are the silly theories that government issued currency has no real value either. This is where MMT helps: "So why, then, does the government tax, under the MMT view? Two big reasons: One, taxation gets people in the country to use the government-issued currency. Because they have to pay income taxes in dollars, Americans have a reason to earn dollars, spend dollars, and otherwise use dollars as opposed to, say, bitcoins or euros. Second, taxes are one tool governments can use to control inflation. They take money out of the economy, which keeps people from bidding up prices." https://www.vox.com/future-perfect/2019/4/16/18251646/modern-monetary-theory-new-moment-explained

Ruth
June 01, 2021

After looking at MMT for 4 years, I consider it to be complete state control of what should be the people's money. MMT does not get people to use fiat currency, it forces them to. It considers the government owns the currency. MMT bureaucrats interfere with the allocation of capital which the private sector is best equipped to do. Bureaucrats are not qualified to make these decisions and have no accountability. If it is introduced here, I will put my currency into any other alternative as I think that under that 'theory' the fiat supply will become worthless.

DK
May 26, 2021

I guess the thing I have been struggling to understand, which I think is a sustained determinant of value, is of what use are any of the crypto currencies?

Setting aside security concerns of the different ones available, which are actually being incorporated into payments for goods and services and where is that trending?

Mark Hayden
May 26, 2021

I agree that it is either a collectible (my preference) or a currency and I like Shane's analysis of the long-term returns for both alternatives. My view is that no-one "needs" to own a crypto-currency, as they can achieve their goals via other investments and without ever needing to spend any time (or money) on crypto-currency.

Rudy Boeff
May 26, 2021

The day I can buy groceries, fuel for my car or make my monthly mortgage payment with cryptocurrency will be the day I start to look at this sector seriously from an investment perspective. While this day may not be far away given the increased popularity of cryptocurrencies, until then, I'd rather invest in a classic car or piece of art that I can actually touch and enjoy.

Tony Dillon
May 27, 2021

To describe cryptocurrency as money is a stretch. Rather it is an imaginary commodity at best, with price bid up and down on a whim. And nothing of any value backs it, nor has anything of value been created, apart from maybe bringing blockchain technology to the fore.

Fred Bell
June 01, 2021

I feel very uncomfortable that cryptocurrency is so invisible (i.e. You cannot see it or touch it) and is like gambling on a racehorse eg huge wins or complete losses. The share market may fall but at least you still have something tangible to hold onto. Could I suggest that the Buyer beware, as this could be the scam of the century ??

DK
June 07, 2021

As a further comment, where is ASIC in all of the social media promotion of cryptocurrencies by influencers, I am guessing these people are not licenced to provide personal or general advice as they are not complying with any of the associated requirements in their influencing activities?


Leave a Comment:

RELATED ARTICLES

A reluctant investor’s guide to understanding bitcoin

Opening the virtual frontier: Senator Hume’s address to Blockchain Week

Understanding and investing in cryptocurrency

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.