Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 265

Why dividend yields in Australia are so high

People often ask me why listed company dividend yields in Australia are so high. The average dividend yield across the Australian stock market is currently 4.1% or twice the world average. It is the highest in the world apart from Russia, Portugal, Turkey, UAE, Qatar and Nigeria.

There is a good reason for this. In the early stages of a country’s development, dividend yields start at high levels because investors are nervous about getting their money back if they have to wait too long. In the 1880s, dividend yields in Australia and the US both ran at 6% to 8%. As a country matures, investors develop trust in the corporate sector’s ability to invest wisely for future growth and so they let boards retain more of their profits to invest, and pay less back as dividends. In this sense, Australia is still like an early stage emerging market.

A history of reckless spending

Investors have a well-deserved distrust of Australian directors' and CEOs' ability to invest excess cash wisely, and so they demand profits be returned as dividends instead. Australian companies have a long history of wasting money on ego-boosting projects, usually in the form of reckless overpriced overseas ventures undertaken in booms. Then they are forced to sell, close or give the assets away after wasting billions of dollars. This trait has infected our big banks, miners, telcos, retailers, and hundreds of other companies. Success stories like Westfield, Macquarie, CSL, Seek, Cochlear, Sonic and Computershare are rare exceptions in a sea of red ink from failed expansions.

Australia is a small country in the middle of nowhere, and our directors find it hard to resist the temptation to chase the dream of free travel and adventure in pursuit of fame and fortune, all with shareholder money! Grand plans are usually hatched at the tops of booms, often with debt, with assumptions that prices will keep rising forever. They never do of course.

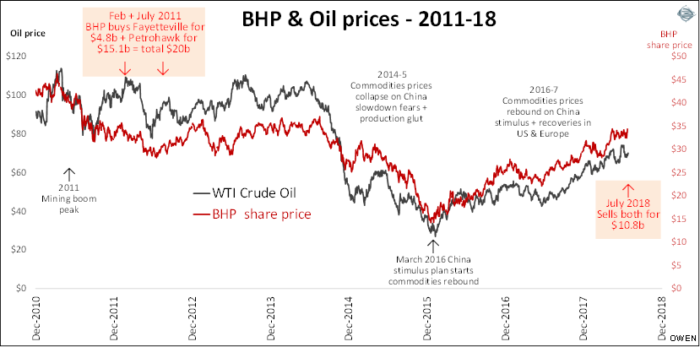
At the top of the 2011 mining boom when oil prices were above $100 per barrel, BHP spent $20 billion buying two shale oil operations in south eastern USA – Fayetteville for $4.8 billion and Petrohawk for $15 billion. BHP’s CEO was South African former management consultant Marius Kloppers, and Chairman was former Ford CEO Jac Nasser. Nasser had spent his career at Ford begging Canberra for handouts for Ford Australia, and begging Washington for handouts for Ford US. Neither knew much about mining or running profitable businesses without taxpayer support. BHP then spent the next six years throwing even more money at the troublesome projects while progressively writing off billions.
Click to enlarge

In theory, shareholders appoint the custodians of their companies

Finally last week, BHP announced the sale of both projects - Fayetteville for just $300 million and Petrohawk for $10.8 billion. At the same time, it wrote off another $3 billion, bringing losses to around $20 billion. That’s US dollars, not Australian dollars!

In the meantime, CEO Kloppers was fired and replaced by Scotsman Andrew Mackenzie, a real miner, and Chairman Nasser was replaced by former Amcor CEO Ken MacKenzie, with real experience running a very profitable business.

It is good to see BHP back in good, or at least better, hands once again. But we still don’t trust them. Thankfully, they are handing back all of the cash proceeds of the Petrohawk and Fayetteville sales to shareholders. They are also paying out record dividends from the windfall recovery in commodities prices over the past two years. The BHP share price is drifting up again, mainly because prices of commodities are rising, not because of good management.

The scary thing is that it could have been much worse. Kloppers and Nasser tried to use BHP to take over rival miner Rio Tinto for $150 billion in early 2008 when the iron ore price was at its all-time peak of $200 per tonne. It is now just $65 per tonne, and Rio was rescued by the Chinese government.

The problem is we can’t blame the CEOs, directors and chairpersons for bad decisions even if they had no relevant experience when there were appointed. In theory, they are put there by shareholders, so that’s where the blame lies. In reality, it is a cozy club because the big shareholders – which is mainly the big institutional super funds – stand by idly and let it happen. For small shareholders, it is easier to just watch from a safe distance and get out when we see trouble brewing.


Ashley Owen is Chief Investment Officer at advisory firm Stanford Brown and The Lunar Group. He is also a Director of Third Link Investment Managers, a fund that supports Australian charities. This article is general information that does not consider the circumstances of any individual.


  •   2 August 2018
  • 5
  •      
  •   
5 Comments
Hank
August 02, 2018

I would have thought the tax system in conjunction with a massive superannuation pool plays a major role in the high level of payouts in both absolute & relative terms

Peter Thornhill
August 02, 2018

I can think of no better endorsement of dividends versus retained profits. The episodes of misuse of shareholders money by megalomaniac CEO's are legendary.

hank
August 02, 2018

I would have thought that tax policy in conjunction with a massive pool of superannuation money and high levels of retail share ownership may have a significant impact ??
(think imputation, significant SMSF sector, deductibility of interest & tax credits)

David Heath
August 02, 2018

Good article Ashley. Your criticisms of individual companies applies to the whole of Australia and governance. The ASX has gone up around 4 times over 30 odd years compared to 12 times for the Dow and around 60! times for the Nasdaq. Australian property is up around say 8 times over the same period. This is extremely strange as the risk premium for property is lower than for stock market investments. In addition if we take the last 10 years the ASX is up around 20% (Dow 110%) compared to inflation of around 30% so individuals who sell the overall market now pay CGT on real losses! The relative difference in the treatment of CGT between property and the ASX is one of the reasons why the ASX has underperformed compared to property. If Labor increases the CGT to around 36% at the highest marginal rate this would be close to the highest in the world - and still not indexed for inflation - which is the reason for the current 50% discount - I think I will move to NZ or Switzerland if I can get in! In Australia we seem happy to pay an extra $100b per year in financing costs (Australian banks are still five times bigger than in the US in terms of relative market cap - for doing the same work!) in oder to save a default of say $20b that might happen once every 10 years!

Gen Y
August 03, 2018

You can hardly create the link between Australia having a 'developing sharemarket' and high dividends... You could argue our share market is one of the most developed in the world given we all have significant exposure to it through our Superannuation.

It is Tax, Tax, Tax and Tax. Most companies offer generous dividend reinvest terms, why? Because it is in many investor's best interest to wash the money through as a dividend with the fat refundable tax credit, then it is for the company to simply reinvest those profits. Many companies also complete Capital Raisings whilst also paying out a high proportion of profits as dividends, again for the same reasons.

Trying to create a link between anything else is just incorrect.


Leave a Comment:

RELATED ARTICLES

Digging for value among ASX miners

The challenges with building a dividend portfolio

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.