Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 521

The drawbacks for SMSFs moving funds into cash

Investment trends can sometimes be hard to pick, but the huge and ongoing investor cash inflows into Exchange Traded Funds (ETFs) that invest in fixed income securities such as government and corporate bonds is difficult to miss.

Fixed income inflows are currently running at a record pace, largely thanks to deteriorating economic conditions that have spurred a spike in interest rates. Higher interest rates are translating into higher fixed income returns.

Over the first half of this year, investors in the United States poured US$99.4 billion (A$144.3 billion) into fixed income ETFs, according to Morningstar. Meanwhile, European demand for fixed income ETFs hit record levels as investors added US$36 billion (A$52.2 billion) into listed bond funds.

Australian fixed income inflows also surged over the six months to 30 June 2023, according to data from the Australian Securities Exchange (ASX) and separate data from Vanguard. In Australia, the combined inflows into Australian-listed ETFs that invest in bonds exceeded the inflows into ETFs that invest in domestic and global shares. That’s despite the strong first half rally on global equity markets, including on the ASX.

Collectively, investment inflows into Australian and global fixed income ETF products totalled $2.49 billion over the first half, which compared with inflows of $1.56 billion into Australian and global equity ETF products.

SMSFs become more defensive

This uplift in fixed income inflows is also likely to extend to the investments being made by Australia’s self-managed superannuation fund cohort.

The 2023 Vanguard/Investment Trends SMSF Investor Report, released in June, found that many SMSF investors had started to increase their allocation to defensive assets in general. Conducted between February and March 2023, the annual report now in its 18th year represents the largest scale quantitative survey of Australian SMSF investors.

According to the report, one in five SMSFs acknowledge that the prevailing economic conditions have had a significant impact on their approach in selecting investments, with over a third of SMSFs indicating an increased allocation to cash and cash-like products.

Direct shares have seen the largest relative decline in terms of SMSF asset allocation on a dollar-weighted basis. Of the SMSF survey respondents, 36% said they had rebalanced their investment portfolio in the past year by between 10% and 50%. This had resulted in their average asset weighting to direct shares declining from 36% in 2022 to 31%, as shown below.
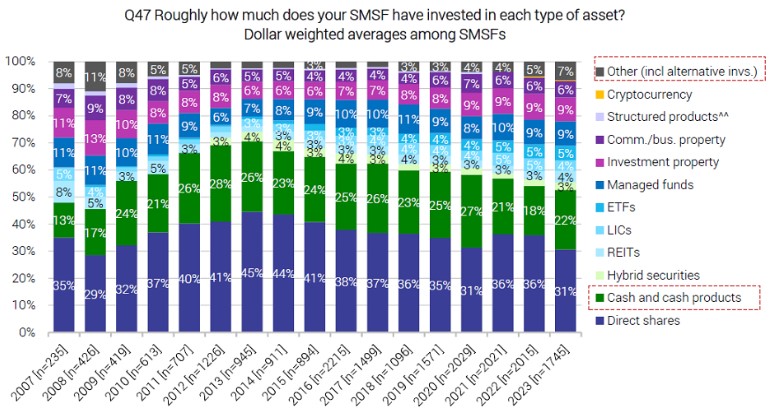
The primary reasons cited for this were because SMSF trustees had adopted a more defensive stance and had a negative outlook on overseas shares. With the current unsettled economic landscape of high interest rates and inflation, capital protection remains a priority for most SMSFs.

It is typical to see increased allocation to defensive assets such as fixed income or cash products during uncertain times. With interest rates rising, the data suggests SMSFs are favouring assets that they see as low risk.

The bottom line on cash

There is a common misconception that cash is a risk-free asset. While it is not prone to daily market volatility like shares are and is highly liquid, cash does have inherent investment risks.

A decade of record-low interest rates has meant that cash as an asset class has delivered an average annualised income return of just 1.9% since 2012. That’s lower than any other major asset class.

Worse still, after taking high inflation levels into account, hovering between 5% and 7% at time of writing, real cash returns have been negative for some time.

Although rising interest rates have created short-term pain for Australian investors, they have helped to improve long-term return expectations for bonds.

While bond prices typically reprice lower when interest rates rise, investors with a sufficient long-term investment horizon will ultimately be better off.

Investors are also flocking to bonds in their search for diversification and income as yields continue to stabilise (a signal that investors are becoming more optimistic), presenting an attractive alternative to holding cash which has generally underperformed bonds post rate hike cycles.

Being slightly higher-risk than cash, bonds are generally expected to outperform cash over the long term. As of June this year, Vanguard’s median annualised return expectations for Australian and global bonds ex-U.S (hedged to Australian dollars) over the next decade were 3.4% to 4.4%, and 3.6% to 4.6%, respectively.


Balaji Gopal is Head of Personal Investor and Financial Adviser Services at Vanguard Australia, a sponsor of Firstlinks. This article is for general information purposes only and does not consider the circumstances of any individual.

For more articles and papers from Vanguard Investments Australia, please click here.


  •   9 August 2023
  • 2
  •      
  •   
2 Comments
Simon
August 12, 2023

I don't get why anyone would waste their time investing in bonds with a 4.5% yield - and that is presumably before management fees - when there are numerous bank savings accounts offering 5% with no fees and no volatility.

Ramani
August 13, 2023

The increased allocation to cash might be due to investment uncertainty (the present seems eternally volatile), reversion to normal minimum rates from 2023/24, members moving to a higher minimum bracket, publicised property sector collapses and need to rollover to an APRA fund or avoid the punitive 17% proxy death duty on super paid to tax non-dependents.

As with navigating non super assets during twilight time, a prudent estimate of cash flow needs allowing for health, relationship and capital demands and cashing up (dollar cost averaging on disinvestment) would help, but remembering that non super assets and all of liabilities must be included.

Cash risks exposing the nest egg to inflationary loss of value and opportunity loss of investing in more aggressive assets.
Government bonds, often touted as ‘safe’ are less so when sovereign country risk (remember the Asian and Global Financial Crises when once reputed governments quickly descended into insolvency), currency risk (easily manipulated by the Gordon Gekkos and greedy finance ministers) and interest rate risk ( as yields rise) are factored in.

There is no magic bullet. We should console ourselves that these are problems of having a nest egg. The Bangladeshi family buffeted by Brahmaputra floods is not so lucky.

Schadenfreude!


Leave a Comment:

RELATED ARTICLES

Who really loses from the SMSF borrowing ban?

Meg on SMSFs: Withdrawing assets ahead of the $3m super tax

Navigating SMSF property compliance

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.