Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 558

Exploiting Warren Buffett

Warren Buffett and his former offsider Charlie Munger are treated like investing royalty, and rightly so. Yet, their success also makes them valuable marketing tools. For journalists looking for headline clickbait. For fund managers looking to bask in their wisdom and afterglow. And likewise for CEOs.

It’s a newer trend which disturbs me more. That is, of growth investors selectively quoting Buffett and Munger to justify their purchases of ‘wonderful’ businesses, or compounders.

Invariably, the story is told of how Munger turned Buffett from a Ben Graham-type value investor into a growth investor. It’s supported by quotes from Buffett like these:

“It’s far better to buy a wonderful company at a fair price, than a fair company at a wonderful price.”

“If a business does well, the stock eventually follows.”

“Only buy something that you’d be perfectly happy to hold if that market shut down for 10 years.”

As well as by quotes from Munger like this:

"Over the long term, it's hard for a stock to earn a much better return than the business which underlies it earns. If the business earns 6% on capital over 40 years and you hold it for that 40 years, you're not going to make much different than a 6% return—even if you originally buy it at a huge discount.”

Growth investors are rightly basking in a golden era where their style of investing has crushed indices. Since the GFC, growth investing has reined supreme, while the likes of value have been pulverised. Fast growing companies such as the ‘Magnificent Seven’ in the US, and Cochlear, Pro Medicus, and Technology One in Australia have delivered incredible returns for shareholders.

Yet the past isn’t the future, and one key component of Buffett and Munger’s investing is increasingly being ignored: that buying stocks at the right price matters too.

Here’s Buffett on the topic:

“Price is what you pay. Value is what you get.”

“For the investor, a too-high purchase price for the stock of an excellent company can undo the effects of a subsequent decade of favourable business developments.”

“The three most important words in investing are margin of safety.”

“Most people get interested in stocks when everybody else is. The time to get interested is when no one else is. You can’t buy what is popular and do well.”

And here’s Munger:

“You’re looking for a mispriced gamble. That’s what investing is. And you have to know enough to know whether the gamble is mispriced. That’s value investing.”

The growth mantra

Let’s look at an example of what I’ll call the ‘growth investing mantra’. Last week, Rudi Filapek-Vandyck wrote an article for Firstlinks on the virtues of buying wonderful businesses like CBA. Rudi is a quality thinker and writer, though I respectfully disagree with some of his conclusions.

In the article, Rudi suggests that the reason that US markets have crushed Australia’s since the GFC is because they have a greater number of high-quality businesses. That’s undoubtedly correct.

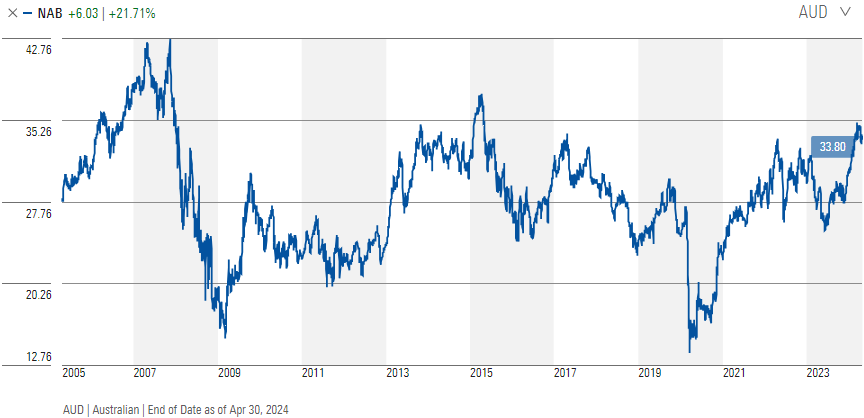
He goes on to say that Australia still has some quality growth stocks. He compares CBA to the rest of the major banks. Over the past 20 years, NAB has delivered minimal returns, ex dividends.

Source: Morningstar

Westpac has done a bit better. From the bottom of the GFC, it’s risen 4.7% per annum. Including dividends and franking, brings that return up to 9-10%. Yet, most other timeframes other than from the bottom of the GFC would have delivered little in returns for investors.

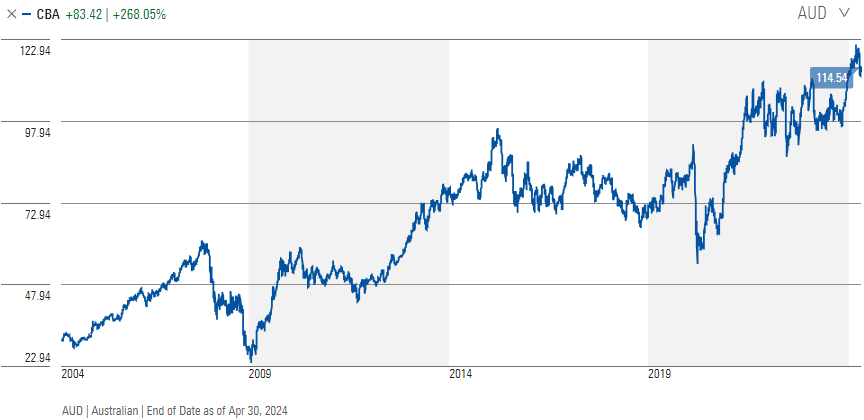
Compare that to CBA. From March 2009, it’s returned 22% per annum, ex dividends.

Source: Morningstar

It’s quite the contrast. And what accounts for the very different returns from CBA versus the other banks? According to Rudi, it’s the quality of CBA compared to the rest. And he says that CBA has been the most expensive bank throughout that 16-year period, and it’s still delivered the best returns. The lesson? Buy the best companies.

What’s missing?

What he doesn’t mention though is that earnings growth for CBA has been mediocre since the GFC. Diluted earnings per share (EPS) was 313.4 cents in 2009, and that went up to 601.4 cents last financial year. That’s an EPS compound annual growth rate of 4.4%. If we reduce the timeframe from 15 years to the last decade, EPS has compounded at an annual rate of 2.32%.

In other words, the bulk of the fantastic returns of CBA over the past 15 years has come from multiple expansion – the multiple that investors have been willing to pay for those CBA earnings.

When CBA bottomed in March 2009, it traded under $25. Then, the price-to-earnings ratio (PER) was around 8x 2009 earnings, or less than 7x 2008 earnings. The stock was dirt cheap at that stage.

Since then, the PER has risen to a peak above 20x in March this year, and it’s just under that now.

The upshot is that there is a vast difference in the valuation attached to CBA now versus 2009. Today, the shares trade for almost 3x the multiple they did back then. Your starting point today is that you’re paying almost 20x earnings for a stock growing EPS at 2% per annum.

CBA’s potential returns over the next decade

What can we expect for returns from CBA over the next 10 years? We can use a simple but useful formula:

Expected returns (nominal, annualized over the next 10 years) = Starting dividend yield + Earnings growth + percentage change (annualized) in the PER multiple.

CBA’s dividend yield is 3.78% and if we plug in 2.32% EPS growth, as it’s averaged over the past decade, that gets us to total annual returns of 6.01%.

Of course, earnings going forward are dependent on numerous things, and past earnings may not be indicative of future ones. I’d argue that the earnings assumption is probably realistic. The past decade has delivered an enormous housing boom that’s fuelled CBA’s loan book. Yet, it’s also suffered from poor margins due to low interest rates throughout much of the period. Costs have also spiked from increased technology spend and more recently, wages.

Looking ahead, margins should improve as rates stay higher, though that may be crimped by the increased competition for deposits from the likes of Macquarie. On the other hand, it’s harder to see the housing boom being replicated, and bad debts staying as low as they have been.

A big swing factor for returns will be whether CBA can retain its current PER multiple of ~20x. If it does, then shareholders can expect around that 6% in total return, provided my earnings assumption proves right. If the multiple is cut to 15x, and assuming the same earnings growth, then expected total annual returns would fall to just 3.8%.

Whether you use heroic or conservative earnings assumptions, the maths suggest that CBA won’t deliver anything but mediocre to poor returns over the next decade. And it’s principally because the current share price is exorbitant for a slow growing stock.

Other market darlings

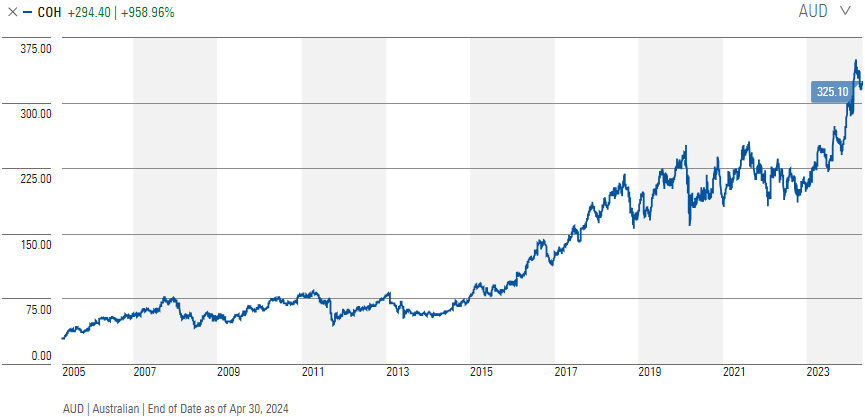
With growth stories scarce in Australia, investors seem willing to pay up, and then some, for a select group of other stocks too. For instance, Cochlear is trading at a cool 46x next year’s earnings. That’s for a stock that’s grown EPS at 9% and 7% per annum over the past five and ten years respectively.

Source: Morningstar

Cochlear’s PER equates to an earnings yield of just 2.17% (earnings yield is the inverse of PER, or earnings divided by price). That earnings yield is under half the 10-year Australian government bond yield, or risk-free rate, of 4.5%. In other words, you can invest in a risk-free bond at more than 2x the yield that you’ll get from investing in Cochlear.

Cochlear is also trading at a steep premium to most of the Magnificent Seven tech stocks in the US, which are growing much more strongly. For example, Nvidia is trading on a forward PER of 36x, and Microsoft is at 29x.

On a lot of fronts, Cochlear’s pricing doesn’t make sense. And that will impact its future returns. If the PER drops from the current 46x to 30x, that will shave almost 5% per annum off total returns over a 10-year period. Investors will need very strong earnings growth over that period, or the multiple to stay near where it is now, for the stock to return anything close to the ASX 200 over that same period.

That also assumes that the business doesn’t trip up during that time, which is far from a sure thing.


James Gruber is an assistant editor at Firstlinks and Morningstar.com.au.


  •   1 May 2024
  • 16
  •      
  •   
16 Comments
Dudley
May 02, 2024

"CBA. From March 2009, it’s returned 22% per annum, ex dividends":

ADJusted for dividends, splits, etc, and Indexed to 100:

CBA:
https://www.marketindex.com.au/asx/cba/advanced-chart
= (842.84 / 100) ^ (1 / ((DATE(2024, 5, 2) - DATE(2009, 3, 2)) / 365.25)) - 1
= 15.1% / y

NAB:
https://www.marketindex.com.au/asx/nab/advanced-chart
=(497.65 / 100) ^ (1 / ((DATE(2024, 5, 2) - DATE(2009, 3, 2)) / 365.25)) - 1
= 11.2% / y

Tim
May 03, 2024

Yeah, 22% p.a. ex dividends doesn't look correct for CBA. Using the XIRR function on excel gives 8.3% p.a. ex. divs and 15.9% p.a. inc. divs (31 dividends from March 09 to present, totaling $57.66 per share).

Rudi Filapek-Vandyck
May 06, 2024

Hi Dudley (and Tim), maybe the following numbers will show the message from my story:

-Total return over 15 years, ex dividends:

-CBA = 338%
-ANZ = 135%
-NAB = 103%
-Westpac = 71%

As per always, we can discuss angles and commas, but those are the blanket facts. And THAT was the message from my story (included last week)

Dudley
May 06, 2024

2029/Feb/2 to 2024/May/1:
https://www.marketindex.com.au/asx/cba/advanced-chart

'Total' return multiple:
Symbol: excluding dividends, including reinvested dividends (and splits etc):
CBA: 3.997 8.8865
ANZ: 2.188 5.0695
NAB: 1.9176 4.6987
WBC: 1.7397 4.0814

They all offer barely competitive deposit interest rates. Some rates being extremely anti(?)-competitive.
CBA used to offer good rates, but have not for 15 years. They found cheaper source of funds.

My ignorant opinion is that their lending rates are also barely competitive.

Dudley
May 06, 2024

"2029/Feb/2" --> 2009/Feb/2

Craig Ellis
May 02, 2024

Whilst the theory stacks up James, the reality is a limited free float created by a trillion dollar super pool hunting for assets (11c in every dollar every day) ,mums and dads who bought CBA at $5 and will never sell "coz CGT".

Rob
May 03, 2024

That's me to a tee Craig. Have an average buy price on CBA of $45 (5000 shares) and an average buy price on COH of $20 (2000 shares). I've never sold any CBA and only sold some COH to manage CGT and pay for a house deposit.

Charlie H
May 03, 2024

I suppose the issue is there is so much money chasing so few growth stocks. We need more good quality stocks on the ASX.

David
May 05, 2024

As soon as the small good ones grow, they get bought out by foreign owners.

Ed Heath
May 04, 2024

CBA has a lot of intrinsic strength in its business franchise
1. Approx. 25% market share in key segments and historic business strength for past 100 years.
2. Better managed
3. Higher quality workforce
4. Buy of last resort when other financial institutions go belly up
5. At least 5 years ahead of key competitors in business & technology back office functions
6.Implicit Govt Guarantee & Protection in bad times
7. Australian public has implicit faith in CBA franchise & its viability

With so much in favor, only question remains is how much premium to pay for CBA shares?
Mathematical calculations on CBA trailing returns only throw light on past.

Leslie
May 05, 2024

Very insightful and clear article, thanks James!

Peter Thornhill
May 05, 2024

Oh dear. I hadn't realised how disappointed I should be but then again I stupidly spend little time digging into my holdings; careless really but I'm only interested in the dividends appearing in our bank account.
Thought I should check. Present value
CBA- Bought in 2001; over time, total invested $113K and divs todate are $230K total return 13% p.a. $346K
COH- Bought in 1995; over time, total invested $106K and divs todate are $130K total return 23.1%p.a. $990K
CCP- Bought in 2000: $151K $478K 27% p.a. $995K
CSL- Bought in 2002 $179K $236K 23% p.a. $1,930K
These crackers at least this help cover the few shares I bought that went bust. Our super fund adminstrator informs me that since inception in 2000 our super fund has returned 10.5% p.a. compared to the ASX 200 Accum at 7.5% over the same period. As an aside, the issue of yield drives me nuts. A high yield does not ensure the best income. My best dividend payers are the lowest yielding. Go figure.

Rob
May 07, 2024

Hear, hear!
Agree with every word of this comment. I really don't care too much about price movement, my wife and I live off the $220k of gross dividends we get year in, year out, even accounting for GFC and Covid dips.

Rudi Filapek-Vandyck
May 06, 2024

It looks like my story (in last week's edition) has inspired the story above. I'd like to point out my story never advocated investors should buy anything at any price.

What my research does prove, and what became the essence of my story, is that investing in quality companies is the surest strategy for superior returns, rather than buying 'cheap' shares because, well, they look 'cheap'.

And that is the exact message of the quote from Charlie Munger I referred to. CBA is oft referred to as the highest quality bank in Australia. That's why its shares trade at a premium versus the others.

What typical value investors find hard to understand is that the 'cheaper' alternatives do not by default generate the better return, outside, maybe, a short-term catch up.

That is exactly what my story illustrated, and frankly, it is difficult to argue with the differences in return over the past 15 years.

But none of the above says CBA at its current price is 'fair value' or that I am mis-quoting Charlie Munger (I believe I am not).

While CBA shares had become 'cheap' at the depths of the GFC, they have consistently traded at a premium throughout the 15 years since. It has never prevented those premium-priced shares from offering shareholders the superior reward in the sector.

That is the core essence of my research/message/analysis. The cheapest stock does not offer the best return. It's most likely the better quality, less-cheaply priced (at a relative premium) stock that returns the most, if time is allowed to do its work.

I am aware this is a shock to your typical value-inspired investor mindset, but that doesn't make it untrue.

This is, and remains, the outcome from my 'Quality'-oriented research, backed by many more examples outside of the local banking sector. Try REA Group versus Domain, or Aristocrat Leisure versus Ainsworth Gaming, etc. By the way, Macquarie beats all of the local banks, handsomely, and that's not coincidence either.

Finally, and this is why every investor should pay attention: I do not believe the next ten years will be fundamentally different from the past decade. If anything, the difference between High Quality and Low(er) Quality might well become even more pronounced.

And, indeed, this means stocks valued on a relative premium, assuming they are truly of High Quality, will continue to generate superior returns. Unless shares are pricing-in excessive exuberance.

The latter will always be something investors need to be mindful of. Goes without saying.

James Gruber
May 06, 2024

Hi Rudy,

Thanks for your comments. Your article wasn't the trigger for this one; it was more an inbox full of buy x compounder at 40x because quality will always pay off. In hindsight, I regret elaborating on yours as it's a more thoughtful and rational perspective.

One thing I didn't have space to mention here is the academic literature on quality as a style factor. Generally it concludes that yes, quality has outperformed many other styles over time. However, the timeframes for the research of up to 50-60 years are short in the scheme of things, and therefore not entirely conclusive. The other point is that quality often underperforms other factors including value over long stretches of time.

The point of my article is that quality and momentum have outperformed other styles for a long period now, and that won't continue indefinitely. And that will surprise a lot of investors who are currently blindly buying 'quality' stocks.

It's also worth noting that Charlie Munger also expressed in his last years that his style of investing had become exceedingly popular and he was wary of that. Also, he refused to recommend for people to buy Costco, of which he was a director, even though he thought it one of the best companies in the world, principally because he believed it to be fully priced.

Buying quality is great; even better when it's with a margin of safety.

Best,
James

Blake B
May 06, 2024

Buffett's comment at his annual meeting was telling:

“I don’t think anyone at this table has any idea of how to use it [US$189B in cash] effectively, and therefore we don’t use it. We only swing at pitches we like… today things aren’t attractive. We’re not using it at 5.4%, but I wouldn’t use it at 1% either. But don’t tell the Federal Reserve that.

I don’t mind at all, given current conditions, building our cash position. When I look at the equity markets and the composition of what’s going on in the world, we find cash quite attractive.”


Leave a Comment:

RELATED ARTICLES

Are term deposits attractive right now?

On the virtue of owning wonderful businesses like CBA

Retail investors aren't buying the dip

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.