Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 193

Governments fund more research than we realise

[Editor’s Note: For background, CEPAR is the ARC Centre of Excellence in Population and Ageing Research. ARC stands for Australian Research Council, an Australian Government entity whose mission is to deliver policy and programmes that advance Australian research and innovation globally and benefit the community].

Understanding the changes in our population and its demographics are vital inputs when planning our retirement systems. On 8 September 2016, ARC awarded CEPAR $27.25 million in funding to finance a second research term of seven years. This is a significant achievement and the many people involved, notably Professor John Piggott (Centre Director) and Marc de Cure (Chair of CEPAR’s Advisory Board), deserve congratulations.

To put this win into context, consider the other eight winners of ARC funding:

  • ARC Centre of Excellence for All Sky Astrophysics in 3 Dimensions
  • ARC Centre of Excellence of Australian Biodiversity and Heritage
  • ARC Centre of Excellence for Climate Extremes
  • ARC Centre of Excellence for Engineered Quantum Systems
  • ARC Centre of Excellence for Gravitational Wave Discovery
  • ARC Centre of Excellence in Exciton Science
  • ARC Centre of Excellence in Future Low Energy Electronics Technologies
  • ARC Centre of Excellence for Quantum Computation and Communication Technology

Reactions may include awe at the complexity of some of the topics and the breadth of research areas supported by government funding. A large number of top quality applications were unsuccessful, and I agree wholeheartedly with Piggott’s comment that “population ageing is an issue of paramount importance to all; this is truly the ageing century”.

CEPAR is a good example of collaboration:

  • From a research perspective, while based at UNSW Australia, it applies a best practice model and has research members from the Australian National University, the University of Sydney, the University of Melbourne, the University of Western Australia, the University of Manchester, the University of Pennsylvania and the Wharton School.
  • CEPAR has a collaborative funding model, receiving additional funding from industry and government partners including the major Commonwealth policy departments, large corporates, and the NSW Government. CEPAR also has strong support and engagement with the World Bank, OECD and COTA.

CEPAR’s multidisciplinary approach draws on expertise in actuarial studies, demography, economics, epidemiology, organisational behaviour, psychology and sociology. Piggott explains, “CEPAR’s research programmes are assembled into four interconnected streams, that cover demographic modelling; decision making, expectations and cognitive ageing; work design and successful ageing in the workforce; and sustainable wellbeing in later life. The latter including not only physical but financial wellbeing as well.”

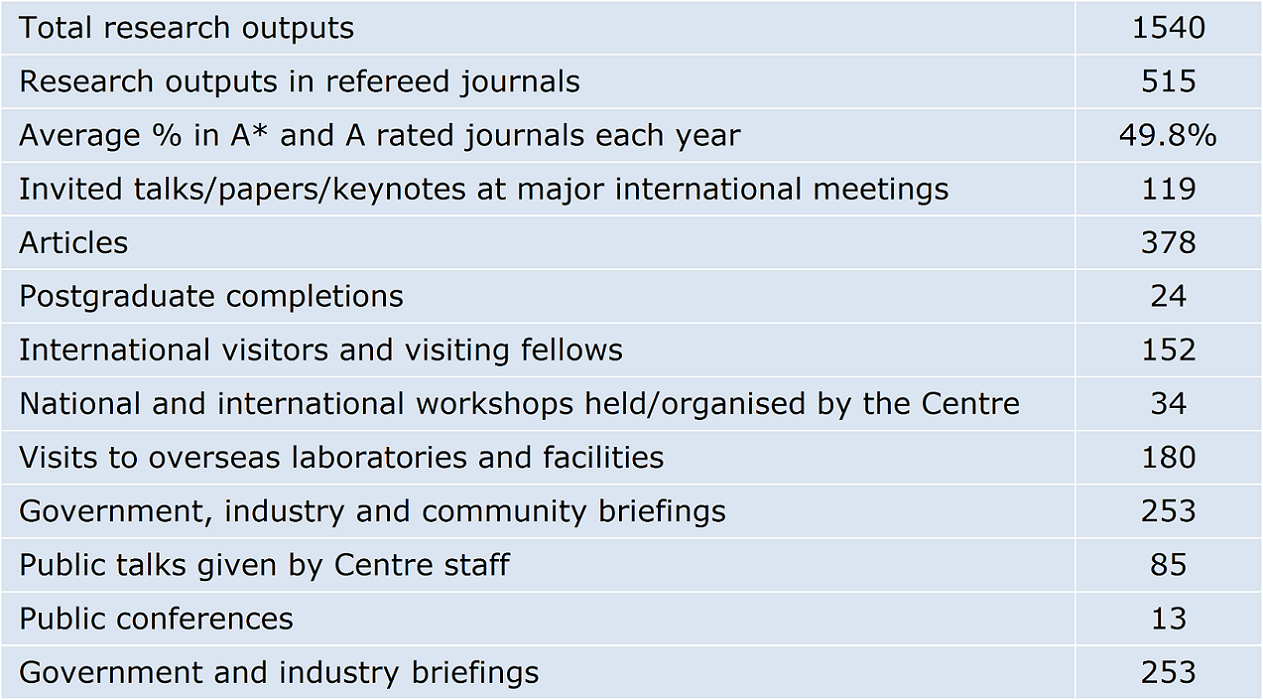
Sometimes it may be difficult to identify the output of a research body. Some of CEPAR’s statistics shed light on the breadth and quantity of output (for the period 2011 to 2015):
Why does this matter for industry and individuals?

People will ask questions such as “How does this all flow down to the real world?” or “How does society benefit from academic research?” The table above demonstrates how research centres are increasingly focusing on more than publication in academic journals (though that will always be important). Modern day research in practice recognises engagement and collaboration are drivers of success.

If research groups engage well, then their research is better positioned and reaches a larger audience. By engaging and collaborating, academic researchers are better informed of research needs and barriers to implementation.

The first draft of this article received strong editorial feedback. It was going to finish with the following paragraph.

Perhaps it is important for industry to ask themselves “Are we sufficiently engaging with the research community?” If you haven’t heard of CEPAR or aren’t aware of the work CEPAR is doing, then it is worth learning more about, especially if you are affected by population ageing (in my case, for instance, superannuation).

However, the alternative paragraph is as thought-provoking.

How many people in industry have heard of CEPAR? Are the metrics tabled above ones which best measure effective engagement? How highly does CEPAR value the benefits of engagement with industry and is it sufficiently core to their culture and philosophy? And how can we more clearly see how the benefits work for the ageing public who pay for their research?

Personally, I feel there will always be the potential for greater levels of collaboration between industry and researchers such as CEPAR. All parties are stepping in the right direction, and there is more to come. In CEPAR’s case, at least seven years and hopefully a lot more.


David Bell is Chief Investment Officer at Mine Wealth + Wellbeing. He is working towards a PhD at University of New South Wales.


  •   9 March 2017
  • 2
  •      
  •   
2 Comments
Fundie
March 09, 2017

Interesting story but here's an idea – cut the spending on all that medical research that is adding to life spans, then we don’t need to spend so much money on research into fixing all the problems created by longer lifespans!

David Williams
March 09, 2017

CEPAR does an excellent job of identifying longevity issues, researching them and achieving well-founded conclusions. Its 'faculty' is world class. But like so many countries, our programs for educating people to deal with their own longevity are significantly underfunded and limited.

We have funded improving financial literacy, but as a community we are woefully longevity ignorant. Yet our financial requirements are dependent on our expected time frame - the independent variable on which professional financial planning depends. Understanding our time frame,its potential consequences and the trade-offs we must make are the best foundation for appropriate financial decisions.

We need to do much more to plug CEPAR's excellent work into learning and behavioural changes. We must develop a more aware, independent and functional older community as well as better informing their successors.

The root of our longevity challenge is that our social evolution is simply not keeping pace with the growth in our scientific knowledge - so our solutions are evolving more slowly than our longevity increases. We need to bridge the gap with better education.


Leave a Comment:

RELATED ARTICLES

How long will you live?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.