Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 231

The index investing story could be even better

The 2017 financial year was a good one to be a passive (index-tracking) investor in large cap Australian equities. The S&P/ASX200 returned 14.1%. Add to this the other attractions of passive investing – fees are typically lower than active management, taxes and transaction costs are lower, and investors know what they are getting. These attractions no doubt explain why around US$500 billion globally is leaving active equity strategies each year.

Large superannuation funds in Australia caught up in this global trend have an additional factor to consider. Australia, almost uniquely, taxes the investment returns of super funds. This makes passive investing an after-tax optimisation problem for Australian funds. While the headline 14.1% return is eye-catching, there is little insight as to what this looks like after tax or what tax management could have added to this good news story. ‘Dumbing down’ the after-tax optimisation problem to a simple ‘keep turnover low’ mantra does a disservice to the smart, sophisticated investment thinking most funds apply to other parts of their investment portfolio.

The forgotten effect of taxes

Most talk is on the extra tax a fund pays when moving from a passive to a factor-based or full active management style. But there are meaningful increases in tax just from moving from a theoretical ‘buy and hold’ strategy to a real-life index-tracking strategy which typically turns over 5-10% each year due to index reconstitutions, corporate actions and day to day fund cash flows.

It is a step in the right direction for a super fund to ask how much more tax could be payable by moving from a passive to factor-based or active investment approach. But given the massive flows in the other direction (towards passive), funds must also explore the whether there are ways to pay less tax in the way the passive investment strategy is implemented. Funds and asset consultants seem to stop short of asking this second question. It is not in the interests of the traditional passive managers (the beneficiaries of the flight to passive management) to raise it.

One way to differentiate a genuine tax-managed passive strategy from a simple ‘keep turnover low’ approach is in how loss stocks are treated in the portfolio. Consider the stock-level returns comprising the S&P/ASX200 over the 2017 financial year, as set out below:
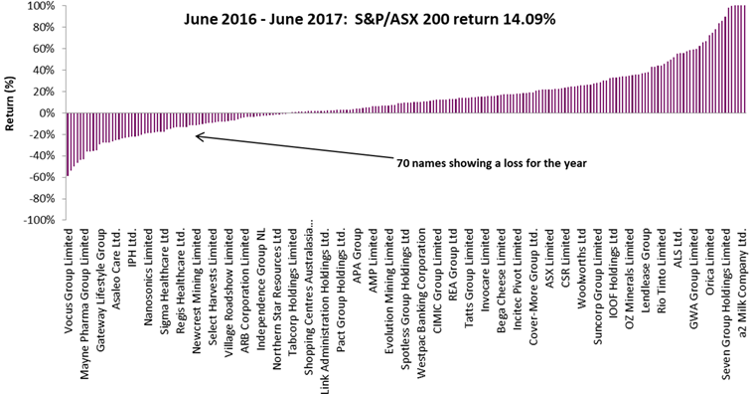
Source: S&P, Parametric. Provided for illustration purposes only. It is not possible to invest directly in an index.

Utilising the losses to offset gains

A portfolio tracking this index could claim to be ‘tax efficient’ by naturally avoiding the realisation of gains on the 142 stocks which appreciated in value during the year. The accrued gains count for performance measurement purposes, but not for tax purposes – a good combination. But note the 70 loss stocks in the portfolio that depreciated in value over 2017. A traditional passive strategy has done nothing with these loss stocks, even though realised losses are valuable as assets which shelter from tax capital gains realised anywhere else in the fund’s portfolio (not just Australian equities).

In contrast, a genuine tax-managed passive strategy could naturally accelerate the realisation of these losses (within legal limits) to unlock their tax value and improve the after-tax returns of the portfolio further. In fact, the real opportunity set for an after-tax focused passive manager is not the 70 stocks in the S&P/ASX200 that returned a net loss but the 178 stocks that, through natural fluctuations in the market, were showing a loss at some point in time in 2017.

Using super fund capital gains tax rates, our published research indicates that this kind of intelligent after-tax thinking can add (pre-fees) around 25 basis points (0.25%) to an S&P/ASX200 portfolio and 30 basis points (0.30%) to an international equity portfolio each year. Franking credit strategies could add more. These extra returns are relative to traditional passive approaches which claim to be ‘tax efficient’.

An interesting sideline is that volatility, the enemy of most investors, actually becomes a useful tool in this exercise. This illustrates how the S&P/ASX200’s good news story for 2017 could have been even better if super funds were genuinely approaching passive investing as an after-tax challenge. Of course, if the index’s returns move closer to long-term averages (less than half of the 2017 return) in coming years, the extra return increments will be even handier.

Finally, genuine after-tax investing will report portfolio and benchmark performance both pre- and post-tax, which is the only legitimate way to show whether a ‘tax efficient’ strategy is living up to its claim.


Raewyn Williams is Managing Director of Research at Parametric Australia, a US-based investment advisor. This information is intended for wholesale use only. Parametric is not a licensed tax agent or advisor in Australia and this does not represent tax advice. Additional information is available at parametricportfolio.com.au.


  •   14 December 2017
  • 3
  •      
  •   
3 Comments
James Williamson
December 15, 2017

Do you know of any after tax return information on managed funds? I know vanguard put this on their website do you know of any others or an independent source.?

Nick
December 16, 2017

Raewyn's idea requires an element of active management which will be reflected in the management fees.

Peter Vann
December 19, 2017

IMHO, funds that ignore the impact on after tax results from decisions they make are not adequately fulling their duties; the same applies regarding external manager mandates.

Whilst tax considerations in investment decisions require some grey cells, it is not hard and surprisingly still not done as a matter of course across the industry, even after much focus on this issues back in the late 1990s and early 2000, and thereafter.

One example: I know of an analysis done for a large super fund some time ago that simply looked at the impact of the back office parcel picking for CGT purposes following simple pragmatic rules (no impact on investment decisions and simply an accounting action); this analysis was done for the full transaction histories on a number of stocks and showed that there was between a few bps to 40 bps p.a. benefit in after tax returns, average benefit around 25bps p.a.. Was this (almost) free lunch ever implemented? Not to my knowledge. Who would throw away that return boost??

If index fund managers did this, then they would even surpass more active funds on an after tax basis. Well done Raewyn.


Leave a Comment:

RELATED ARTICLES

Div 296's million-dollar reset worth $25,000

Are markets broken?

The when and why of four million Australian retirees

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.