Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 79

Investor behaviour and lump sum bias

Australian superannuation funds face a number of barriers in providing an adequate and sustainable level of retirement income for their members. This article looks at one such barrier, an investor behaviour known as ‘lump sum’ bias.

What is lump sum bias?

Public superannuation funds accumulate capital for people to retire on. But most people find it difficult to calculate how much retirement income their capital can reliably produce from year to year. They tend to over-estimate the amount of annual income it can reliably produce.

Anecdotes about such behaviour are common place. Retirement expert, Don Ezra, suggests that if you ask an intelligent, but non-mathematical, person how much yearly income a lump sum of $100,000 could reliably generate for the rest of their lives, their usual response would be in the range of $10,000 to $20,000. Most experts would put the correct figure at around $5,000 per annum, perhaps even less.

Lump sum bias is where people place a higher value on a lump sum than the actuarially fair and sustainable income stream it could produce.

In rational economic theory, a person should choose the payment outcome that has the highest discounted value. Behaviourally, however, people have a bias towards a lump sum payment. There are a number of factors that explain why people exhibit such bias, including:

  • wealth illusion – one simply looks bigger than the other
  • affect heuristic – people make a rapid, intuitive judgment because it feels like a good amount
  • simple temporal discounting – people generally prefer dollars today over dollars tomorrow
  • preference for certainty – people perceive the future as uncertain, and by taking a lump sum payment today, they eliminate a degree of uncertainty, even if they potentially sacrifice some ultimately higher value
  • opportunity cost – people believe that having a single large sum might enable them to create or exploit an otherwise unavailable opportunity
  • utility of money – people expect the utility of money to decrease as they age and that they will have fewer and less attractive opportunities to enjoy the money.

Evidence of lump sum bias

United States academic Dan Goldstein conducted an experiment where participants were asked to rate their satisfaction with either a $100,000 lump sum or monthly payments of $300, $500 or $900 for life. For a 65-year-old, such a lump sum is roughly equivalent to $500 a month for life.

Respondents had clear preference for the lump sum, even compared to the much more actuarially valuable $900 monthly payments. In fact, Goldstein calculated that the ‘indifference point’ (ie where people would take either) between monthly payments and a $100,000 lump sum was $1,065 a month, nearly twice what it should have been.

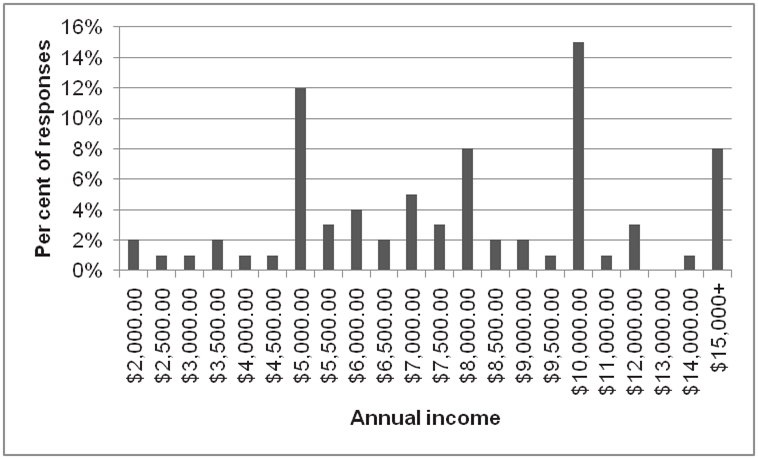
Australian financial research firm Investment Trends conducted a similar survey in Australia. They asked people 40 years of age and over how much minimum guaranteed annual income they would need for the rest of their life, in return for a $100,000 investment. Figure 1 outlines the results. The average response was $8,200 per annum, with $10,000 per annum being the most selected option. This is well above the actuarially fair amount of approximately $5,000 per annum.

Figure 1 Lifetime annual income required for a $100k lump sum
Summary

When it comes to developing an income plan for retirement, lump sum bias can negatively impact the planning process. People who are unable to determine an equivalent income stream from a lump sum might not be saving enough. In particular, people with smaller amounts of retirement savings feel that a lump sum is more adequate for retirement than an equivalent income stream.

Most super fund members get their periodic statement with their latest account balance on it. If they also received a projection of their annual income in retirement in today’s dollars (while highlighting the likelihood of a range of outcomes deviating from the average) it would help prevent them from falling short of retirement adequacy by over-estimating the value of their lump sums.


Aaron Minney is Head of Retirement Income Research and Phil Sainsbury is a Research Analyst at Challenger Limited.


  •   12 September 2014
  • 3
  •      
  •   
3 Comments
Warren Bird
September 12, 2014

To me, the answer to the poll question that is related to this article is: "it depends on the credit rating of the institution promising me the income."

What I mean is this. If faced with a choice between a $100,000 lump sum or $4,000 a year from the Government, I'd take the income stream. But if the promise of $4,000 a year was from a BBB rated financial institution with no clear investment process, I'd take the lump sum and invest it in a portfolio of my own choosing.

If the BBB rated institution offered my $7,000 a year I might think about it. Even then, if this was all I had saved up, I'd be worried about the concentration risk and would prefer a more diversified source of income.

So I'm curious whether any of the research took this into account? What was the actual nature of the income promise that people were asked to compare with the lump sum? Clearly if people like me responded, it would bias up the break-even income level!

Stuart Barton
September 17, 2014

Ceteris paribus would be the answer, wouldn't it? The research is expressly solving for one variable, so doesn't take into account the issuer's creditworthiness, nor the actual or self-perceived skill level of the respondent. A separate experiment would be required to test for sensitivity around the perceived creditworthiness of the income stream issuer, Even so I am not sure that the theoretically risk-free Government is an appropriate foil, as not even Australia's A-rated life companies/annuity providers will have higher perceived creditworthiness.

David M
September 12, 2014

Well written article, have known and seen this in action but wasn’t aware it had a label. I think some form of additional reporting about the possible income stream is a good idea; this might encourage people to help grow their superannuation.


Leave a Comment:

RELATED ARTICLES

Putting off that retirement speech

There's a reason why your super is locked up until your 60s

Under-retiring: The greatest retirement risk in a generation

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.