Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 566

The iron law of building wealth

I like the chart below. It shows how when we’re born, we have infinite paths that we can take. Our experiences and decisions take us via a certain route to where we are today. And from now, there are similarly a lot of different directions that we can travel. The question is: what’s the best path for us?
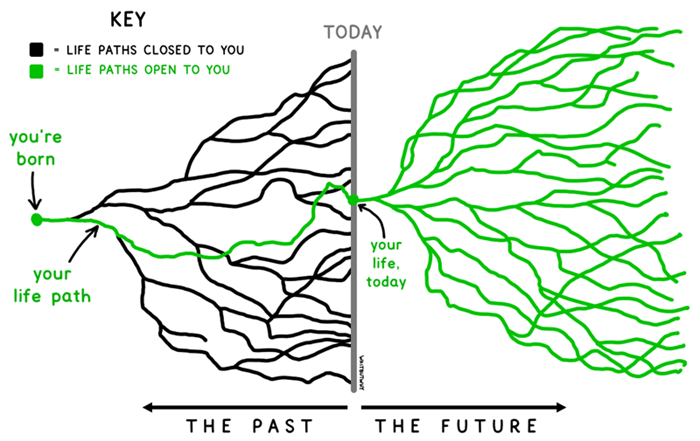

Source: Tim Urban

To make it easier, it can be worthwhile to think about the above diagram in terms of one key aspect of our lives: financial, social, health, perhaps spiritual. And, to consider the best ways to make the most of this part of our lives. To increase the odds of success, if you like.

The future is inherently uncertain. There’s no guarantee that we’ll end up where we want even if we make the right decisions along the way. However, there are ways to lift the probabilities of achieving our goals.

Inverting the problem

How do we this? One strategy can be to turn the question around 180 degrees and look at how not to do it.

Take our health for example. Most of us want to be healthy, to have a good quality of life as well to possibly extend our lifespan. Yet, we often pursue things that will never allow us to reach our goals.

Have you ever dieted before? I know some people who’ve tried every diet there is. Mediterranean, Atkins, high protein, Paleo, Keto, low-fat, intermittent fasting, and the list goes on.

The problem with dieting is it isn’t sustainable. It’s not something that we’ll be able to maintain for the rest of our lives.

The same goes for fitness. Have you ever signed up for a gym membership, and given up after a few weeks? Or go to the gym for a more extended period, then give up for a while, before getting back into it, and then letting the membership lapse again? I know I have.

For many of us, going to the gym isn’t sustainable either. It’s not something we’ll continue over the very long-term, for any variety of reasons.

Often the solution is to look at things that are more sustainable. With diet, it’s perhaps not trying a radical solution but a more incremental one. Instead of going for the Atkins diet, it’s committing to eating a salad for lunch each day. Doing that consistently could do wonders for your health.

Or instead of going to the gym, committing to a sport that you like for 2-3 days each week. Or walking for 30 minutes each day. Anything that you could see yourself doing not only today, but in 10-, 20- or 50-years’ time.

How this applies to investing

How does this relate to investing? The biggest mistake that I see investors make is constantly switching strategies. One minute, they’ll chase the speculative pharmaceutical stock that they’re sure will soon get FDA approval for a certain drug, or the mining company that’s about to make the next big find, or the next bit of market momentum. And the next minute, they’ll chase the investment manager that’s recently shot the lights out, and we all know what usually happens then.

This flip-flopping leads to predictable results. Numerous studies show that the average retail investor underperforms indices by a wide margin.
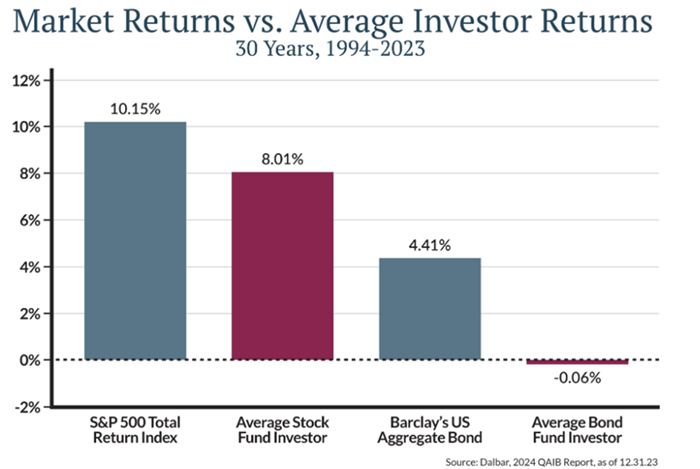
The chart above reveals the average stock investor has trailed the index in the US by more than 2% each year over the past decade. This may be generous as prior studies have found worse outcomes.
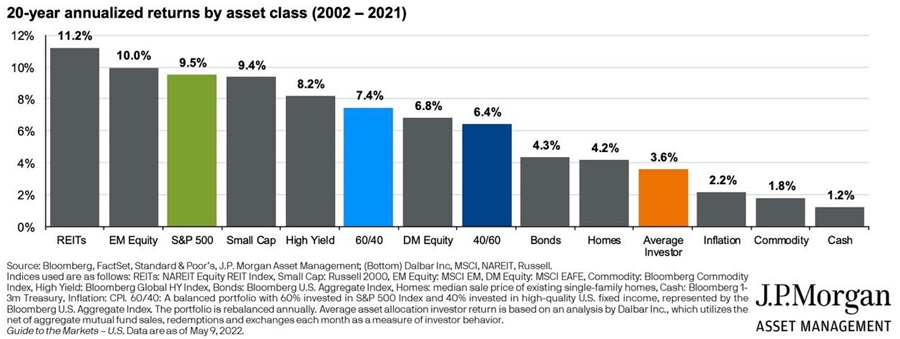
The next chart shows part of the reason why this happens.
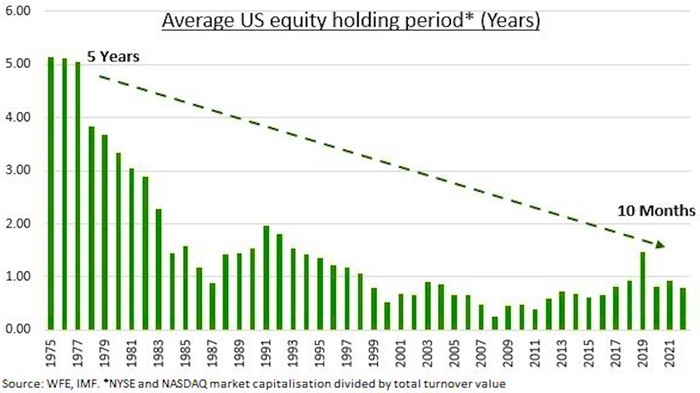
Trading and flip-flopping between strategies are what I call lottery investing. There’s a small chance that you can hit it big, but the odds are against you.

How to tilt the odds in your favour

What can improve the probabilities of building wealth? As with our health, the answer usually revolves around what is sustainable, or timeless. What is an investment strategy that you feel comfortable pursuing in the long-term? Framing the issue this way has several advantages:

  • It gets you thinking long-term rather than trying to find the next ‘lottery stock’.
  • It makes you consider what strategy may suit you best. It’s not about what suits others, but you. Your goals, preferences, and personality.
  • It can help identify your investing edge versus others. Warren Buffett once said: “If you've been playing poker for half an hour and you still don't know who the patsy is, you're the patsy.” This can help you avoid being the patsy!
  • It can help you ride through short-term market noise and market gyrations, both of which undo a lot of investors.

Notice how I haven’t mentioned any specific investing style or strategy worth pursuing, because really that’s up to the individual.

Possible objections

There are a few potential objections to the strategy of timeless investing:

  1. Doesn’t it mean sticking with a strategy that’s static and not moving with the times?
  2. Didn’t Buffett change his style and go on to become successful?
  3. What if my strategy isn’t working? What do I then?

To the first question, it certainly does mean sticking with strategy – that’s the whole idea.

While it’s true that Buffett did change his investment style, there was a specific reason for that. As you may know, Buffett was a deep value investor when he ran his own fund, before buying into Berkshire Hathaway. Meeting Charlie Munger helped Buffett move towards more of a growth style of investing, which led to famous stock purchases such as Washington Post, Coca-Cola, and more recently, Apple.

What’s little acknowledged is that Buffett was forced to evolve his strategy as he grew Berkshire. He foresaw that what worked previously with a small amount of money wasn’t going to work with a large pot of cash.

As to the last question, that’s a tricky one though it makes it even more critical to ensure your original choice of a strategy is the correct one.


James Gruber is Editor at Firstlinks and Morningstar.


  •   26 June 2024
  • 5
  •      
  •   
5 Comments
Stephen E
June 27, 2024

As Charlie Munger said, invert, always invert.

BeenThereB4
June 27, 2024

About 20 years ago, about Melbourne Cup time, I concocted my Investment Trifecta:

Buy/Hold shares in companies that
1. Receive Revenue from sale of goods or services
2. Earn Profits, and
3. Pay Dividends

The above eliminates 75%-to-80% of companies listed on the ASX.

Above avoids wannabees like early stage pharma and mining hopefuls.

One can the dig into P/E ratios, gearing, bona fides of directors etc

Just saying

G-Pete
June 30, 2024

And, BeenThereB4, your result is…..?

David O
June 30, 2024

“invert”, what does it mean when investing?

Chris
July 03, 2024

Always flip the situation on its head and first determine the outcomes you wish to avoid. Eliminating stupid mistakes is easier than trying to execute brilliance.

Munger said “All I want to know is where I’m going to die, so I’ll never go there.”; inspired by the German mathematician Carl Gustav Jacob Jacobi. Jacobi often solved difficult problems by following a simple strategy: “man muss immer umkehren” (or loosely translated, “invert, always invert.”)

He knew that it is in the nature of things that many hard problems are best solved when they are addressed backward. It is not enough to think about difficult problems one way. You need to think about them forwards and backward. Inversion often forces you to uncover hidden beliefs about the problem you are trying to solve; “many problems can’t be solved forward.”


Leave a Comment:

RELATED ARTICLES

Can Berkshire thrive without Buffett?

The new capital gains tax trap for your portfolio

The investing rule that explains the next market crash

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Latest Updates

Retirement

The retirement account that Australia should have

Our retirement system asks one account to do two very different jobs. A dedicated "rainy day" account separating income from emergency savings could deliver better outcomes and greater peace of mind for retirees.

Investing

What the US midterm results mean for investors

Democrats have regained control of Congress, changing the equation in Washington. Whether that proves positive for investors will depend less on the result itself and more on what happens next for growth and markets.

Taxation

Should the capital gains tax reward risk?

A reader query on the recent CGT reforms has revealed a bigger issue. One overlooked feature of the old system may have done more than compensate for inflation. As we move to indexation, are we forgetting to reward risk?

Investment strategies

Bonds: The income and diversification trade-off

Rising yields have made bonds attractive again, but that does not mean they will behave as expected. As inflation, fiscal pressures and geopolitical risks reshape markets, the role of bonds may be more complicated than it appears.

Investment strategies

Why high-dividend investing deserves another look

Income investors have endured several lean years, but signs of a recovery are emerging. As opportunities improve, investors face an important choice between chasing headline yields and building a reliable source of income.

Investment strategies

Why 'overvalued' has been such an expensive word

Investors love simple rules, especially when markets appear stretched. Yet some of the strongest returns have arrived when the outlook seemed least attractive. This leaves an important question that history struggles to answer.

Investment strategies

AI – A good kind of bubble or just a bubble?

Investor obsession with AI is attracting unprecedented amounts of capital and confidence. But beneath the excitement lies uncertainties about returns, funding and risks that enthusiasts may not be paying enough attention to.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.