Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 448

Lessons for family businesses from the House of Gucci movie

The crime drama movie released last year, House of Gucci, is Ridley Scott's controversial interpretation based on the true story of Patrizia Reggiani and her conviction for murdering her ex-husband Maurizio Gucci.

The prestige product manufacturer, Gucci, has seen the potential for negative publicity for its brand arising from the film and has asserted that it is a work of fiction. I have no way of knowing if the film is factually incorrect but, from 25 years of advising family business owners, I would say there is no doubt that there were disputes in the family.

In 1993, after one grandson, Maurizio, sold his inherited 50% interest in Gucci to the same investment firm he had brought in to buy up his relatives’ shares, there was no longer anyone from the Gucci family involved in running the firm. His lavish spending and lackluster management left the company in a parlous position when he finally relinquished control.

Maurizio would go from reluctantly joining his family firm to ruthlessly removing his relatives to execute his vision to save the company.

He was murdered on the steps of his office building in Milan in 1995. The film explains that his wife, Patrizia Reggiani, was sentenced to 29 years in prison for orchestrating the murder, and she was released in 2014 after serving 16 years. She could have been released even earlier but she turned down a work-release programme, reportedly saying, “I never worked a day in my life, and I don’t intend to start now.”
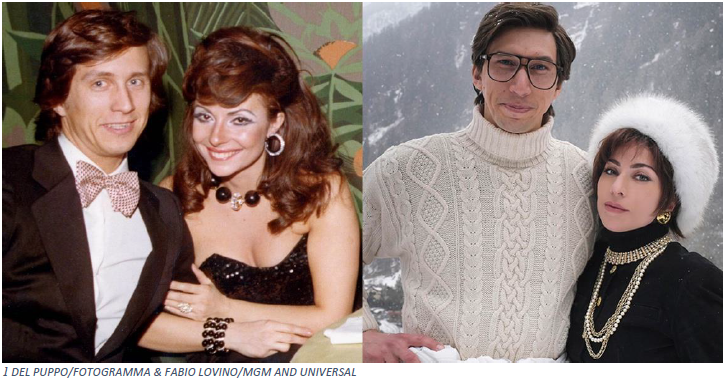
The movie ends with an inheritance dispute as often happens. In our experience, behind most such disputes there is family drama that could have been handled much better.

After her release, Patrizia was asked by paparazzi in the street why she hired a gunman to kill Maurizio rather than do it herself, she said, “My eyesight is not so good, I didn’t want to miss.” According to the new afterword in the movie tie-in edition of the book on which the film is based, the wife succeeded, against her two daughters who presumably wanted the inheritance, in her claim for a substantial annuity from the Gucci estate. In 2014, she said, “I still feel like a Gucci – in fact, the most Gucci of them all.”

The other family members did not fare much better. Another grandson, Paolo, filed for bankruptcy in 1993 while his father, Aldo, served time in prison for tax evasion.

Roberto, one of Aldo’s sons not depicted in the movie, went on to run a small leather goods business in Florence after selling his shares of the family company, and once said, “The Guccis were a great family. I ask forgiveness for all their mistakes. Who doesn’t make mistakes?”

I first came across this story in a book considering family succession by Alan Crosbie called 'Don’t Leave It To The Children'. Crosbie writes with authority being the fifth generation of an Irish newspaper dynasty. He writes:

“Guccio Gucci suffered from a bad sense of parental fairness. He had two sons, and in order to be fair to both of them, he divided his company equally between them: each son received 50% of the shares in the family firm. Now, that figure has a certain magic to it. The expression ‘They divided the business 50-50’ has a wonderful ring to it. Unless you’re one of those accountants or lawyers who has had to mop up the results of such an even split between family members.”

At Legacy Law, we are one of the mopper-uppers. The way to avoid family disputes is to have good communication, adequate preparation and helpful dispute resolution  - by which we mean avoiding the civil and criminal courts. 

Well-respected commentator on family business, Dennis Jaffe, recently opined:

“Major decisions were hard to make since the brothers were equal owners and it was never clear who was in charge. As in many families since biblical times, interpersonal dramas and sibling rivalry were dominant, and they were on course to disrupt a thriving business”.

The film ends with a note that acknowledges the company’s current leadership and that it has an estimated value of US$60 billion. It just has no family owners.

In the book, as Maurizio rises in the company, his own father Rodolfo tells his wife, “Once he gets money and power, he will change.” As humans, we all change but it is positive change that is required if families are to avoid falling victim to disputes and miss the opportunity to Be A Better AncestorTM.

If you have a business, ask yourself if you want to build one of the great business families. They are plenty of good and bad examples but the good ones do a lot more than rely on good luck and goodwill.

Have you simply left the shares equally to the children? Equality, without more governance, communication and consensus can leave a family business exposed to public ridicule, or worse.


Donal Griffin is the Principal of Legacy Law, a Sydney-based legal firm specialising in protecting family assets, and author of 'An Irish book of living and dying' (the first book in the 'Be A Better Ancestor' series). Legacy Law is not licensed to give financial advice and this is general information.


  •   2 March 2022
  • 2
  •      
  •   
2 Comments
Matt Meehan
March 06, 2022

Thanks Donal

Donal Griffin
March 11, 2022

Thanks Matt


Leave a Comment:

RELATED ARTICLES

Could your children pass the inheritance ‘stress test’?

Preserving wealth through generations is hard

The legal fallout when a carer becomes a partner

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.