Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 225

Will millennials change the investment landscape?

Millennials recently became the largest demographic cohort, and now 29% of the Australian population was born between 1980 and 2000. By 2030, they will represent the largest source of income and consumer spending, earning two out of every three dollars in Australia. While much has been written about how the shift in spending patterns will change the retail landscape (online over brick and mortar and experiences over materialism) relatively little research has focused on the changes to investing and asset management. Over the next two decades millennials will not only become the largest earners but are also set to inherit significant wealth, further increasing their importance to the investment industry.

Tech savvy and socially responsible

Much of the focus on the investments of millennials has to date revolved around the growth of passive/ETF investing (according to Commsec, millennials now account for 25% of ETF trades) and the use of ‘robo-advice’. Both have largely been driven by lower minimum investments and perceived low fees, making them attractive entry level propositions. While these trends are likely to continue, millennial investors are also likely to move into more traditional investment products as they build wealth over their lifetimes. Indeed, we are already beginning to see this, with Commsec finding that 50% of all new customers are under 35 years of age while millennial customers have increased by 51% over the last five years and now represent 28% of all active members.

With 87% of millennials believing that business success should be measured by more than just financial performance, one of the largest changes is likely to be the continued growth in responsible, sustainable or ‘impact’ investing. Growth in these strategies is accelerating in Australia, with rise in funds invested in ‘core responsible investments’ from $11.9 billion in 2006 to $64.9 billion in 2016 and reaching 4.5% of total assets, as shown below. Market share remained under 2% for the majority of the last decade, but have surged in the last few years.

Core responsible investment strategies as a percentage of assets under management
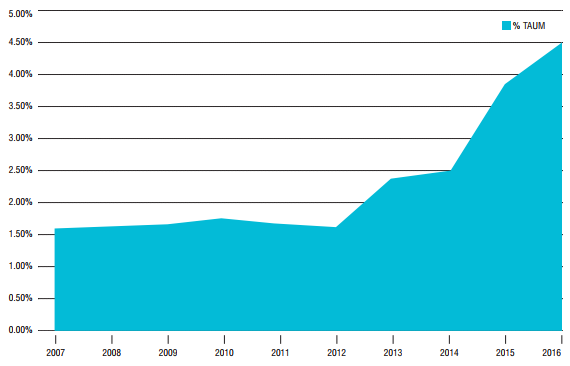

Source: RIAA, Responsible Investment Benchmark Report 2017 Australia.

With 85% of millennials interested in or currently using social impact investments, this trend is likely to accelerate further as they make up a larger proportion of the market. Additionally, 85% of millennials now consider investment decisions as a way to express their values. Financial investments will become more aligned with social, political and environmental factors.

At CFSGAM, we recently conducted a survey of our own staff (30% of whom are millennials) on the extent of their individual beliefs on responsible investment. The survey found that:

  • 80% of staff believe considering ESG issues leads to more complete analyses and better-informed investment decisions.
  • 85% supported the view that asset owners should, as part of their duties, consider both the direct and indirect ESG impacts of their investments.
  • 75% believed that the risks and opportunities associated with ESG factors are not being captured in market values.

This tells us that millennials are ahead of the curve when thinking about the impact and implications of responsible investment strategies. Further, they are more likely to favour responsible investment strategies and are also more likely to believe that investing responsibly does not negatively impact performance. Indeed, there is strong evidence that utilising ESG factors improves performance, with a recent BofAML Report finding that they could have helped investors avoid 90% of bankruptcies.

The funds management industry will need to adapt and responsible investing will become increasingly mainstream and less of a niche or nice to have addition to traditional offerings.


Harry Moore is Head of Business Development for Australia and New Zealand at Colonial First State Global Asset Management, a sponsor of Cuffelinks.


  •   2 November 2017
  • 5
  •      
  •   
5 Comments
Frank
November 02, 2017

Why are people born in 1980 called ‘millennials’?

Chris
November 02, 2017

“set to inherit significant wealth, further increasing their importance to the investment industry.”

Really ? Sorry, but as a Gen-X (born late-70s), I don’t expect or demand that my parents (one of them already being in a nursing home) will have anything to leave me (as one of four kids), in that the only thing they own are some cash, premium bonds and the house (which is nothing special).

They will likely need that money to look after themselves and any aged care requirements.

If they do leave me any money, it’s a good surprise, but I’d go and pay my mortgage off, then put my daughter through school / university, and if there was anything left after that (unlikely), then look at investing it.

Chris
November 02, 2017

And as a side note to the financial planning industry, the time to get involved and interested in millennial clients (and anyone else who isn’t a boomer like themselves, by the way) is BEFORE they grow their wealth, not when you think they might just suddenly inherit a whole lot (which is not a given and probably the exception, rather than the rule).

Most planners I’ve talked to look down their nose and over their bifocals at my modest, sub-million net worth and think it’s not worth bothering about.

Otherwise, you just come across as a gold digger, who suddenly becomes interested in marrying an old (wo)man with a dodgy ticker who has just won the lottery. It’s pretty obvious.

Gen Y
November 04, 2017

Oh Chris, I'm sure they're interested. They'll surely sell you some life insurance...

Rick
November 06, 2017

Wow, "bifocals", seriously? You've just painted the picture of a Bank Manager circa 1972, pretty outdated, cynical stuff. I don't know who you've been talking to, but the advisers I know are all energetic, progressive, and forward looking - they're very happy working with less established clients. In fact, helping younger clients move decisively towards achieving their goals is the part of my job I actually enjoy the most. And btw if an adviser charges a flat, dollar based fee, how much accumulated wealth a client has is irrelevant from an adviser remuneration perspective.

Gen Y: Life insurance and estate planning is a serious part of the wealth building/wealth protection equation, and for an adviser to not discuss it with a client would be negligent in the extreme. Let's not have a shot about 'selling' life insurance?


Leave a Comment:

RELATED ARTICLES

Four reasons ESG investing continues to grow

Looking deeper than the home page of roboadvice

Sustainable, responsible or ethical – what’s the difference?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.