Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 412

Peak to peak, which LIC managers performed during COVID?

The 14-month period from 31 January 2020 to 31 March 2021 was an excellent opportunity to assess whether a fund manager did a good job. That’s because January 2020 was the last monthly high before the pandemic hit markets and in March 2021, the ASX200 Accumulation Index returned to that level again. If you had invested in the ASX200 over this period, your return would have been just 0.7%. 

This period features both the downturn and the upswing. Although it’s a short period, it has some of the characteristics of a complete market cycle. These are the periods when active managers should outperform and earn their fees. 

So we checked this market high to market high to see how LIC managers performed. Did they add value?  

How we did it

For this exercise, we wanted to measure the investment performance of the LIC manager, so we ignored changes in share prices and looked only at the change in underlying NTA plus dividends and distributions. This excludes the impact of other market forces, such as changes in discounts to NTA.

Generally, discounts and premiums magnify market ups and downs. For example, if you had taken the plunge and bought a LIC in March or April 2020, it’s almost certain that the current premium or discount is better than when you bought. 

We looked at the change in pre-tax NTA plus dividends and distributions paid between January 2020 and March 2021. This penalises LIC managers slightly by including the impact of tax on realised gains. It also does not consider the effect of any corporate actions such as options and capital raisings. Even so, as you will see below, most managers still performed admirably after this handicap. For LITs, the trust structure means that, like ETFs and unlisted managed funds, there was no direct tax cost to handicap them.

We also highlight areas where active management has worked best, broken down by strategy. In many cases, particular LICs could have qualified in more than one strategy but we have placed LICs with the peer group we felt is the best fit.

Australian Large Cap Equities

For larger ASX stocks, where the ASX200 Accumulation Index delivered 0.7% for the period, we’ve used this as a benchmark. Results varied widely.
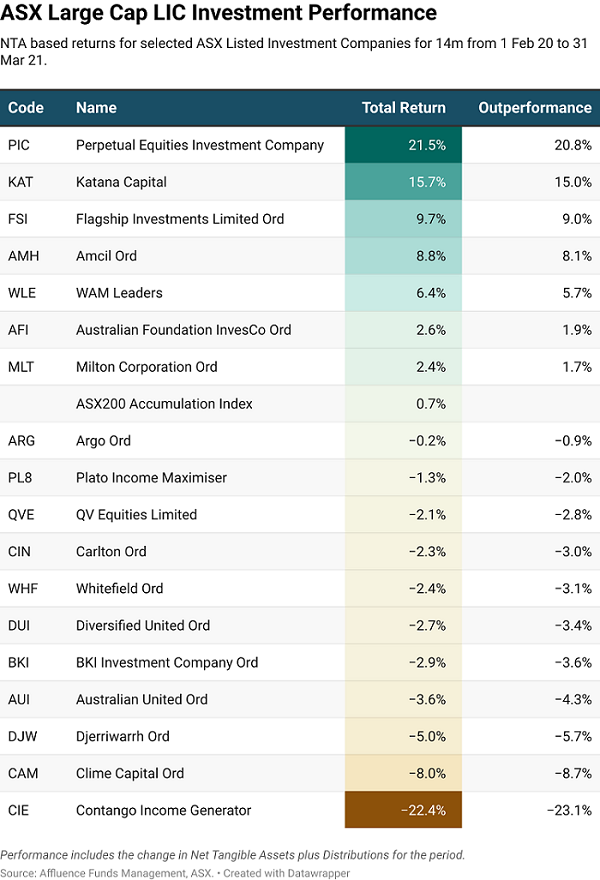
No doubt the star of the show was Perpetual. PIC delivered a total return of 21.5%. The result was helped by a small allocation to global equities and a resurgence in some of their favoured value stocks. Perpetual is genuinely differentiated from the index and it shone through. Other key outperformers were Katana Capital, helped by a decent allocation to resources, Flagship Investments, AMCIL and WAM Leaders.

What about the three largest LICs? AFIC and Milton added a small amount of value while Argo slightly underperformed.

At the wrong end of the table, we have AFIC stablemate Djerriwarrh, where some upside from the recovery may have been lost via their strategy to write call options. Clime Capital performed poorly while Contango Income Generator suffered as income stocks were hammered during COVID. This eventually resulted in the manager completely changing this LIC's strategy.

So, a mixed bag from large cap LICs with over 40% return difference between the best and worst performers.

Australian Small Cap Equities

Small caps are where the real opportunities exist for active managers, and most managers delivered in spades. The ASX Small Ords Accumulation Index did better than the ASX200 Accumulation Index over the period, with a 7.9% total return versus 0.7% for the ASX200.

Overall, 15 of the 21 small cap LICs, or around 70%, outperformed the Small Ords, many of them handsomely.
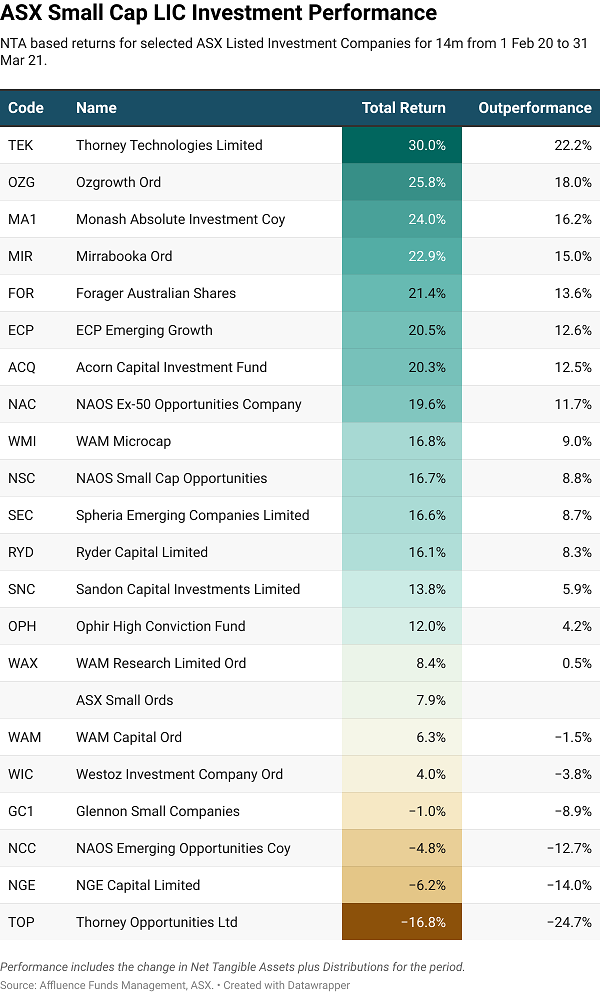
Unbelievably, both the top and bottom performers were managed by Thorney. This shows the stark difference that an investment style can make, even when run by the same management team. The technology focused TEK delivered a 30% return while old school value hunter TOP was the worst performer. TOP performance was made significantly worse by the management agreement with Thorney, which allows the performance fee hurdle to reset every year. This meant the $35 million loss suffered by shareholders in the 2020 financial year could be ignored. It resulted in a performance fee of $5.5 million in the second half of 2020 despite shareholders still being underwater.

Special mention must go to the team at Monash, who performed significantly better than most in the downturn and continued to add value during the recovery. In addition, they recently completed the transition of MA1 from an LIC to a listed managed fund, eliminating the considerable NTA discount and introducing a 6% per annum distribution target.

Global Equities

The MSCI All World Index returned 7.8% for the 14-month period, while US and many Asian indices fared even better. 
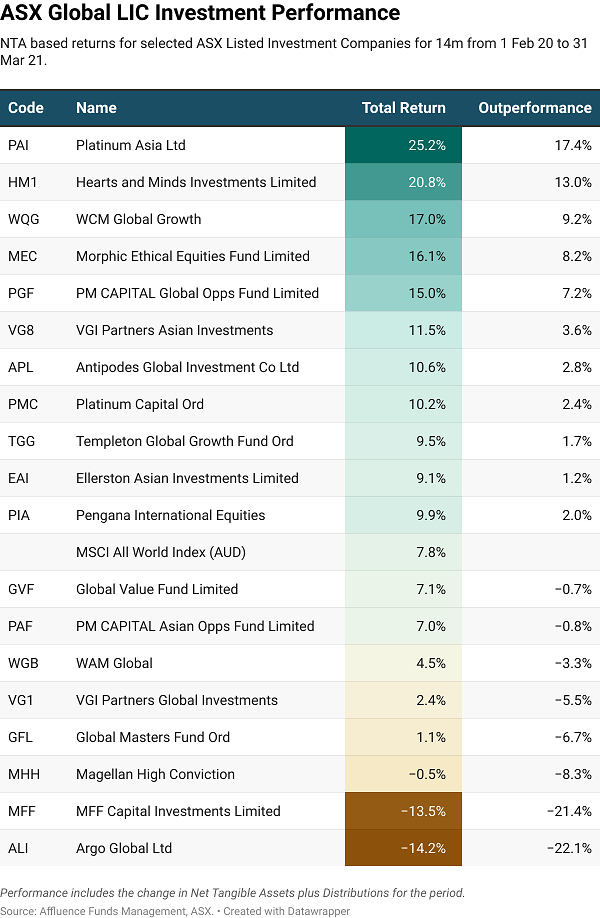
Platinum Asia and the flagship Platinum Capital did well as the value style slowly came good after a long period of underperformance. Other good performers included the successful Hearts and Minds Investments, WCM's US-focused global growth strategy, Morphic Ethical Equities and PM Capital, another value manager.

Two poor performers stand out. MFF Capital investments struggled after remaining overweight cash and missing a significant portion of the recovery. Argo Global is focused on listed infrastructure which has remained one of the areas most impacted by COVID.

Alternative Strategies

The alternative strategies group covers LICs that seek absolute returns, using tools such as shorting or carrying significant extra cash.
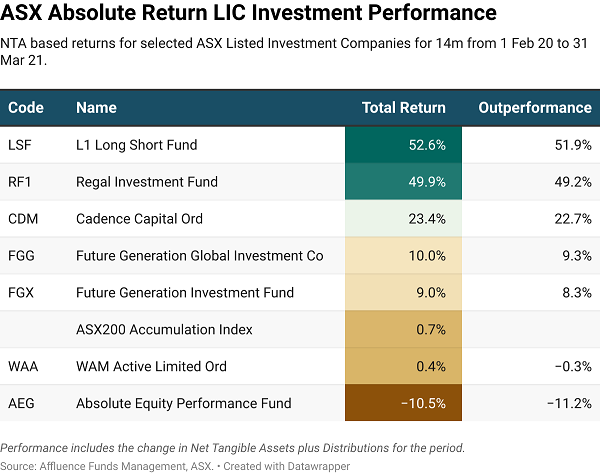
L1 Long Short Fund, despite being one of the most impacted initially on the downside, has recovered spectacularly well. They correctly recognised early in the recovery period that vaccines were likely to be highly effective and positioned the portfolio to benefit from value plays and the recovery trade. Regal Investment Fund, which incorporates a range of investment styles, also performed well. This was somewhat assisted by gearing embedded in some strategies. On the flipside, AEG, a geared market neutral fund, has struggled in an environment where value stocks have made a a comeback.

Alternative Assets

Our alternative assets group includes LICs investing in non-standard asset classes.
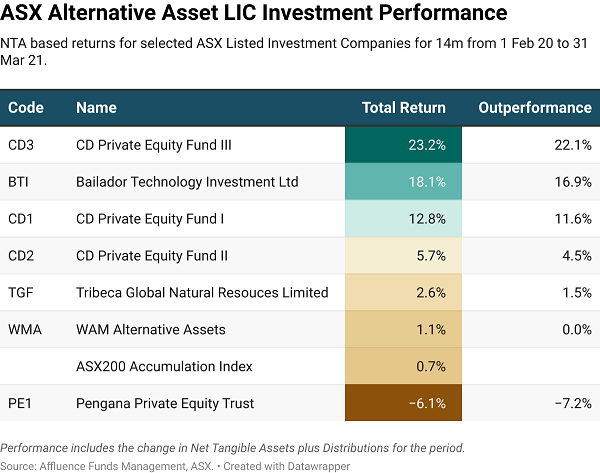
Outperformers included all three of the CD Private Equity Funds and Bailador's Technology focused private equity LIC.

The one disappointment was Pengana's Private Equity LIC. Despite weathering the downturn well, the recovery has been meagre for Pengana. It was not helped by the appreciation of the Australian dollar nor the additional capital raised by the manager.

Corporate and Real Estate Debt

Despite being a relative newcomer to the sector, debt focused LITs have primarily done their job. However, most of them traded at substantial discounts to their net asset value at some stage in 2020, requiring investors to hold their nerve to achieve the returns.
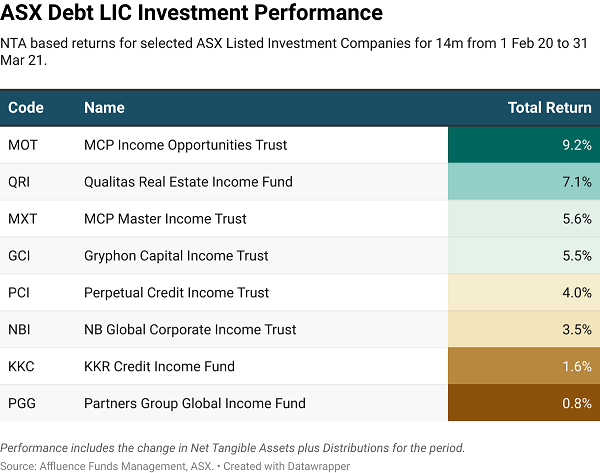
Two LITs from Metrics and one from Qualitas, both high-quality Australian managers, are at the top. All three delivered good results with no material loan losses. Of course, it helps that they hold private or unlisted debt, which is not marked to market like publicly-traded debt.

On the flipside, LITs from KKR and Partners Group generally have exposure to offshore publicly traded debt, which has not fared as well. We would also argue that this type of asset has a higher embedded risk. Indeed, these were also two of the most volatile LICs last year.

What have we learned?

From market peak to trough, and back to peak again, we've seen surprisingly diverse results from LIC managers, including many outstanding performers.

What lessons can we learn from this? Here are eight key takeaways, although these comments may apply to managed funds in general.

  1. The more a manager can deviate from a benchmark, the higher their chance to outperform. Of course, this also comes with a risk that they underperform. But if you choose talented managers with an excellent long-term track record, you've probably made a good start.
  2. Look carefully at what the manager is doing and question their competitive advantage. For example, it's harder to outperform in the biggest stocks. On the other hand, small cap managers and alternative strategies where the manager can have an information or skill advantage can deliver good results in choppy markets.
  3. Diversification is worthwhile. Picking one or two LICs might work, but it is better to have at least five and up to 10 for a diversified LIC portfolio.
  4. Investment style matters. Certain styles will outperform or underperform, potentially for long periods. Sometimes, that means two different LICs run by the same manager can have vastly different results.
  5. Bigger is not better. The performance of larger LICs was average overall. Most of the stellar results came from the medium and smaller sized LICs.
  6. Alternative strategies and alternative assets can be attractive diversifiers and perform relatively well when other investments struggle.
  7. Debt LITs did their job, eventually, with Australian assets and Australian managers delivering. Investors stomached volatility along the way.
  8. Finally, LICs can be an attractive addition to your portfolio. Increasing your allocation during times of market stress, when NTA discounts are higher and active managers can do their best work, can deliver outstanding investment results.


Greg Lander is a Portfolio Manager at Affluence Funds Management. This article is intended to provide general information only. It should not be construed as tax, legal or investment advice as it has been prepared without considering your objectives, financial situation or needs.


  •   16 June 2021
  • 15
  •      
  •   
15 Comments
Steve Green
June 16, 2021

Good summary Greg. Thanks for sharing as I find the time period very interesting to look at and this might have been a time consuming exercise to come up with the article so appreciate that.

Only comment I want to make is the shareholders of CIE & TOP might want to ask some questions to management there.

Peter J
June 19, 2021

Ditto to Steve Greens comment as I very much appreciate the time and the effort that goes into a presentation like this.

Peter Thornhill
June 16, 2021

Fourteen months huh? Can you give us the 20 year results please.

John Smith
June 17, 2021

Good point. The old LICs (ARG, AFI etc) are some of the best options available for us retail shareholders seeking some growth and steady income. I plan on holding them forever. Plenty of other ways to play short term if you want to do that.

I think it is a good article. Sensible advice.

Brad
June 17, 2021

I knew I would find you down here Peter! Very true but.

C
June 20, 2021

I've seen the 20 year figures for your beloved ARG, MLT, BKI etc and they have continually underperformed the index over the past 1, 3, 5, 7, 10, 15 and 20 year periods. AFIC has been better, but not better than the index. Just because something is old doesn't necessarily make it better. I'm happy with how PIC, WLE, WMI and LSF have done over the past 1 - 5 years and charging a performance fee for BEATING the index is not a bad thing.

Peter Thornhill
June 17, 2021

This is a comparison of before tax indices to after tax company outcomes, so understates the outcome of every company in the list.
The tax differential should be accounted for before making any comparison.

Anthony Gross
June 19, 2021

Good point Peter! I remember with affection your Income builder and industrial shares products of old!

Phil
June 19, 2021

Good information however I would also like to see the longer term performance eg 5 and 10 year and also I am not sure why not provide after tax performance, just as analysis of super fund performance needs to include fees. However this analysis does provide the basis of more investigation into the higher performers.

George Darivakis
June 19, 2021

It would be interesting and helpful to see a longer term perspective as Peter T commented .Also adding the" right" cost averaging investing with some responsive LIC will have delivered in those periods different outcomes. Thank you for the research. George Darivakis

Jeremy David
June 19, 2021

The trouble with using NTA is that is not what investors can actually buy and sell at. An investor in NBI for example is actually down -15% based on a discount to NTA that has never recovered over this period, wiping out multiple years worth of returns in a product meant to be an income product. At the low if the downturn it was actually much worse. This period has actually shown me exactly why LICs with the big disconnect between NTA and trading price is a massive problem for investors and moving to ETFs or funds is a better option.

Ramon Vasquez
June 19, 2021

Hello . IMVHO , l think we need a Fund of Funds Lic ; does one exist ? Best wishes , Ramon .

Greg Lander
June 20, 2021

Hi Ramon, we (Affluence Funds Management) have been running an unlisted fund dedicated to ASX listed LICs/LITs for the last 5 years. It was setup to capture the dual benefit of manager alpha and discount capture. It has performed very well, and we are actually closing the fund to new investors (existing investors can continue to invest) this month.

David James
June 21, 2021

Thanks for the analysis. If you believe the top managers tend to mean revert around their long term performance (not the benchmark), this provides some food for thought for changing weightings. E.g. MFFs significant underperformance due to their high cash holdings could provide an opportunity.

Re TOP and their terrible performance fee structure, can't say I didn't warn you :) https://www.firstlinks.com.au/5-famous-investors-with-cheap-listed-funds (see comments)

James
June 22, 2021

Anyone care to comment on the proposed WHSP “buyout” of MLT?

MLT has gone from about $5 to $6 overnight. Besides the likely 52cps fully franked dividends to be paid to existing MLT holders it looks like you end up with overpriced SOL shares and a whole different beast than you originally bought into. Not convinced it’s a good thing for long term holders that want dividends and some conservative growth.


Leave a Comment:

RELATED ARTICLES

It’s time for LICs to die

Why LICs may be close to bottoming

The fascinating battle between Nick Bolton and Magellan

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.