Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 344

The pitfalls of total return investing

In a former life, as a financial planner, I counselled my clients to consider the benefits of Total Return Investing (TRI). Forget about income, I said. Trust the academics, and the professionals (me). Today, however, I’m not so sure. TRI may in fact be doing investors a disservice. I say that because the global investment landscape has changed, and so have the risks.

The TRI theory holds that investors should build and learn to live off the total return of their portfolio, not just the income. In practice, this means investors sell appreciated assets when they need income above what is generated by the portfolio. And, where possible, live off dividend and interest income in the years when the portfolio declines.

The Total Return approach is elegant, it makes intuitive sense, and like so many investment strategies, it ‘backtests’ well – that is, it’s done well in the past. There is, however, a fly in the ointment: the prevailing global low-to-no interest rate regime. The backtests in the U.S. occurred during periods when both stock and bond yields were much higher.

5-Year U.S Treasury yield (1963-2019)
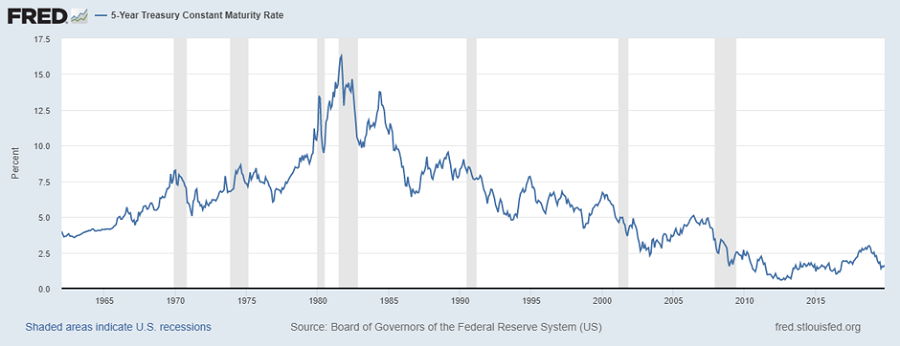
Thus, the TRI theory is based on what we now know to be the luxurious presumption of earning income from fixed interest. No one has had the experience of funding a 30+ year retirement through a period of zero or even negative interest rates.

The short income squeeze

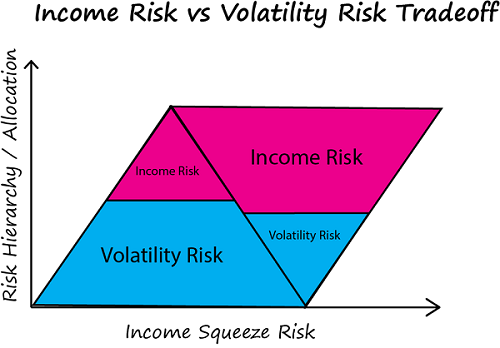
This lack of income is a critical weakness of TRI theory because the less income your portfolio generates, the more you are exposed to the pain of calling on your principal during market drawdowns - what I term a “short income squeeze risk”.

Here’s how it works: in the event of a market downturn, a lack of income creates, in essence, a short-squeeze situation. Retirees have no choice but to sell their investments and often at times when valuations dictate they should be buying or at least holding.

To date, this danger has been easy to ignore because returns have been strong and volatility relatively benign. However, there are reasons to believe it may not be in the future.

The new risk hierarchy - consistency of income trumps portfolio volatility

Intelligent investors think in terms of risk and then return, so it may be helpful to rephrase the issue in terms of a hierarchy of risk. In the past, the risk of an income squeeze could be easily subordinated to the risk of portfolio volatility because income was readily available. Today’s environment calls for a rethink.

I contend that below a certain portfolio income threshold, maintaining a steady income is a higher priority than minimising volatility. This threshold will depend on several factors which may include:

  • the degree of spending flexibility
  • capital risk relative to income 
  • diversification considerations, and
  • other sources of funds.

The degree of capital risk assumed relative to income obtained is also a critical consideration. Investors and their advisers should examine this new retirement risk landscape and re-calibrate their portfolios if necessary.
Sustainable income – mitigating income squeeze risk

One strategy to mitigate income squeeze risk is to increase the portfolio allocation to investments that offer sustainable dividends. Specifically, companies and credits with stable business models that rely on secular growth trends, such as population growth both in Australia and abroad.

The classic rejoinder to such advice is that it entails foolishly 'reaching for yield', i.e. unknowingly increasing risk by moving from lower- to higher-risk assets. And it is true, increasing your allocation to riskier assets will raise the volatility of your portfolio.

However, the paradoxical world created by low-to-no interest rates means that the income generated by equity-like dividends may come to be the only way to shelter retirees from an income squeeze. And as a result, spare them from having to erode their principal during a severe or even moderate downturn.

Thus, it can be argued that by taking more risk, you are making the conscious decision to reduce income risk (the income squeeze). The choice then is not a reach for yield but the inevitable by-product of all investment decisions, the exchange of one type of risk for another.

Recognising this, Legg Mason has created income solutions like the Legg Mason Martin Currie Equity Income and Legg Mason Brandywine Global Income Optimiser which are designed to invest in assets that hold out the prospect of providing sustainable income. As central banks continue to consign investors to a world without income, we believe these strategies will play an increasingly important role in clients’ portfolios.


Peter Cook is a Senior Investment Writer at Legg Mason Australia/NZ, a sponsor of Firstlinks. This article contains general information only and should not be considered a recommendation to purchase or sell any particular security. Please consider the appropriateness of this information, in light of your own objectives, financial situation or needs before making any decision.

For more articles and papers from Legg Mason, please click here.


  •   12 February 2020
  • 7
  •      
  •   
7 Comments
Andrew Bird
February 12, 2020

I agree that a TRI approach is almost essential these days given low yields. But I am not sure I agree that piling into the very crowded "high yield" trade is going to provide the best risk/return outcome.

A simpler way to deal with the "short income risk squeeze" that you mention is to keep a good cash buffer rather than compromising the growth potential of your portfolio. To use a simple example, If we assume a 5% drawdown rate on a portfolio, by keeping 15% in cash you have 3 years of income up your sleeve even without any income yield at all. Three years should be enough time to cover some pretty bad market downturns.

The 15% cash is not going to generate much but it does provide a lot of piece of mind. And the rest of the portfolio can be invested with total return in mind rather than a excessive focus on yield.

Andrew Bird
February 12, 2020

I agree that a TRI approach is almost essential these days given low yields. But I am not sure I agree that piling into the very crowded "high yield" trade is going to provide the best risk/return outcome.

A simpler way to deal with the "short income risk squeee" that you mention is to keep a good cash buffer rather than compromising the growth potential of your portfolio. To use a simple example, If we assume a 5% drawdown rate on a portfolio, by keeping 15% in cash you have 3 years of income up your sleeve even without any income yield at all. Three years should be enough time to cover some pretty bad market downturns.

The 15% cash is not going to generate much but it does provide a lot of piece of mind. And the rest of the portfolio can be invested with total return in mind rather than a excessive focus on yield.

Michael
February 12, 2020

Income from fixed interest and cash is VERY different to 'income' from equities. Dividends reduce your investment capital when they are paid (i.e. the share price reduces by the value of the dividend on the opening of the market on the ex-div date). This means that dividends and selling the equivalent value of shares are equal except for the tax implications (capital gains discount, franking credits).

Your challenge to TRI theory relies on the idea that dividends do not reduce your capital whereas selling shares does. This is incorrect. It will still be best practice for investors to choose investments for their total return potential rather than relying on only those that pay dividends at a certain level. To fund their income needs they then should sell assets and do so at all stages of the investment cycle.

Kim Wilkinson
February 12, 2020

Adopting a "Bucket" strategy (https://www.superguide.com.au/accessing-superannuation/bucket-strategy-solution-retirement-income-plan) would seem to minimise the "low income risk squeeze".
In Australia, if the investment income drops, people have the age pension to take up (or increase).

J.D.
February 14, 2020

The concept of total return investing is not to "live off dividend and interest income in the years when the portfolio declines".

If you had say 60% stocks and 40% bonds, then when the stock market declines, you do not live off dividends.


First you take from bonds what you need to live off. Secondly you reinvest the dividends buying socks when they are cheap. Thirdly you further rebalance from bonds into stocks also purchasing stocks cheap.

There's a common misconception amongst lay people that dividends are somehow safer than selling down shares and therefore dividends can provide reliable income. This is a fallacy. A dividend is literally a withdrawal. It's not similar to a withdrawal, it's an actual withdrawal.

Here's how it works at a company level - after a company pays out wages, debts, and other obligations, it pays out a portion of the remaining profit as dividends.

If a company worth $99M is gifted $1M, their new value is $100M.
In the same way, when a company pays out $1M in dividends, their new value is worth $1M less.
When you don't reinvest your dividends, you have a made a withdrawal.

Taking dividends is literally no different to a portfolio withdrawal, and when you take the dividends from high dividend stocks, you have made a larger withdrawal, which exacerbates the problem when there is a stock market decline.

It is absolutely shocking to me that someone who was a financial advisor doesn't know all of this.

Dudley.
February 17, 2020

"when you take the dividends from high dividend stocks, you have made a larger withdrawal":

... which enables withdrawal of tax credits from ATO, both of which can be 'deposited' to earn again.

J.D.
February 19, 2020

Franking credits are largely priced-in (see the below link for an explanation of what that means)
https://www.passiveinvestingaustralia.com/franking-credits-how-much-more-are-you-really-getting

Besides that, there are drawbacks to focusing on dividends.
1. Dividends are taxed while you're receiving your full-time salary - and at your highest tax bracket, potentially even pushing you into a higher bracket. You can't elect to delay realising gains until after you've retired where your returns would be taxed at time when you have no other salary.
2. Dividends miss out on the massive benefit of the 50% CGT discount.
3. Franking credits may be gone in the future.
4. Chasing yield is risky. It deters people from diversifying internationally leaving you over exposed to an isolated economic crisis. Also, since your income and job security are tied to Australia, by not diversifying internationally you increase the risk of your income and investments going down together. You also miss out on improved risk-adjusted returns from investing globally.


Leave a Comment:

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.