Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 173

How rebalancing can help your portfolio

As with most things in life, it is the less exciting aspects of managing a portfolio such as rebalancing that turn out to be the most important. So what does rebalancing mean? Quite simply, it’s repositioning your portfolio back to target weights.

This is the first in a series exploring different methods to rebalance a portfolio. There are plenty of ways to do this, but here we start with the simplest method – calendar rebalancing, which means rebalancing over a set period of time, and it can be done at different time intervals.

'Set and forget' performs worst in this example

Assume we started in August 1996 with $100,000 to invest and run the analysis for 20 years. We chose four stocks – BHP Billiton (BHP), Commonwealth Bank of Australia (CBA), National Australia Bank (NAB) and Woolworths (WOW). We set our target weights at 30%, 20%, 20% and 30% respectively. This is not about portfolio construction, so for illustrative purposes four stocks is enough.

We consider four scenarios; ‘Set and forget’, monthly, semi-annual and annual rebalancing. We rebalance our portfolio irrespective of what the stock price has done, what we think (or hope) it’s going to do and simply buy or sell shares at the calendar end of the period to take our target weights back to our starting position. With calendar rebalancing, there is no emotion.

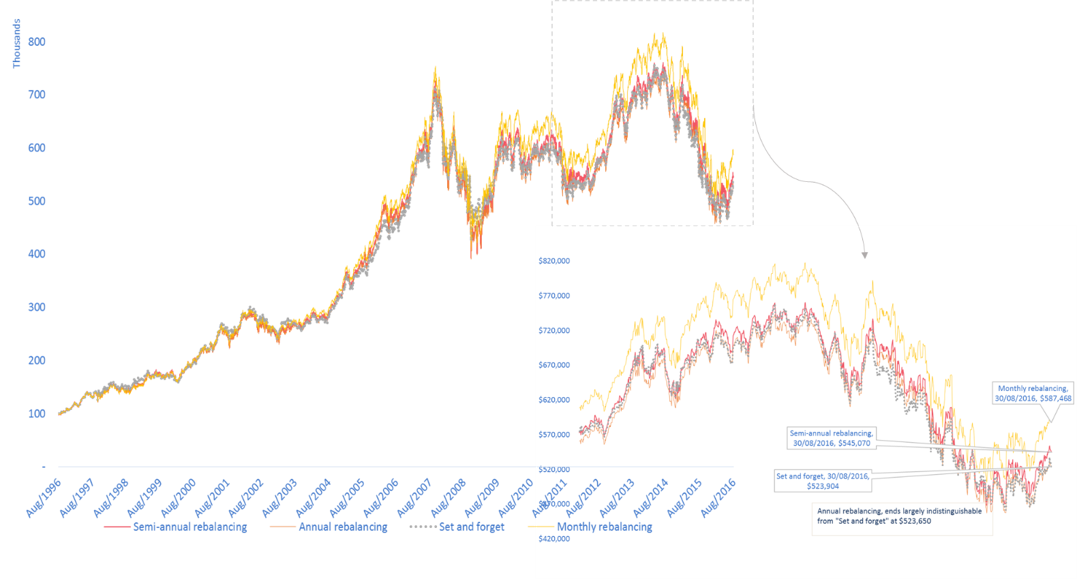
‘Set and forget’ lets us down here with a final portfolio value of $523,000.
Source: FactSet, Owners Advisory, September 2016 (Click to enlarge)

However, simply rebalancing the portfolio (albeit a very simple portfolio) monthly gives a final portfolio value of $587,000, semi-annual rebalancing gives a final portfolio of $545,000, and for this portfolio, annual rebalancing adds no value. The total returns for these portfolios are shown in the table below:
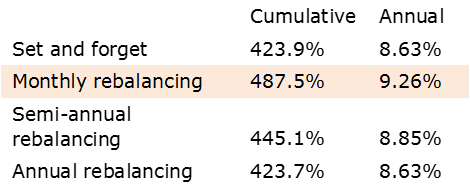
The performance difference from rebalancing is significant, particularly over a long period of time. Why? Let’s look at two of these scenarios and the weights through time to show the story.

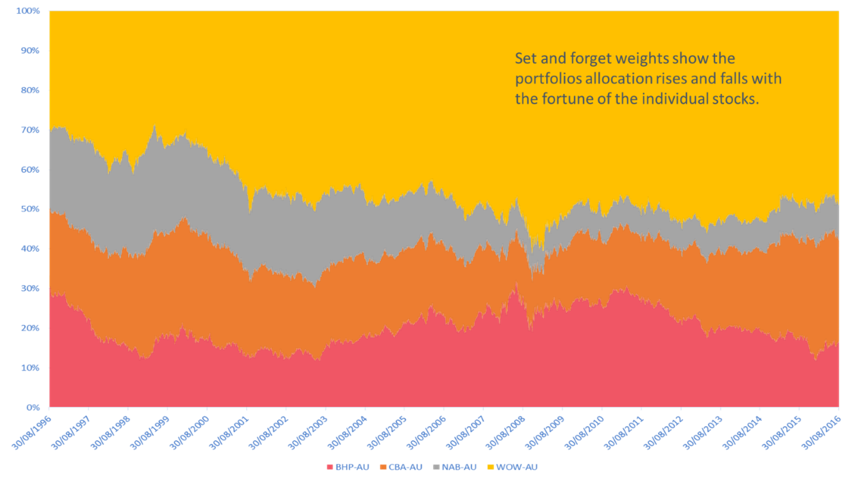
‘Set and forget’ weights through time impact performance
Source: FactSet, Owners Advisory, September 2016

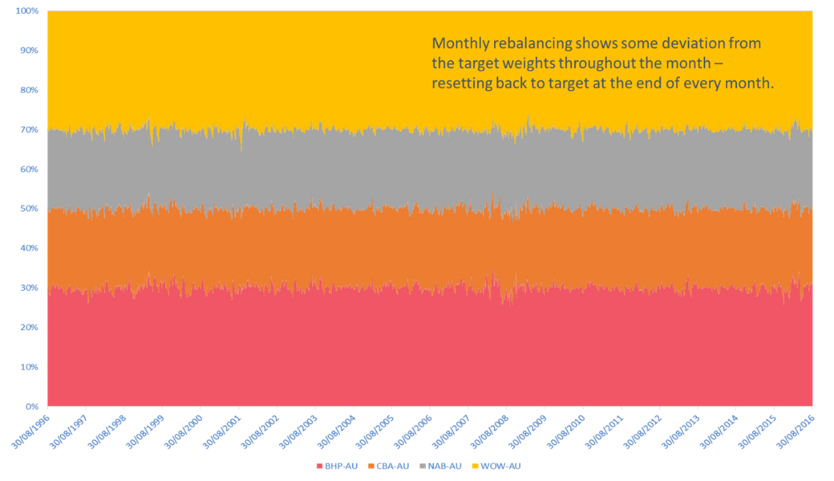
‘Monthly rebalancing’ holds our exposures largely constant through time
Source: FactSet, Owners Advisory, September 2016

Looking at the weights through time we see that, should we just set and forget, Woolworths becomes a large position in our portfolio. In fact, our dollar holding in the set and forget portfolio increases to over 50% of our portfolio.

In our monthly rebalancing, we begin to see why rebalancing performs the best for a concentrated stock portfolio. By design, we buy stocks when they have fallen below our target weight and we sell stocks when they have risen above our target weight. We are implementing the ‘trader’s catch-cry’ of buying low and selling high simply because we have held true to the weights we started with.

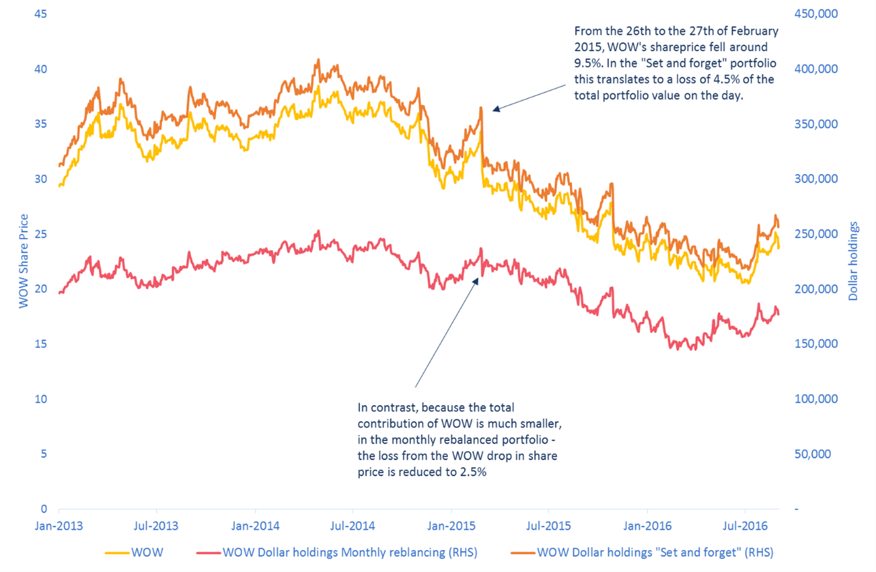
The second reason why rebalancing helps is it is the simplest method of portfolio risk control. Consider WOW: in the set and forget portfolio, we have let our best performers run, which is a very tempting way to manage a stock portfolio. But looking at what happens when WOW reprices reveals the other side of why a rebalancing regime helps overall portfolio performance.

By 2015, in the ‘set and forget’ portfolio the dollar holdings in WOW has risen to approximately $400,000, as opposed to around $200,000 in the monthly rebalanced portfolio
Source: FactSet, Owners Advisory, September 2016

Woolworths fell 9.5% on 26 to 27 February 2015, costing us 4.5% in the entire portfolio on the day ($30,000 in dollar terms). However, in those portfolios where we have controlled our total exposure to a single stock, we see that while we still suffer a loss, it is only 2.5% of the portfolio’s value ($18,000 in dollar terms).

Simply having the discipline to hold shares at predetermined weights can go a long way to adding value to the total portfolio’s returns over the long term.

In the next instalment, we look at using the percentage deviation from target weights as our rebalancing trigger to see whether we can improve our overall portfolio performance by being just a little bit more sophisticated.


Leah Kelly is Portfolio Manager at Owners Advisory. This article is general information and does not consider the circumstances of any individual.


  •   15 September 2016
  • 6
  •      
  •   
6 Comments
sandgroper
September 15, 2016

Hi Leah, capital gains tax (particularly for individuals but also for super) would be a major source of performance leakage from this strategy, have you looked at after-tax performance of rebalancing vs set and forget? Thanks

Leah
September 15, 2016

Hi - thanks for your question. I will be looking at that in part 3 as yes - it certainly changes the numbers reported.

gismo
September 16, 2016

Furthermore, were trading costs included? I think they would have been relatively significant to the monthly re-balancing portfolio.

Kevin
September 17, 2016

Rebalancing always baffled me,the high costs of churning as others have pointed out.Shooting the horse that wins the race to feed it to the ones that lost,weird.Should we not just let winners run?

I would have no problem with a concentrated portfolio,looking for the end result and the magic of compounding.The dividends they would bring in after retirement.

Have dividends been reinvested as the total seems a bit low.If they have then CBA would now be far ahead of all the rest of that portfolio,probably with a good performance from WOW.

I remember reading the 'Top stocks ' book in the early 1990s,I forget the name of the guy that writes it.Of 10 stocks I think 3 of them went bust,but the silly thing was,he had sold out of Westfield.Westfield had swamped the rest of the portfolio and was worth more than all the other shares put together.Preaching the necessity to rebalance so the portfolio was not concentrated.

I would what Frank Lowy's answer would be if somebody told him he was silly for not rebalancing,just a thought.

Ramon Vasquez
February 11, 2018

Hi Everyone ...

Thanks very much for the article , especially as l have been to much of a trader ,but am now approaching retirement age and need to change my style accordingly .


Would it be possible to make a comparison similar to the outline and some querical objections , against an EQUALLY WEIGHTED portfolio of the same four stocks , l wonder ???

Best wishes , Ramon Vasquez .

Errol Davey
August 17, 2019

The figures would be vastly different if the 20 year period was from 1999 to 2019, WOW is now $36.00.


Leave a Comment:

RELATED ARTICLES

The new capital gains tax trap for your portfolio

Solving the Australian equities conundrum

With markets near record highs, here's what you should do with your portfolio

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.