Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 319

Retirees facing steep increases for basic items

The ASFA Retirement Standard benchmarks the annual budget needed by Australians to fund either a 'comfortable' or 'modest' standard of living in the post-work years. It is updated quarterly to reflect inflation and provides detailed budgets of what singles and couples would need to spend to support their chosen lifestyle.

What does modest and comfortable mean?

A modest retirement lifestyle is considered better than the age pension but still only able to afford fairly basic activities.

A comfortable retirement lifestyle enables an older, healthy retiree to be involved in a broad range of leisure and recreational activities and to have a good standard of living through the purchase of such things as:

  • household goods
  • private health insurance
  • a reasonable car
  • good clothes
  • a range of electronic equipment
  • domestic and occasionally international holiday travel.

The June quarter 2019 figures indicate that couples aged around 65 living a comfortable retirement need to spend $61,522 per year and singles $43,601, up 0.8% for each on the previous quarter. At the modest level there was an 0.6% increase for singles and a 0.5% increase for couples.

These various changes are more or less in line with the All Groups CPI 0.6% increase between the March and June quarters.

Over the year to the June 2019 quarter, costs were up around 1.5% for couples at both the comfortable and modest levels, compared to the 1.6% increase in the All Groups CPI. This equates to couples needing to spend $918 more a year, and for singles the amount is $648.

Budgets for older retirees rose from the previous quarter by around 0.7% at the comfortable level and by 0.5% at the modest level.

Many retirees would have welcomed the recent decision to decrease the deeming rate in the asset test for the age pension but at the same time they have been facing increased costs of living and lower returns from investments, such as term deposits. Having sufficient savings in superannuation to support the lifestyle Australians want and deserve in retirement is an imperative. Moving to 12% for the Superannuation Guarantee is a necessity for those not yet retired.

Prices that have risen substantially

However, while the increase in the headline rate of the CPI might not look large, retirees have been facing significant increases in the price of many necessities of life. The drought has impacted the prices of a range of foods, the cost of private health insurance continues to grow at around twice the general rate of inflation, and petrol prices are up.

The costs for retirees that increased substantially over the last 12 months are:

  • Price of bread up by 4.8%
  • Price of beef up by 6.0% and lamb up by 13.5%
  • Price of milk up by 2.9%
  • Price of fruit up by 4.9%
  • Price of vegetables up by 6.2%
  • Price of beer up by 2.5%
  • Property rates up by 2.3%
  • Price of hairdressing up by 2.9%
  • Price of private health insurance up by 3.25% on average
  • Price of dental services up by 2.3%
  • Price of domestic travel up by 3.5% and price of international travel by 4.1%

The most significant price increases in the June quarter were automotive fuel (10.2%), medical and hospital service (2.6%) and international holiday, travel and accommodation (2.7%).
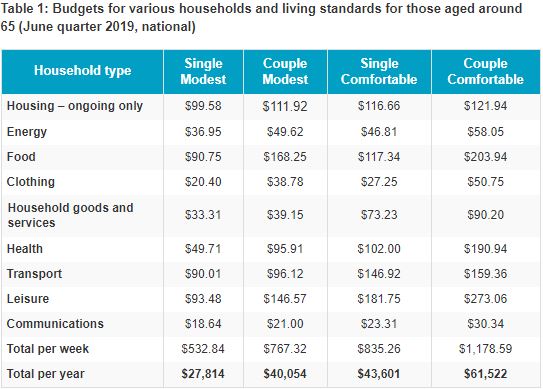
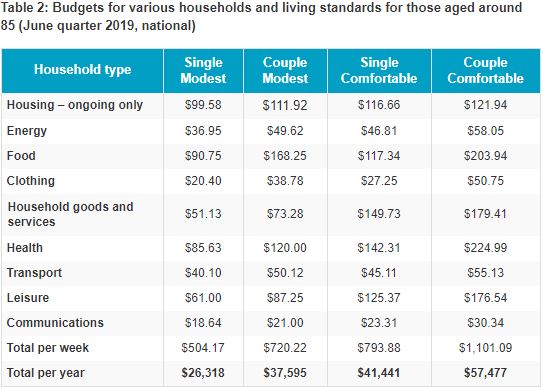
The figures in each case assume that the retiree/s own their own home and relate to expenditure by the household. This can be greater than household income after income tax where there is a drawdown on capital over the period of retirement. All calculations are weekly, unless otherwise stated. Annual figure is 52.2 times the weekly figure.

More information

Costs and summary figures can be accessed via the ASFA website. ASFA provides individual calculators to help Australians plan for retirement. Australians can find out more about superannuation on the independent Super Guru website.


Martin Fahy is Chief Executive Officer of The Association of Superannuation Funds of Australia (ASFA), the peak policy, research and advocacy body for Australia’s superannuation industry. This article is general information and does not consider the circumstances of any person.


  •   13 August 2019
  • 5
  •      
  •   
5 Comments
Frank
August 14, 2019

Most important to realise is all these numbers assume you own your own home. This will become increasingly uncommon putting a lot of pressure on older folk.

Graham W
August 16, 2019

What a load of rubbish that retirees need $65k pa. I know many pensioners solely receiving the age pension that have full and active lives. As long as you own your place of residence this is pretty much a given,apart from mainly the capital cities. We maintain a large home ,3 vehicles and lots of holidays towing a luxury caravan,more like $50k pa.
We all started as frugal baby boomers and know how to make a quid stretch ,without economising too much.The north of WA is chokka with caravanners enjoying the good life,few need $60k pa to live a life in their unit doing little but watching the goggle box.Economists are rubbish.

Peter W
August 17, 2019

Graham W,
I would suggest that you may not represent all retiree's. I think I can make a number of assumptions about you.
You are obviously blessed with extremely good health as health can be a major cost to a retiree. Also i wonder if you even have private health cover which is another cost. You don't have any diet issues as the cost of food if you have an intolerance is much higher than usual. Also you obviously don't travel overseas or if you do it is to very low cost destinations on a low budget and a rare occasion. Also when I consider you own three vehicles and a caravan and considering the depreciation, running costs and the maintenance cost on your home I would like to see look over your finances to see how you manage on $50k a year. Sorry but I very much doubt your costing.

Roger Farquhar
August 16, 2019

I would think that these sums are conservative and are dependent on what you consider to be comfortable. Our housing - rates and insurance - are far more than allowed and then there are the inevitable replacements due to wear and tear.

Yes there are retirees on the road - they crawl along in high gear to save fuel and budget from one park to the next.

Geoff
August 19, 2019

I've run my personal numbers for (retired) life at 60 and they're certainly way, way higher than the comfy / miserable numbers that are forever being touted and upgraded by ASFA. I can't see that all that much will change between 60 and 65. People should interrogate them and come up with their personal costs and work backwards from there. Guidelines, not rules.

You just don't get two phones, an internet connection and a "sinking fund" style allowance for replacing a couple of laptops and/or tablets every five years or so for $30.34 a week (communications/comfy/couple/65). Not even close. And that's modern day essential for a cohabiting couple, I'd suggest.

And is wine under food, health or leisure? :)


Leave a Comment:

RELATED ARTICLES

Retirement affordability myths

Clime time: Inflation cruels a comfortable retirement

Why spending more in early retirement can improve lifetime income

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.