Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 164

For sale: cheaper apartments

Governments and banks have reacted to concerns over the east coast housing boom by instigating cooling measures. Tighter loan criteria, additional stamp duties, and the election debate over negative gearing are all designed to slow prices. However, as the charts below show, there’s no need to do anything: the east coast market is about to be swamped with apartments.

The UBS economics team believes there should be a moderation rather than a downturn, as the tailwinds from record low interest rates offset the headwinds of tighter banking criteria and higher taxes. What is most concerning though, is the impending supply of apartment stock.

Record unit approvals

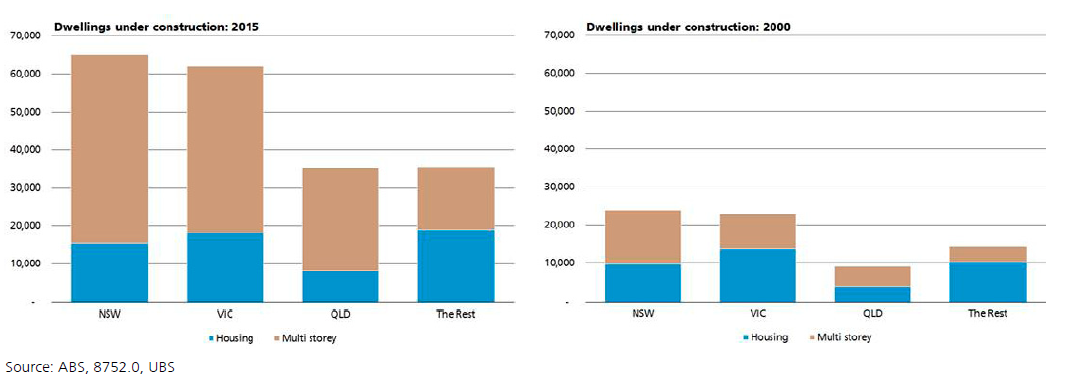
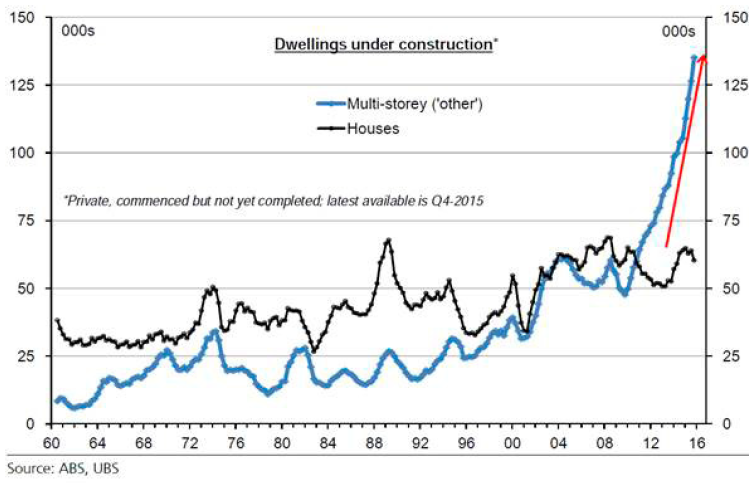
Last year I wrote about the record number of unit approvals along the east coast, with particular concerns about the expected levels of supply in Melbourne and Brisbane. Roll forward to June 2016 and most of those approvals have turned into commencements, with around 137,000 medium density dwellings now under construction. This is about four times more than was under construction in 2000, with 88% of the national total in NSW, Victoria and Queensland. The spike in multi-storey apartments can clearly be seen below, while housing is within historical ranges.

Chart 1: Dwellings under construction in Australia
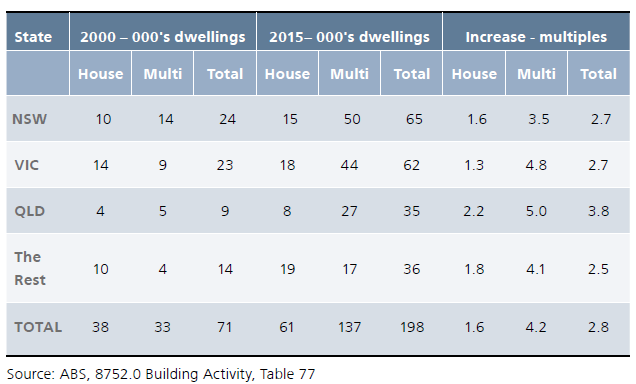
In absolute number terms, it's startling. Construction of apartments in Queensland is running at five times its levels from the year 2000, while NSW and Victoria each represent over 30% of all supply.

At the project level, supply in Queensland and Victoria is largely centred around CBDs, while NSW supply is dispersed across metropolitan areas, spreading the risk. With this supply largely hitting the market in the next year, will those who paid a 10% deposit be able to finance the settlement of the remaining 90%? As a rule of thumb, we estimate that about 70% of purchasers are local buyers (owner occupiers and investors), while about 30% are connected to foreign buyers.

Table 1: Dwellings under construction by type and state as at Dec 2000 and Dec 2015


Settlement risk

The key question is whether it’s in the purchaser’s best interest to settle and that will largely depend on price movements between the dates of the deposit payment (probably 10%) and settlement.

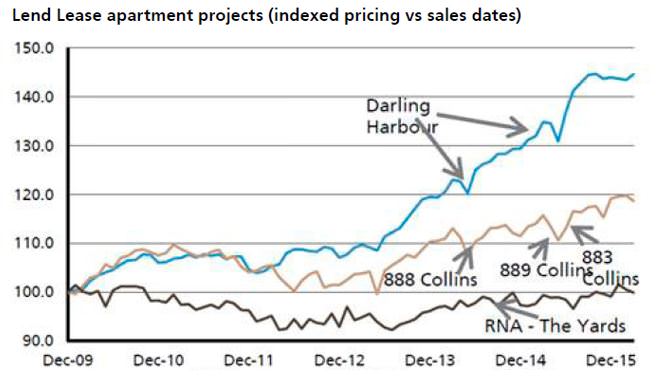
Using Lend Lease as a guide, it appears that anyone who bought an apartment in Sydney is ‘in the money’ and would forego strong capital gains if they walked away from the purchase. Developments such as Melbourne’s Collins Street and Brisbane’s The Yards are less conducive to gains, as shown in the chart below. While a profitable re-sale in Sydney seems highly probable, it seems less so in Melbourne and more difficult in Brisbane. Interestingly, Lend Lease’s highest default rate during the GFC was 3%, versus less than 1% at present. I must point out that the listed market developers like Lend Lease and Mirvac produce higher-quality units that would be more desirable in a re-sale market than some peers.
Financing switching from banks to mezzanine lenders

The great thing about a turning point in the cycle is that those with strong balance sheets and solid cashflows can take advantage of other groups’ weaknesses. I recently spoke to three mezzanine loan providers who said they’d never been busier. When the banks close the doors, other providers step forward and are happy to help, but it will cost more. All three have existing loans to residential developers with solid credentials who were refused construction finance from the big four banks. Two of these were working on plans to raise capital to ‘mop up’ developers who struggle. Those with strong balance sheets and cash resources such as Mirvac, Lend Lease and Stockland will increase their market share in the next two years.

The oversupply should lead to falling apartment rentals as investors compete to secure income. This will take the apartment yield (net of costs) to less than 2% or 50x price to earnings. Investors would do well to sit back and wait.

For those who wonder what happens to the traditional house and land site, weakness in apartments should have an impact. When inner city apartment rents decline, those renting on the fringes can upgrade location. Pleasingly, housing supply is not excessive and continues to be hamstrung by council approval processes. Note that the two markets (houses and apartments) are distinct with a large family on a suburban block with kids at the local school unlikely to switch to a CBD unit.

Of course, property investment is not only residential. A relatively high-yielding, liquid investment such as a REIT, with capital growth potential and expert management, should not be discounted. With our expectation of low rates and a healthy yield buffer above cash and bonds, we remain confident that investments in commercial property, in particular REITs, will continue to deliver solid returns.


Pat Barrett is Property Analyst at UBS Asset Management. Nothing in this document is to be taken as specific financial product advice and it does not take into account any individual investor’s investment objectives, tax and financial situation or particular needs.


  •   14 July 2016
  • 3
  •      
  •   

RELATED ARTICLES

Why investors are looking beyond traditional property sectors

Origins of the mislabeled capital gains tax ‘discount’

Steve Bennett on investing in direct property for the long term

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.