Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 315

The ‘six or out’ VC approach to portfolios

American venture capitalists (VCs) often talk about home runs. VC portfolios are structured to maximise the chance of at least one successful investment that will return the fund multiple times the original investment. Statistically, we know that around 90% of returns for VC investors will come from just 10% of early-stage investments. These are the home runs. The other 90% of businesses will either deliver a modest return or worse-case scenario, no return at all. Home runs are essential to provide the returns that set VCs apart and that investors are expecting.

In the more popular language of cricket for Australia, VC investors need to maximise their chances of hitting a six when constructing their portfolio. And those of us who have dedicated many a summer (or winter in the recent Cricket World Cup) to watching cricket will know that if a batsman protects their wicket too intensely, they can’t take the backswing necessary to hit the six. Instead, they will be forced to settle for singles and dot balls.

Losing wickets is inevitable in early-stage investing

VCs also know that losing a few wickets is an inevitable and necessary part of the game. VCs are generally comfortable with this but for some investors the idea that loss is inevitable can be uncomfortable and off putting. These investors are hindered by loss aversion and the belief that losses fundamentally loom larger than gains.

VC is different and requires a different mindset. Every investment is made with the conviction that it could be the outlier and an acceptance that many will not. It is okay to lose if there’s a big winner in the portfolio.

To labour the cricket metaphor, we can look at the statistics of cricket legend and former Indian captain, Sachin Tendulkar. During his test career, Tendulkar did not score a single run from 57% of the 29,000 balls he faced. He either blocked or let them go through to the keeper. But of the total runs he scored during his test career, over half (55%) were from fours or sixes although these made up just 7.2% of the total balls he faced. Like Tendulkar and the 29,000 balls he faced, investment in early stage businesses requires VCs and their investors to face a lot of companies and know which are worth a big swing. This is a strategic and disciplined approach to risk taking that VCs gain after years of facing start-ups.

Management of the risk

Portfolio construction in VC is geared to address and mitigate against risk factors as much as possible. Good VCs will ensure that there are enough companies in the portfolio and that there is enough diversity in terms of the different sectors and the underlying technology. Experienced VCs are also adept at spotting patterns and identifying strong founder characteristics, technical expertise and market opportunities that maximises the chances of success.

Hitting a six is not always the end game for VCs and their investors. For larger investors, this is often the beginning of a long partnership, particularly those looking to move the needle on a multi-billion dollar fund. Having identified those start-ups that are rapidly gaining traction and showing accelerated growth, larger institutional investors such as superannuation funds are able to write bigger cheques with lower risk at later stages of the business’ lifecycle. Table 1 shows the company funding life cycle with private market investors at the earlier stages and public market investors being involved at the later stages.
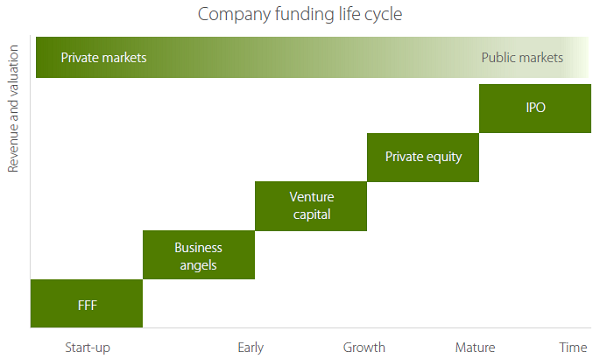
Source: Right Click Capital

The big wins afford VCs and their investors the opportunity to double down on later funding rounds (A, B or C rounds) and participate in growth across other stages such as co-investment opportunities, whether directly or through a mandate structure, and public listings. As high-performing investments progress through the business lifecycle, over time they provide strong returns for a superannuation fund’s venture capital, private equity and listed equities teams.

Table 2 shows an estimate of the number of Australian-based companies raising money in 2018 by stage of investment and reveals a far greater number of opportunities to invest in seed rounds than series A, B and C rounds.
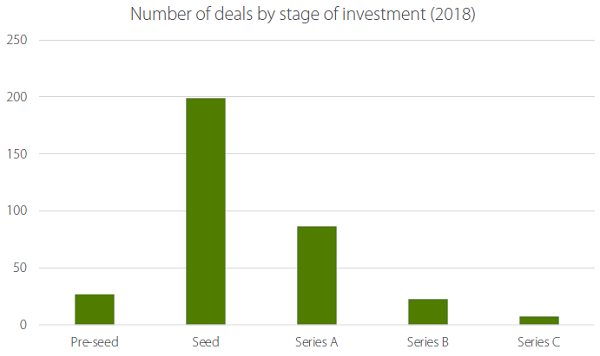
Source: Crunchbase

Table 3 shows the median and average amounts invested in the same deals in 2018 and demonstrates the ability of VCs to invest larger amounts at the later stages of funding as they identify the investments where they have hit a six. VCs who put money to work in businesses at earlier stages need to continue investing in a business’s subsequent rounds in order to maximise their upside when they’re on a winner.

Source: Crunchbase

It’s more about the long term than quick wins

VC often marks the start of a long-term partnership between an investor and a start-up. Ram Nath Kovind, the first Indian President to visit Australia recently commented, “The most successful Australian batsmen in India have been those who have shown patience, read the conditions carefully, settled down for a long innings, nurtured their partnerships and not fallen for spin”.

The same is certainly true for VC investors.


Benjamin Chong is a partner at venture capital firm Right Click Capital, investors in high-growth technology businesses. This article is general information and does not consider the circumstances of any investor.


  •   17 July 2019
  • 1
  •      
  •   

RELATED ARTICLES

Blockbuster AI debt issuance coming to a bond market near you

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.