Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 125

Super engagement better than expected

In mandatory retirement savings systems like Australia’s Superannuation Guarantee, default options are critical. A ‘default’ is where the investment is chosen on behalf of the investor, such as by their employer. In other words, the investor accepts the default option. International research and experience show that ‘passive’ regulatory settings like defaults are far more important than those relying on active decisions like tax concessions. Super fund members face two key defaults: the fund itself and then the investment strategy.

The recent introduction of MySuper gave the superannuation sector a reason to review and renew default settings. And with the support of the Centre for International Finance and Regulation, the research paper, Delegation, trust and defaulting in retirement savings: Perspectives from plan executives and members, was commissioned to find out how well the refurbished MySuper defaults fit the people they are designed for. We interviewed superannuation fund executives and collected their impressions of member needs and characteristics, and the goals of MySuper defaults. Then we surveyed over 1000 members on their default behaviour, reasons for defaulting or opting out, and their superannuation goals.

More active choices than expected

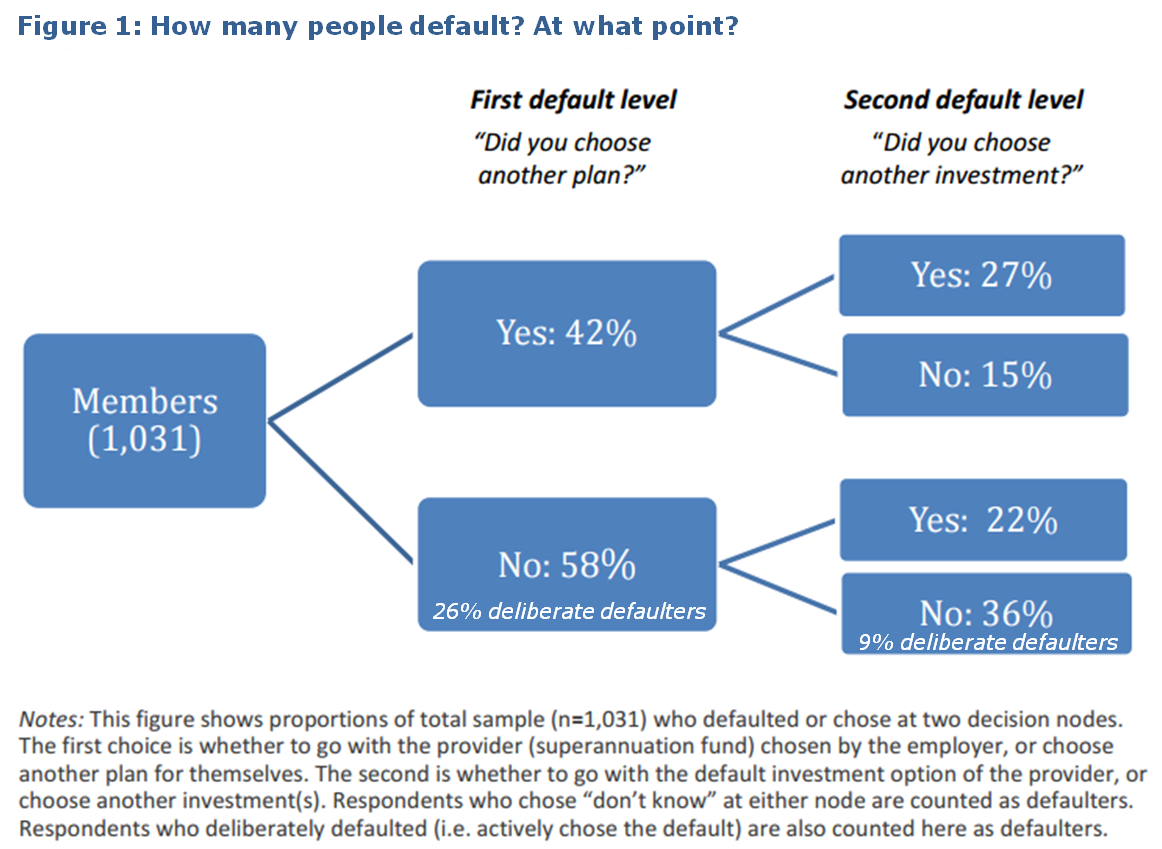
More members described themselves as active choosers than we expected. The diagram below shows the proportion of members who stayed with the default fund and default investment option. Only 36% of our sample defaulted at both stages, meaning that 64% made at least one active choice.  Also, around one-quarter of members in the default fund and 9% of investment defaulters chose the default options deliberately. So the proportion of completely passive defaulters in our sample is probably below one-third. Clearly, not all defaulters are completely disengaged or uninformed, and conversely non-default choices are not a simple proxy for member interest and engagement.
Defaulters are more likely to be younger, female and have lower incomes than non-defaulters. As account balances rise and retirement approaches, the costs of a non-optimal default become larger and are likely to prompt more members to make another choice. Interestingly the financial literacy of defaulters was only a little lower than that of choosers and the difference was not statistically significant.

Interest, trust and defaulting

We also asked members about their reasons for defaulting versus choosing. Most people said they do not want to relinquish control over their retirement savings, but they found the products suitable, and viewed the fund as trustworthy and accountable.  Respondents in the default investment option emphasised more than others their own low skill and knowledge. Respondents in the default fund expressed more trust and belief that the system is well monitored. Time costs of active decision-making were rated high more often than money costs. These results are at odds with some industry commentary that characterises default members as uninterested in superannuation.

A lack of interest was not the main reason for delegating investment to the fund according to the survey (although it did have some impact), and neither is relinquishing control. However, interviews with fund executives suggested that trust is sometimes mistaken for disengagement. Trust, when combined with a self-conscious lack of financial skill, underlies both a low level of active choice and a low level of direct interaction with the fund.

Goals for superannuation

In terms of goals, members emphasised achieving a basic amount of wealth for retirement. This lines up with comments from interviews where executives framed default design in terms of retirement outcomes rather than short-term performance. However there is little agreement in the sector about what are the best strategies to reach this goal.

Members thought low fees were an important, but not the most important, aspect of a fund’s goals. This also seems broadly consistent with executives, who acknowledge that fees matter but view them as constraints rather than objectives.

A noticeable area of difference between executives and surveyed members relates to risk tolerance. The clear skew towards low risk tolerance among default members stands in contrast with relative aggressive investment strategies, where growth asset exposure averages over 70%. While life cycle funds are designed to de-risk near retirement, many executives express the view that default members need strategies with high growth asset exposure in order to generate higher balances and retirement incomes.

Regulators and industry might improve member outcomes by developing smart defaults that allow for a variety of risk preferences and demographics. The study emphasises the dangers of misconstruing super fund members as uninterested: instead, many see themselves as low in skill but high in trust.


Susan Thorp of the University of Sydney co-authored the research paper with Adam Butt of the Australian National University, Scott Donald of University of NSW, Doug Foster of the University of Sydney, and Geoff Warren of the Centre for International Finance and Regulation.


  •   4 September 2015
  • 1
  •      
  •   

RELATED ARTICLES

Reply to Peter: Why a glide path makes sense, with equities for growth

Lifecycle funds increase super engagement

Are lifecycle funds appropriate for MySuper products?

banner

Most viewed in recent weeks

Will you run out of money in retirement?

Fear of running out has become a defining retirement anxiety. Why do some retirees die with substantial wealth while others deplete their nest egg? Evidence suggests the answer is more complicated than we think. 

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

The investment that sidesteps the new tax traps

Tax rules have changed, but many investors are still using yesterday’s strategies. Insurance bonds may offer advantages for those seeking greater control, tax efficiency and certainty about their wealth.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Investment strategies

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Economy

Population growth masks Australia’s productivity problem

For years, investors have benefited from a seemingly reliable growth story. But recent national accounts raise uncomfortable questions about what has really been driving Australia’s economy and whether that can continue unchecked.

Investment strategies

Why tomorrow’s winners may not be today’s index leaders

The stocks that built retirement balances over the past decade now dominate many portfolios. The new challenge is whether these companies can continue meeting the increasingly high expectations embedded in today's share prices.

Investing

What earnings surprises reveal about future returns

Sometimes the most important information in an earnings result isn't the number itself. It's the possibility that the market's assumptions have been fundamentally wrong and future earnings may look very different.

SMSF strategies

Individual SMSF Trusteeship directly liable for ATO fines

A rarely discussed detail buried in SMSF structures could dramatically change who wears the cost when something goes wrong. With penalties rising, a decision many dismissed as administrative may deserve a second look.

Investment strategies

The currency bet you didn’t know you made

Buying global shares means making two bets: on the companies and on the Australian dollar. Most investors consciously choose only the first. Last financial year, the second bet cost 8.5% in returns for many investors.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.