The Federal Government’s restriction to negative gearing for residential property investment has sparked talk that people may instead borrow money to buy shares.
That may seem like an alien concept to Australians unfamiliar with the use of “gearing” in sharemarkets, or a painful reminder to others of losses incurred during the Global Financial Crisis. However, the reality is that gearing in sharemarkets is based on the same principle as buying a property with a loan: it allows the borrower to increase their exposure to an investment to amplify potential gains.
A well-structured gearing strategy with stringent risk management may be a worthwhile component of a diversified investment portfolio for investors who have a proper understanding of how gearing works.
The geared options available to investors have changed since the late 2000s, when many people who took out direct loans to buy shares received “margin calls” when stockmarkets slumped. A margin call means a borrower must inject extra cash into a loan to restore the agreed loan-to-value ratio, or risk having their shares sold from under them by lenders.
Gearing sweet spot
Investors suited to gearing can now gain leverage by investing in managed funds with geared portfolios – instead of borrowing money themselves. The benefit is that an investor’s dollar on day one is the full amount at risk without the threat of margin calls in a market decline.
Some people may also be put off geared share investing by the volatility of stockmarkets. Property values can also fluctuate significantly, although those movements are observed less frequently than listed share prices. The difference is the ups and downs of shares are recorded on a daily basis by a stock exchange, whereas property prices are reported less frequently.
The upshot is that a diversified geared portfolio can allow thoughtful investors to gain slightly more growth assets (that is, shares) without taking on incremental risk relative to the broader sharemarket.
Our modelling suggests that investors are able to gain exposure of up to 120% of their original capital by using a combination of geared managers and diversified asset allocation, whilst taking on similar risk levels to an investment in equities alone.
This 120% exposure is the ‘sweet spot’, providing investors with the right balance between increasing expected returns and managing the volatility a portfolio is likely to experience over time.
As investors increase exposure beyond that, the incremental risk to reward ratio begins to decline. That is, the benefit of gearing starts to wane. For some investors with a very long time frame, it might still be an appropriate strategy but unlikely for everyone.
Here is the maths: combining geared equity funds with other equity exposure and real assets (to get a total growth exposure of 120%) generates an expected return of close to 10% for a diversified portfolio, with around 14% of volatility. This compares favourably to the expected volatility for Australian equities of around 15%.
With a higher gearing ratio, say 150%, our modelling shows an annual return of 11.2%, but an expected volatility of 18.6%. So, with gearing of 120%, the return-risk ratio is 0.65. For gearing of 150%, it is closer to 0.6.
Not just for young people
So, who is suited to geared equities investing? Younger people accumulating wealth are obvious prime candidates, given their long runway for capital growth and ability to recover from market dips. But early retirees can also benefit from exposure to a geared managed fund – especially because it gives them the ability to gain leverage without exposing themselves to potential margin calls.
For example, an individual entering retirement may want to generate not only sufficient income for everyday life, but also to build sufficient capital for later expenses related to old age or to leave an inheritance to chosen heirs.
A small exposure to geared equities could enable that earlier retiree with a 20-plus year investment horizon to address both needs. To illustrate this, consider an investor with a $1 million portfolio. Allocating $200,000 to a strategy with 120% equity exposure provides the economic equivalent of approximately $240,000 invested in equities. Compared with a traditional $240,000 equity allocation, the investor has effectively retained $40,000. The capital not required to achieve the desired level of equity exposure can then be allocated to income-producing, defensive or diversifying assets, depending on the investor’s objectives.
A “bucketing strategy” could be used to structure their overall assets. This involves dividing retirement savings into separate ‘buckets’ or categories, each with its own purpose, strategy and risk profile (being the expected variation in investment returns each year).
Using a three-bucket strategy, for example, money could be split as follows:
- The spending bucket (cash) – to spend over the short term, say the next 1-2 years
- The security bucket (primarily defensive assets) – to spend over the medium term, say the next 3-4 years
- The future bucket (growth assets) – to hold the balance of savings for the longer term. This final bucket could use gearing to help replenish the other buckets over time.
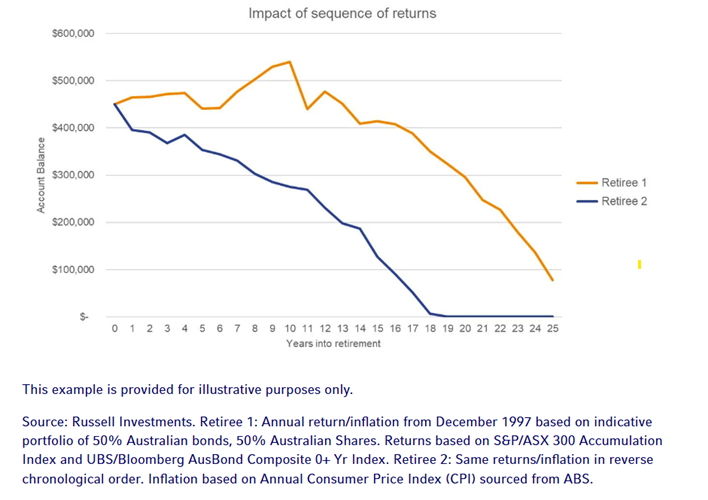
A bucketing strategy not only helps generate longer term gains. It can also help manage “sequencing risk” – or the risk that poor returns early in retirement mean that super savings run out earlier than expected.
For example, many retirement plans assume super will return, say, 7% on average over time. That can easily be taken to mean funds will return 7% year in, year out. But financial markets don’t perform in a uniform way. Some years they rise. In others, they fall sharply or move sideways. It is the sequence of those good and bad years – not the average return over time – that often determines how long super will ultimately last after a retiree begins to draw on it.
Consider two hypothetical retirees with a $450,000 super balance who draw $30,000 annual income from it (indexed for inflation). Both can be invested in the same way, with an average return of 7% over 25 years. One runs out of super seven years earlier than the other due to the sequence of their annual returns (see graph).
A spending bucket would help the less fortunate person manage this risk by maintaining a portion of their capital in liquid assets that are not exposed to market falls. This means they could still generate income from their cash without drawing on their growth capital at a time when its value has fallen.
Click to enlarge
Buyer beware
Whatever their life stage, an investor considering gearing must be confident they can stomach the volatility of market falls. Gearing isn’t for everyone.
Younger people wanting to increase their superannuation savings may need an investment time frame of 30 plus years to get the optimal result, and retirees should have at least 20 years ahead of them.
Both categories of investor must also understand that gearing amplifies losses as well as gains: so the outcome of selling assets in a panic can be more painful than usual. For example, the average market drawdown during a recession is around 35%. With gearing, that drawdown can be exacerbated to 50% or even higher (depending on the level of leverage used).
The longest drawdown in US equity markets since 1964 is an 89-month period between 1973 and 1980 – so young investors with a 20-30 year time horizon are likely to have the ability to recover fully from any drop in the value of sharemarkets. Early retirees may also have a sufficient investment horizon to allow them to weather bouts of volatility.
For investors who understand the risks and have a sufficiently long investment horizon, gearing need not be confined to property. Used carefully, it can be another tool for enhancing long-term portfolio outcomes. As always, it is sensible to seek professional advice to determine the most suitable investment strategies for individual needs.
Alex Cousley is a senior investment strategist at Russell Investments. These views are subject to change at any time based upon market or other conditions and are current as of the date of publication. The information, analysis, and opinions expressed herein are for general information only and are not intended to provide specific advice or recommendations for any individual or entity. This material is not an offer, solicitation or recommendation to purchase any security.