Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 204

The big three investment risks in retirement

The transition to retirement can be challenging, as retirees adjust to major changes in their lifestyle and finances. Entering retirement means the end of employer-sponsored pay cheques and a reliance on personal financial capital, plus any age pension entitlement, to maintain a desired lifestyle. In economic terms, the human capital has expired and the financial capital must take up the heavy lifting. This can be quite a mental and emotional hurdle for many retirees to overcome.

To make sure retirees' financial capital (superannuation and other wealth) is able to meet their needs, it is important to understand the major investment risks facing those in retirement: Longevity, Sequencing and Inflation risks.
Three investment risks: longevity

Three investment risks: longevity

Living longer than expected may not seem like a bad thing and, all else being equal, it’s not. Longevity risk is the risk of outliving your capital rather than living too long, per se.

We have a reasonably good understanding of life expectancies. According to ABS Life Tables, for the average 65-year-old man, it is around 84.5 (or, looked at another way, another 19 years after retiring) and 87.3 for woman (or another 22 years). However, these are average figures and therefore around 50% of people will live longer, for another 6 or 7 years. An easy way to adjust for this, and therefore provide a reasonable chance of not outliving savings, is to plan for financial capital to last an extra five to 10 years longer than initial life expectancy.

Life expectancies are increasing over time as health standards improve. A cure for cancer, for example, or any similar advancement in medical research, will have the potential to increase our life expectancies substantially in a short period. While this would be a welcome development, it would also make longevity risk a bigger investment risk for retirees.

The age pension offers protection against longevity risk by providing for our base minimal income requirements, although emphasis should be placed on minimal (with no certainty of future levels). Other financial products offer hedges against longevity risk, such as lifetime annuities, but these tend to have relatively high implicit costs associated with providing a lifetime guarantee and offer relatively low returns. Investors should therefore consider these options cautiously, in our view.
Three investment risks: sequencing

Sequencing risk is the risk of an adverse market event, such as a GFC, occurring at a time when the dollar value of an investor’s portfolio is largest. For retirees, this is usually during the early stage of retirement. A 20% fall in portfolio value would hurt more in dollar terms at this time than it would early in their working lives or much later, when their account balances are generally much smaller. It is also harder to recover from an adverse market event (or sequencing risk event) in retirement because the investor is drawing down on capital at this time, meaning there is a smaller capital base from which to recover after such a loss.

When considering its impact, we tend to overstate the impact of a sequencing risk due to our inherent behavioural biases. We have a tendency to measure our losses against the previous peak of our portfolio wealth, typically at the top of an economic or share market cycle where valuations of assets are at their highest and often overvalued.

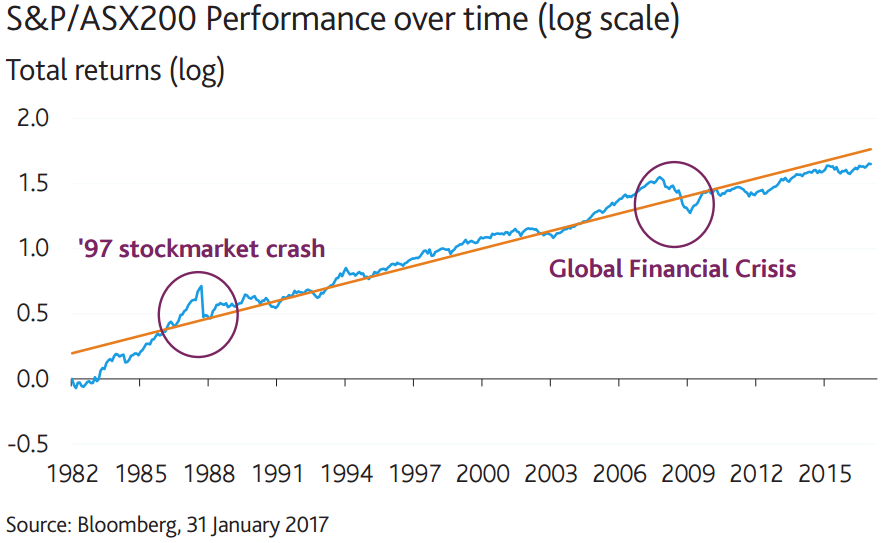
The example in the following chart shows the accumulated value of the S&P/ASX200 Accumulation Index over time (in log scale), including the average return (straight line). Prior to both the 1987 share market fall and the GFC, where equity markets fell by approximately 50% each time, returns had been well above the average in the preceding period. In the case of 1987, the share market had roughly doubled in value in the preceding 12 months before falling by half, or in other words, returning to where it started. The same occurred during the GFC, although the rise and fall happened over longer timeframes.
investment risks

To manage sequencing risk, the portfolio should be properly diversified and match the retiree’s risk tolerance. Investors should realise, at least retrospectively, that account balances at the top of a bull market are probably too high and losses from previous peaks will probably be overstated.
Three investment risks: inflation

Inflation is possibly the most underestimated of the three investment risks.

The impact of inflation in any given year, say 2-3%, compared to the impact of a 50% sequencing risk event, seems small. However, if inflation occurs year in, year out, its compounding impact over a long-term retirement can be substantial. Inflation of 2-3% per year over 20 to 30 years can reduce purchasing power by 50% or more. While this roughly equates to the impact of a 50% sequencing risk event, the two differ in their probability. The risk of inflation causing a 50% reduction in purchasing power in retirement is highly likely over a 20-plus year period, whereas a 50% sequencing risk event like 1987 or the GFC might occur only once on average during that time. What’s more, a retiree would need to be at or near the point of retirement to feel the full force of the sequencing risk event.

The lesson therefore is to be aware of and manage the incremental, yet compounding and therefore significant, impact of inflation on investment portfolios in retirement.

This can be achieved by:


  • Ensuring sufficient growth asset exposure in the portfolio. Overweight exposure to nominal return assets such as cash and term deposits can mean that your retirement income is not inflation hedged.


  • Aligning your investment objective to outperforming inflation, such as using a ‘CPI+’ approach as a benchmark or objective makes more sense for the average retiree compared with managing against more traditional market benchmarks.


Moving into retirement can be a challenging time, with financial stability a real concern. Retirees need an understanding of the major investment risks and have appropriate strategies in place to manage them in order to enjoy a more financially-secure retirement.


Josh Hall is an Investment Specialist at Aberdeen Standard Investments (formerly Aberdeen Asset Management). This article is for general information only and does not consider the circumstances of any individual.

  •   31 May 2017
  • 2
  •      
  •   
2 Comments
allan
June 01, 2017

I have looked at many of the CPI plus models used by various fund managers to allow for most of what Josh is discussing but am not convinced they will always work as they think. I still prefer the 3 buckets method with cash and short term funds in the first bucket, medium term assets in the second bucket and the long term growth assets in the third bucket.
As long as the first bucket always has enough liquidity to provide between 2 and 3 years income there should be very limited chance that you will need to sell growth assets at the bottom of the market to top up liquidity.
This allows for a more aggressive growth portfolio to make the portfolio grow and as long as you keep topping up the liquidity pool from the growth pool to ensure the 2-3 years income it works.

David Williams
June 01, 2017

The consequences of increasing longevity, especially for the top socio-economic quintile (Cuffelinks readers most likely!) are both positive (opportunity) and negative (such as disability and financial inadequacy).
Average life expectancies are notoriously unreliable for planning purposes. We become more different from each other as we age, not more alike. It is much better for each person to establish an understanding of their own potential time frame and how it might proceed before even beginning to develop financial strategies.
The average top quintile 65 year old is likely to achieve almost ten years without notable disability and a further seven years of independent living. So a first issue could be – why ‘retire’ at 65? Every extra year worked will be roughly equivalent to two years of financial support, just for one reason.
For retirement planning, the most important first step is to focus on a person’s potential time frame and its consequences. This dialogue addresses almost all the variables a person struggles to deal with. They include the remaining value in personal capital (involving health, capabilities and experience), accommodation, intergenerational wealth transfer, aged care and end of life issues. The dialogue provides the assumptions which underpin the time frame. Only then can the financial situation be effectively addressed.
With hindsight we probably made a big mistake in focussing only on financial literacy as the key issue to help the community learn about superannuation and financial advice opportunities. I suspect the best impact has been on the under 50’s.
Longevity awareness is the attribute needed to better frame all our decisions as we age. It can lead to improving the quality of life and better managing the costs. It can reduce dependence on financial solutions, including the Age Pension (which increasingly unlikely to be available to anyone in the top quintile in any form). It addresses inter generational issues and the pathways to appropriate wealth transfer. It is the most important risk reduction factor in an enjoyable later life.


Leave a Comment:

RELATED ARTICLES

What financial risks do retirees face?

How decumulation in retirement differs from accumulation

Will you run out of money in retirement?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.