Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 20

What export boom?

Apparently, Australia has had an ‘export boom’ over the past decade. But is it (or was it) a boom?

Australians love to talk a lot about exporting but we actually do very little of it compared to nearly every other country in the world.

Australia is one of the smallest exporters in the world, ie one of the least reliant on exports for our national income. Out of the 200 countries in the world only six major countries export LESS than Australia as a share of their national income - Brazil, USA, Japan, Pakistan, Afghanistan and Colombia. There are also a few tiny countries that Australia does manage to beat as an exporter - including Tonga, Ethiopia and Rwanda.

Every other country on the planet exports more than Australia as a share of its national income. And that’s during our so-called ‘mining export boom’ (plus tourism, agriculture and the so-called ‘boom’ in services exports like education). There are numerous great exporting nations where exports routinely generate more than half of their national incomes from exports - a long list that includes Germany, Denmark, Belgium, Austria, Switzerland, Sweden, Netherlands, Ireland, Korea, Singapore, Malaysia, Thailand and dozens of others.

The first chart shows how the OECD countries rate on the measure of exports as a share of their national incomes, averaged over the years since 2000, which is the period of our so-called China-led export boom.
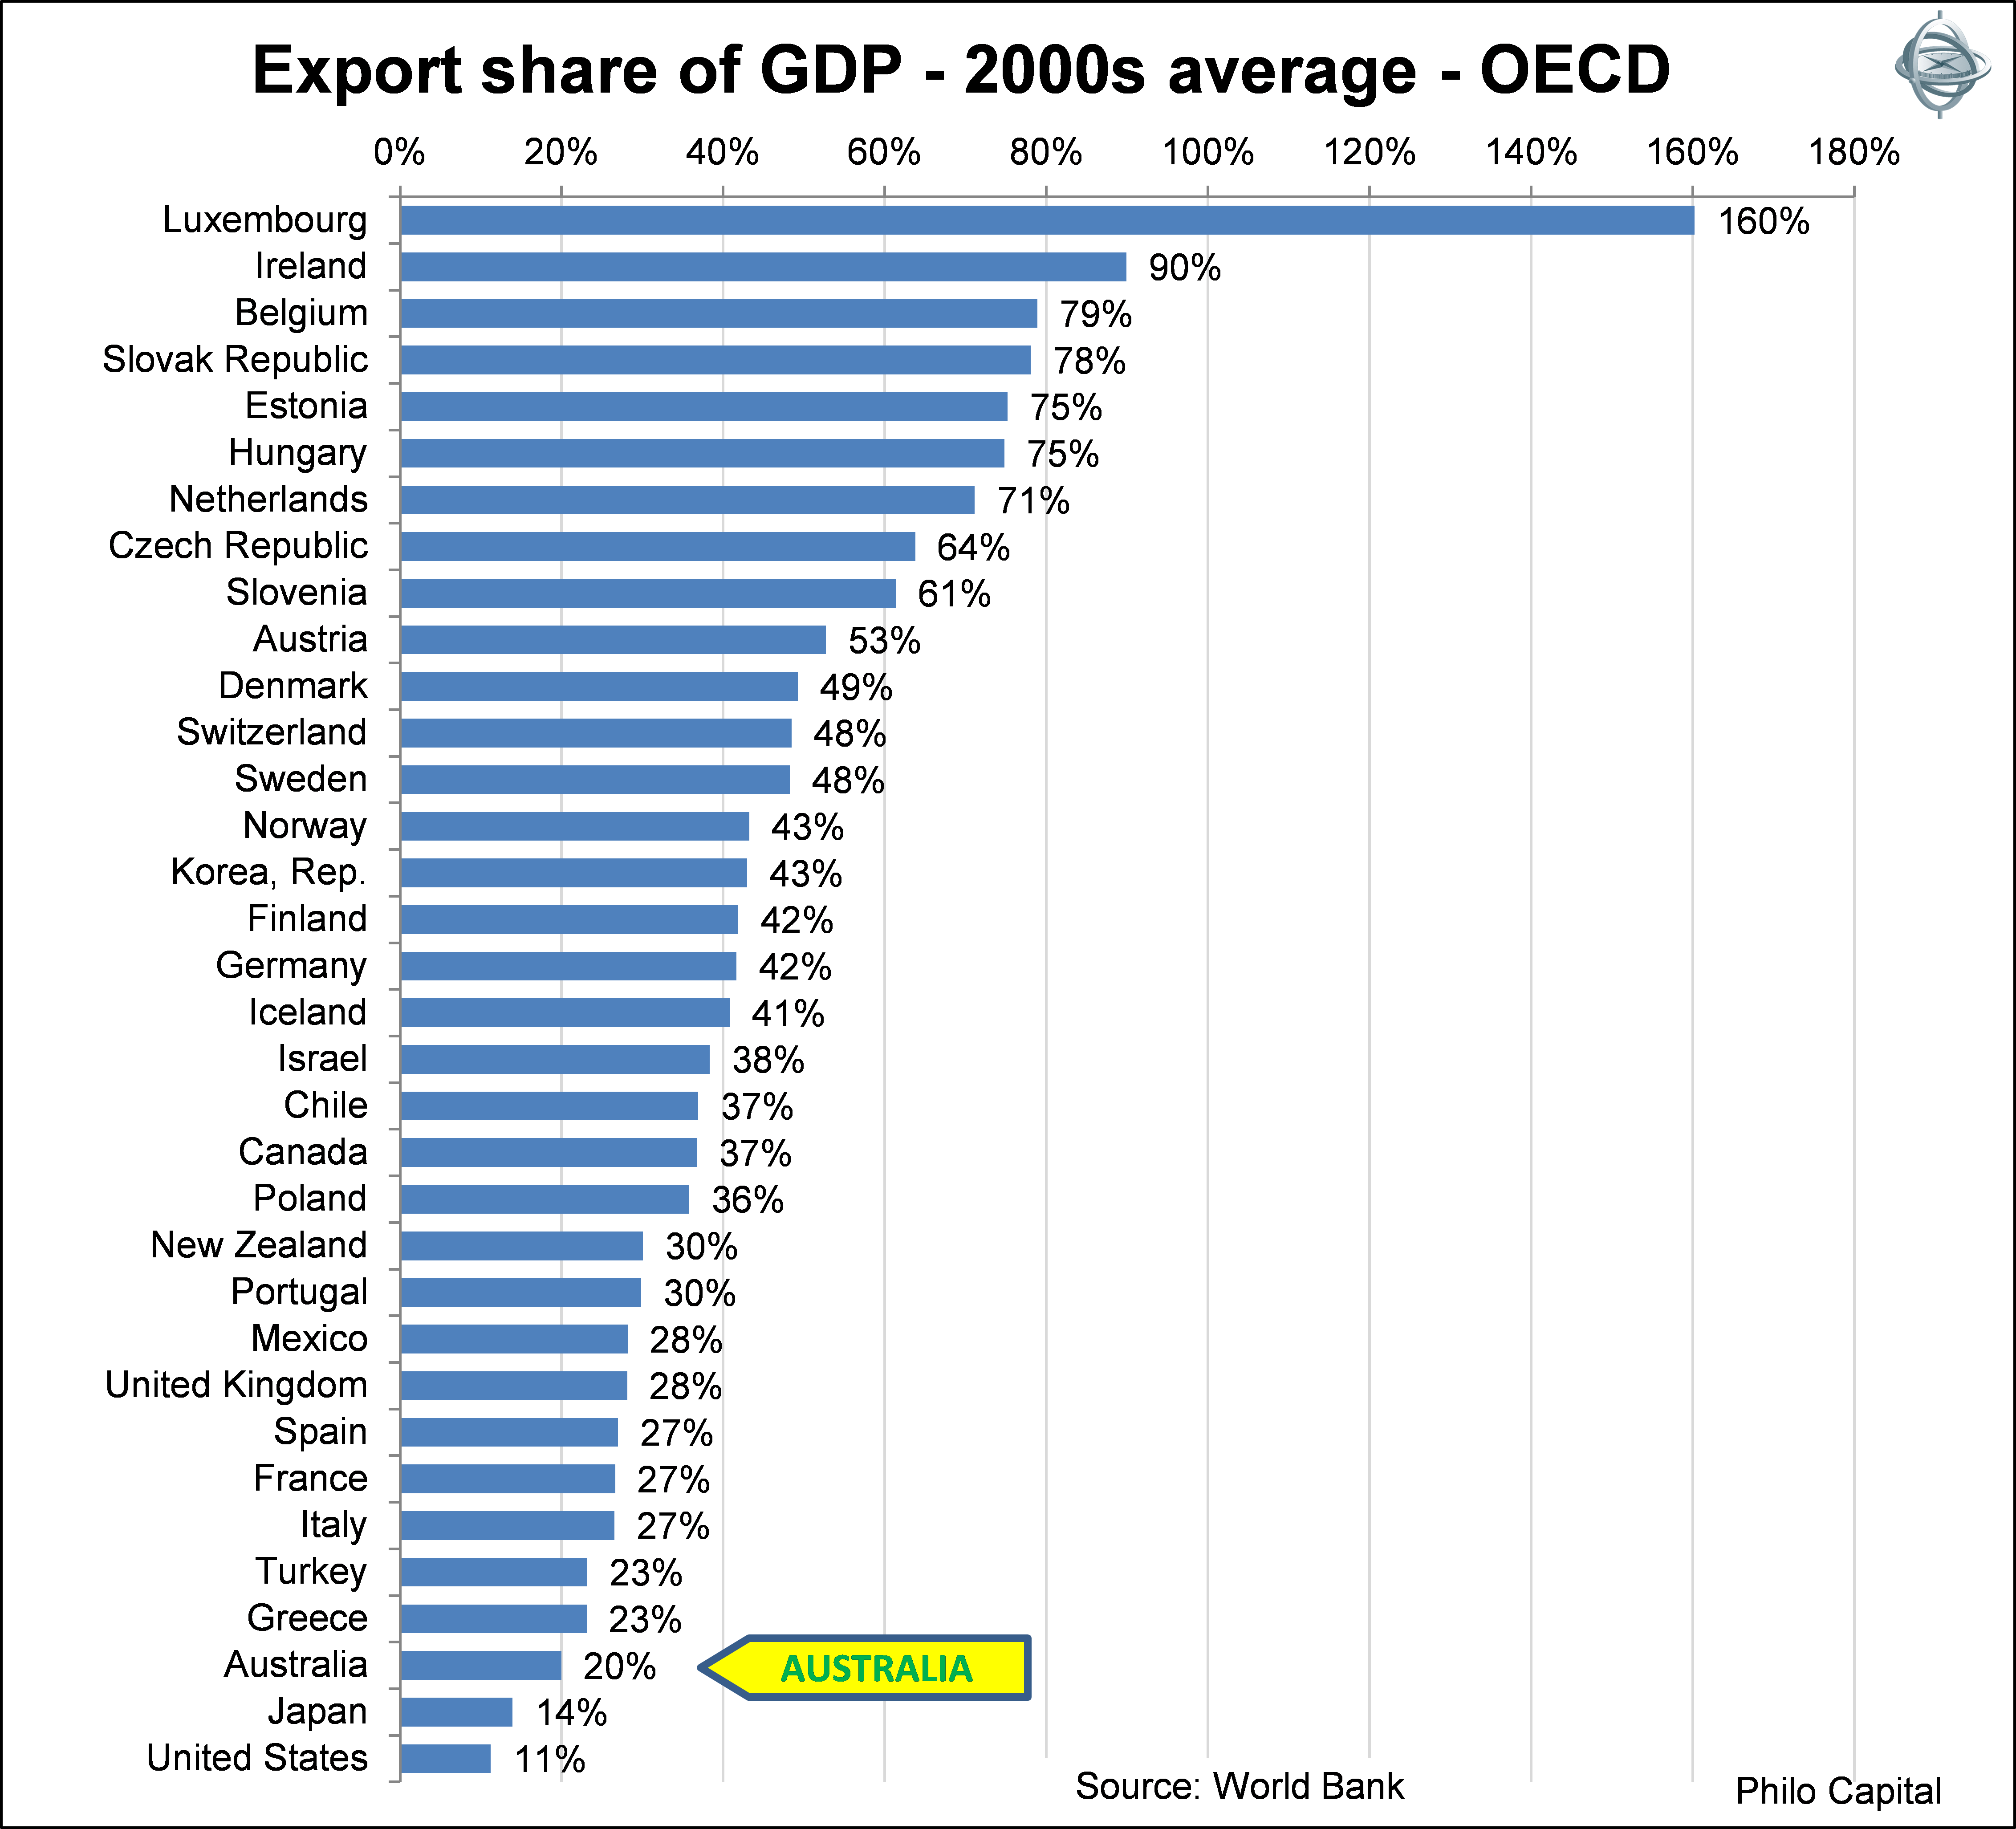
Even New Zealand beats us as an exporting nation by a big margin, and it doesn’t have anything like the abundance of natural resources we have.  Even Greece exports more than we do!

The US and Japan have very low reliance on exports as a share of their national incomes. All the currency devaluations they can muster (and they are trying very hard) to boost exports will hardly make a dent on their overall economies because exports play such a minor role in them. Ask any American what America exports and to whom they export, and you will get blank stares. Exports don’t matter to Americans.

Ask the average Australian the same question and they will rattle on endlessly about China, iron ore, coal and perhaps even our agricultural exports, as being vitally important to the very survival of Australia’s existence as a nation. For some reason, the Australian media have blown the importance of exports to Australia out of all proportion to the point where it has no bearing on reality.

Exports mean even less to Australia’s overall economy than in the other non-exporters because our main export industries employ so few people. We dig up rocks and load them onto the nearest ship, wait around while other people in other countries make useful things out of them, then buy those useful things back at thousands of per cent mark-up, and pay for them with money borrowed from foreigners because we haven’t exported enough to pay for our imports.

That’s hardly a long term sustainable plan, but we’ve been doing it for over 200 years. Not even Australia’s proximity to growth markets has helped.

One may say that the great exporting countries like Denmark, Belgium, Netherlands, Hungary, Sweden, Norway, etc should have a natural advantage by being very close to the big export markets of Europe, but there are two great disadvantages with this. The first is that they must compete with the big industrial powerhouses like Germany and Austria which, thanks to the Euro system, have artificially low currencies in their favour. The second disadvantage is that Europe is the slowest growing region on the planet. Around 70% of the exports of European countries go to other European countries, but the whole of Europe is mired in recession and has suffered relatively slow growth for the past decade even before the GFC hit.

In contrast, only 10% of Australia’s exports go to Europe but 70% of our exports go to Asia - the fastest growing region with the lowest unemployment levels and greatest demand growth in the world. More than half of all humans on the planet live in Asia, and they account for 70-80% of the total global growth in demand and wealth.

And we have plenty of stuff Asians want, including billions of tons of rocks they use to make useful things out of, thousands of miles of pristine beaches they love to visit, millions of acres of farmland that produce food they like to eat, and dozens of funny-looking animals they love to photograph. We didn’t create or invent any of this stuff - the rocks, beaches, land and animals were all here when we got here. All we did was trip over them.

The so-called ‘tyranny of distance’ from export markets is only a problem if we export bulky goods like rocks or food. Likewise, tourism and education require people to travel here. Other countries aren’t blessed with our rocks, or beaches, or land, or our funny-looking animals, so they have to use their brains instead. In the post-industrial knowledge economy, knowledge and ideas can be transmitted around the world in fractions of a second, so physical distance from markets is irrelevant for real high value, high tech exporters.

The reality is that Australia has never been a great exporter at any time in its history. Even in the 1850s gold rush, exports did not reach 50% of GDP (which dozens of countries exceed and have done for many years). Australia’s exports have only ever been near 30% of GDP a couple of times, and only for very brief periods.

The following chart shows Australia’s exports as a share of GDP since 1825 and indicates all of our export booms.
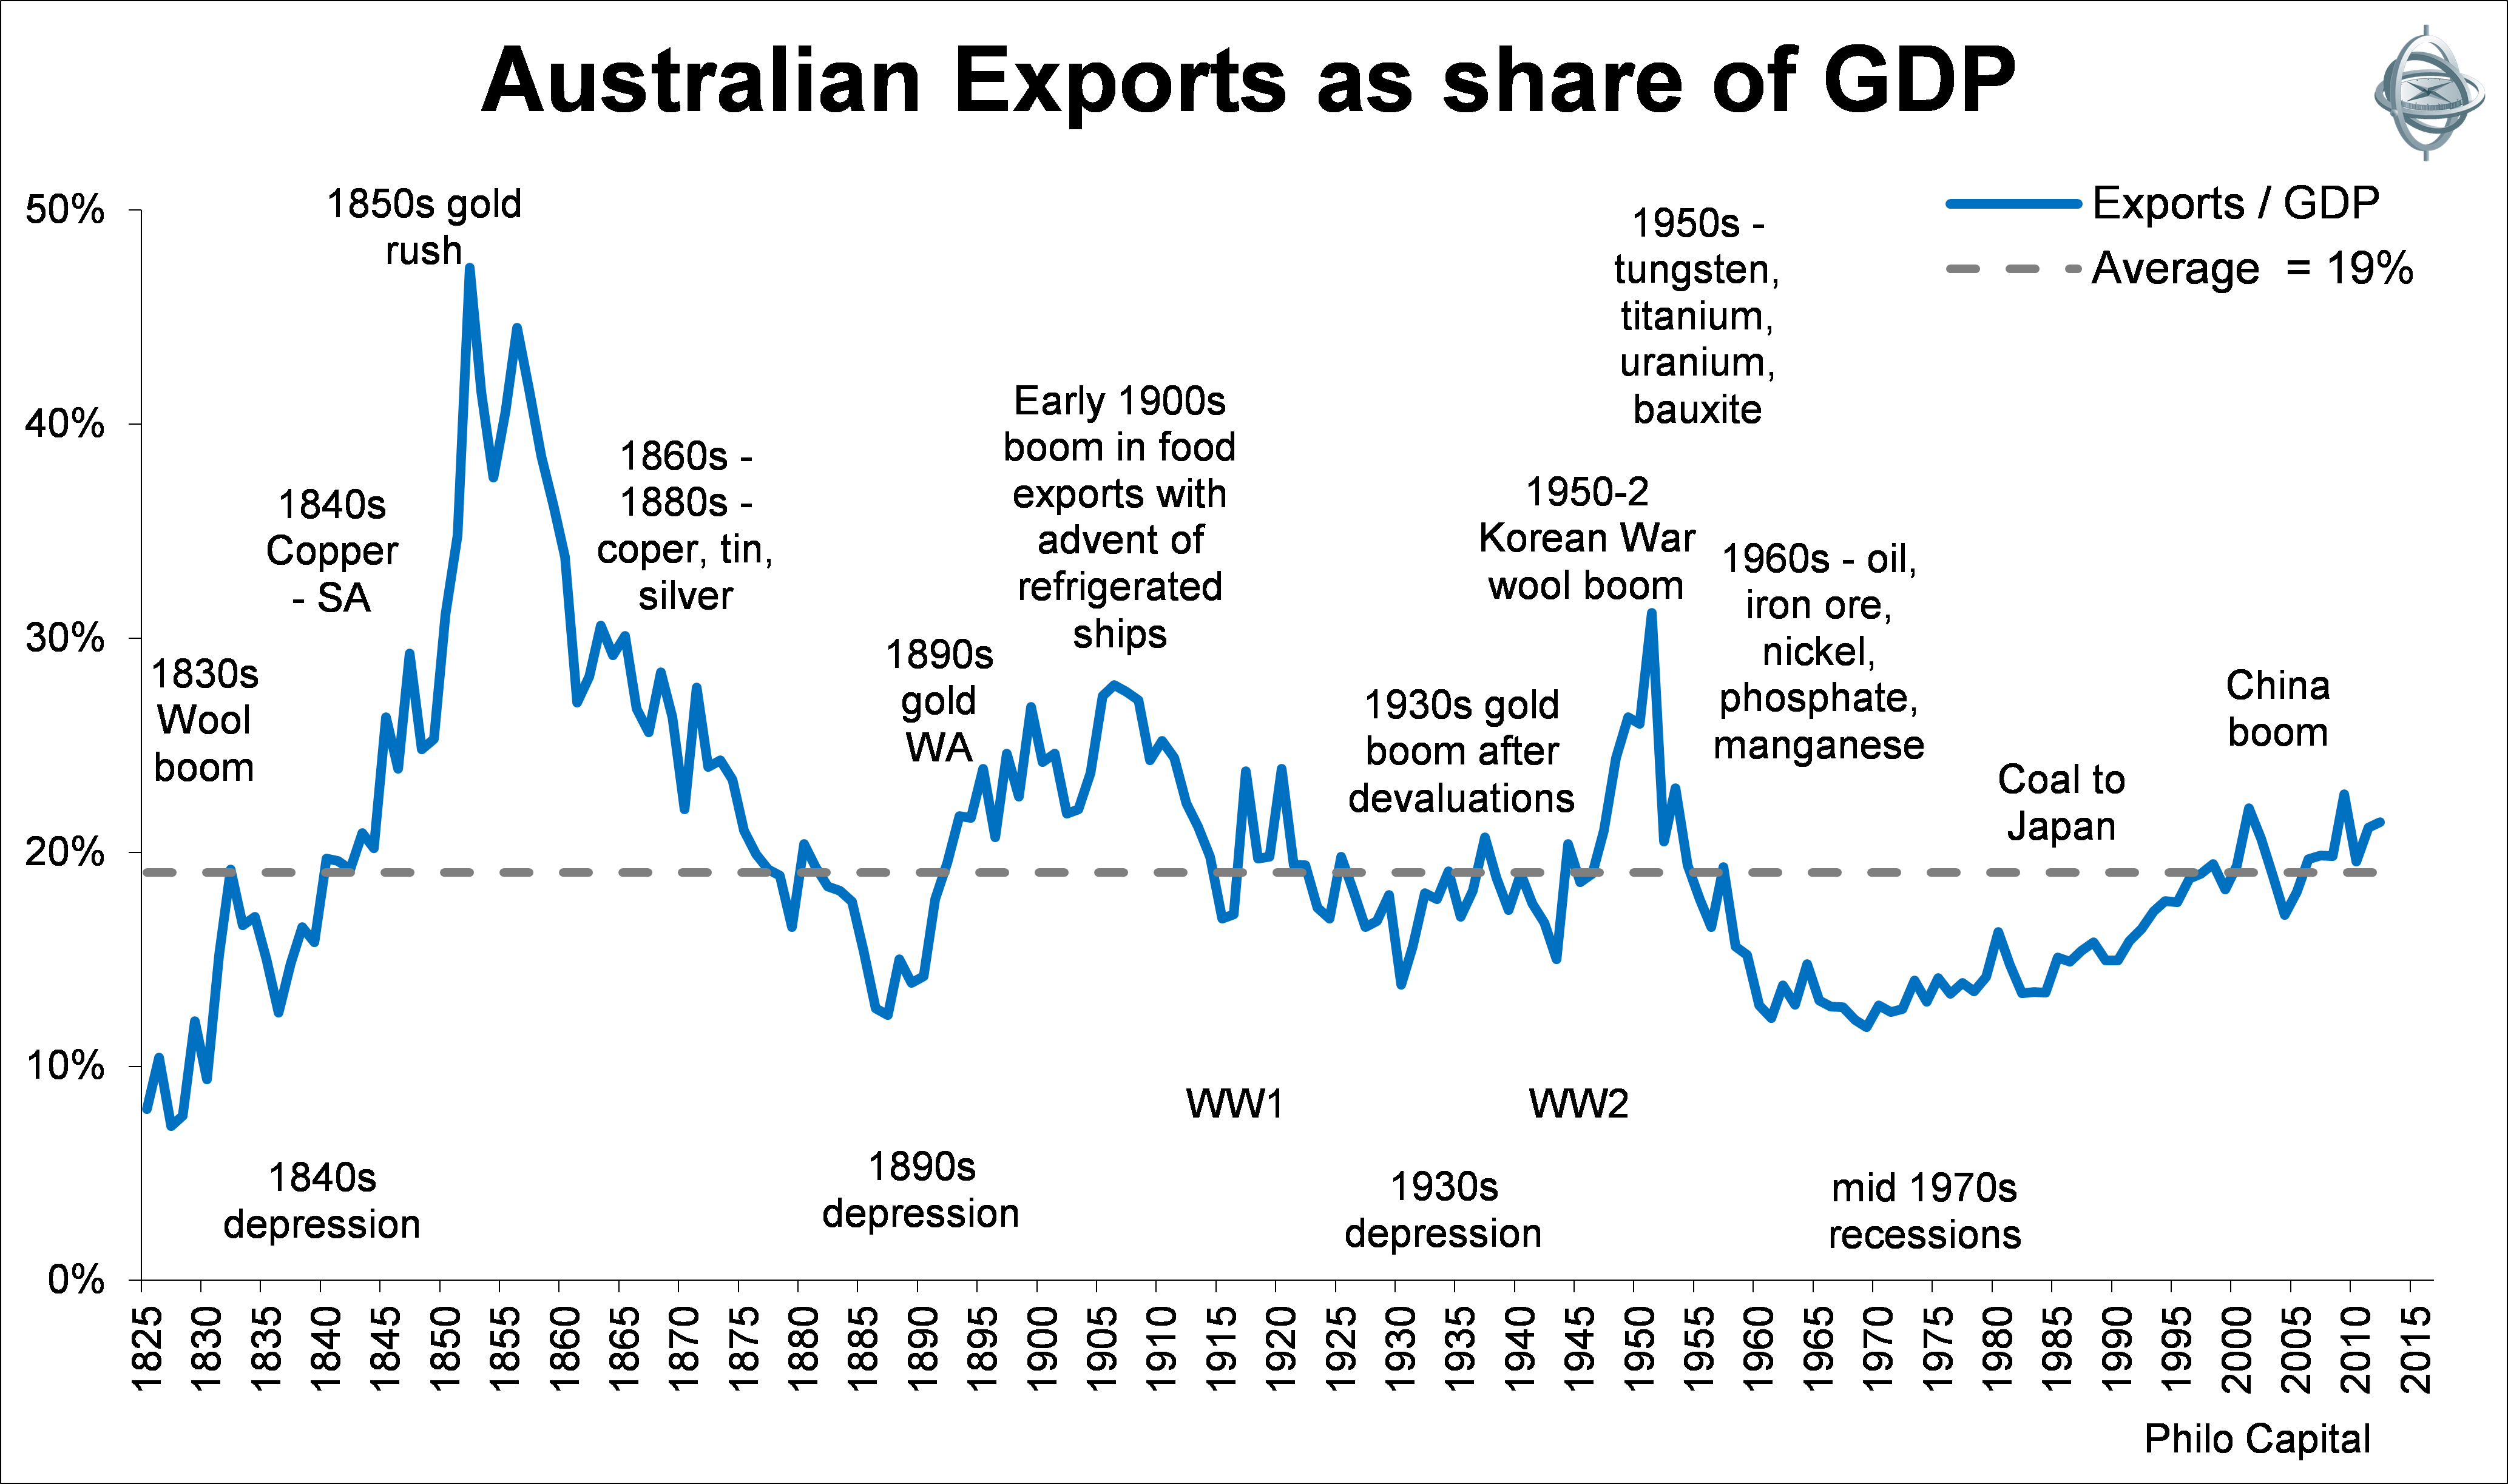
The so-called China export boom just lifted exports as a share of national income back to its (very low) long term average following the great export slump of the 1970s and 1980s. In fact the only times in our history when we were less reliant on exports than we are today was in the 1840s depression, the 1890s depression, the 1930s depression and the 1970s recessions.

Of course, a country doesn’t need to export at all. Its citizens can quite happily make and consume their own goods internally, as hunting and gathering societies did thousands of years ago. However, if we want to buy imports from other countries, we need foreign exchange, and we can only get foreign exchange by exporting.

Everything we do every day relies heavily on imports: the sheets on our beds when we get up in the morning, the clothes we wear, the furniture we sit on, the electronic gadgets we communicate with, the household appliances we use, the books we read, the TVs we watch, the cars we drive, and much of the food we eat. In fact most of what we see around us in our offices or our homes is imported or relies on imported machinery to produce. Just about the only thing we don’t import is the water we drink and the air we breathe.

We are addicted to imports and we have always had a chronic current account deficit problem. (The current account is essentially revenue from exports minus the cost of imports and net interest paid on foreign debt). We haven’t had a current account surplus since 1973, and before that one-off freak year, back in the Korean War boom in the early 1950s.

The problem for investors is that every couple of decades or so we have a mining ‘boom’, and for a short while mining companies dominate the stock markets. But the booms soon fade when supply catches up to and overtakes demand, substitutes are found, and prices fall. The excitement goes into hibernation for a couple of decades until the next ‘boom’.

Australia does have some world class companies that don’t rely on rocks but actually use their brains to compete and win on the world stage (such as CSL, News Corp, Orica, Amcor, Computershare, ALS, Ansell, Ainsworth). These companies are very few and far between, and because they are so rare they tend to be overpriced much of the time. But every so often their share prices fall to a point at which they become great value to buy.

Our local stock market is still littered with big, cosseted oligopolies that dominate virtually every domestic market segment - including banking, insurance, retailing, food, telecoms, gambling, gas, electricity, transport, airlines, and just about every other domestic industry in which listed companies operate. They are protected from real competition by the same ‘tyranny of distance’ and ‘high dollar’ they complain about.

Let us hope that our companies stop their endless bleating about the dollar and the distance, and get on with competing and winning in the knowledge economy where there are no barriers or distances or other excuses for a lack of vision.


Ashley Owen is Joint CEO at Philo Capital Advisers.


  •   20 June 2013
  • 4
  •      
  •   
4 Comments
money maven
June 21, 2013

Great article and some interesting stats. However, when it comes to GDP growth, then the marginal dollar (or growth) is the important metric. Your point about the recent rise in exports from depressed lows is the important point in this article when answering your question. Did we have a resources boom? Absolutely. Growth in that sector was huge and as a result, GDP growth has been good.

ashley owen
July 03, 2013

hi money maven,
yes, I agree. Relative to the past 50 years, it has been almost half a boom. But it doesn't deserve to be called real export boom unless and until it actually generates a current account surplus - ie when exports actually generate more revenue than the cost of imports and the interest on foreign debt borrowed to pay for imports!
cheers
ashley

Sonia Main
June 24, 2013

Ashley, can you explain why this statement is this true? "However, if we want to buy imports from other countries we need foreign exchange and we can only get foreign exchange by exporting." Can't we get foreign exchange by borrowing other currencies, or even printing AUD and selling it?

Ashley
June 24, 2013

A country can print as much paper as it likes but foreigners will pay less for it (ie currency will depreciate). But even then they will only buy AUD if they want to use it to buy things that are sold and priced in AUD – ie Australian stuff.

Money printing is Plan A for the US, UK, Japan, Switzerland, etc. Japan’s money printing is finally starting to work after 20 years of trying. The high gold price since the GFC is caused by people fearing/hoping all this money printing will lead to currency devaluation (which is the same as inflation). But the USD will be stronger, not weaker as its economy improves.

The money printing has not created inflation (too much spare capacity in the world for that, and since all the major countries are doing it, it’s a zero sum game – all currencies can’t devalue against each other at the same time. But at least it has prevented deflation – which is far more damaging than inflation.

We can only borrow in other currencies if we sell AUD to pay for it – so we need to find a buyer for our AUD in order to sell it to them.

Ultimately paper currencies are only worth what foreigners think they can buy with it – either they have to buy Australian stuff with it, or find a bigger fool somewhere else in the world to take the AUDs off their hands.

That’s how all societies develop from closed societies and start to trade. Think about Africans societies in the 15th century (or aboriginals in the 19th). In order to buy/import western goods (guns, alcohol, clothes, etc) they had to exchange something that westerners saw of value to them. They can’t just rip bark off the trees and stamp a number on it (ie create paper money) and pretend it has value that foreigners will pay for.

Societies that stick to non-value-added raw materials like bananas end up as banana republics – like Keating’s warning on 14th May 1986. In the 1960s to the early 1990s monetary policy in Australia was dominated by the current account and ways to control it. Even in the high inflation 1970s and 1980s, it was the current account that dictated policy, more so than inflation and unemployment.


Leave a Comment:

RELATED ARTICLES

Australia’s other boom exports

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.