Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 392

Win some, lose some: Buffett's 2020 scorecard

In a tough year for most investors, even Warren Buffett had a mixed year by his standards. The share price of his Berkshire Hathaway (BRK.B) investment company inched forward by just 2.5%, lagging major US benchmarks like the S&P 500.

Top holding Apple (AAPL) had a stellar year and an investment in data IPO Snowflake (SNOW) proved an immediate hit. But there were a number of misses too, with investments in US banks and financial services proving costly.

Let's take a closer look at his portfolio:

What worked

We covered the Sage of Omaha from a range of angles last year: Morningstar columnist John Rekenthaler analysed Buffett’s predictive powers, in December we dug into Berkshire Hathaway’s portfolio and in June Susan Dziubinski picked out three potential buys from the portfolio following the spring 2020 crash.

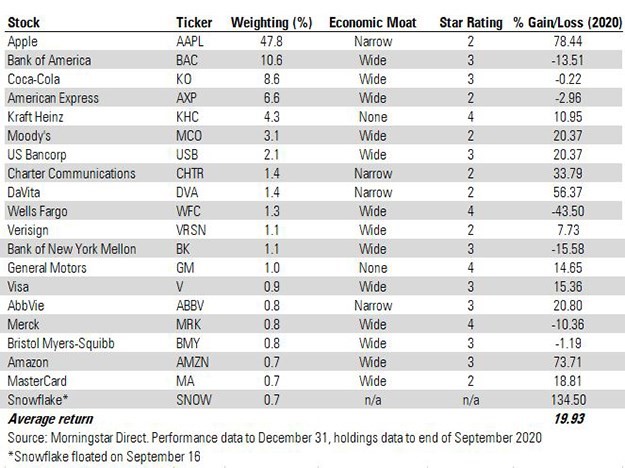
Looking in-depth at the portfolio, there were some strong performances from the likes of Apple and Amazon (AMZN), whose shares were 70% higher at the end of the year. But the standout performer in 2020 was new holding Snowflake, which floated in September at $120 and closed the year 134% higher at $281. The investment was particularly notable as value investor Buffett typically rejects the 'hooplah' associated with IPOs. Indeed, the last time he bought a newly listed company was Ford motor company in 1956.

So what were the biggest changes to the Buffett investment portfolio in 2020?

Healthcare was one of the boom areas of 2020 so it was no surprise to see an increased weighting to these stocks last year. In the third quarter of 2020, the portfolio added to positions in Abbvie (ABBV), Merck (MRK) and Bristol Myers Squibb (BMY) - the trio now accounts for 2.4% of the portfolio's assets between them.

Of these, only Abbvie posted a positive return for the year, up 20%. Merck, meanwhile, is one of four companies in the portfolio rated as undervalued by Morningstar analysts with a 4-star rating (the others are food giant Kraft Heinz (KHC), bank Wells Fargo (WFC), which fell nearly 45% last year, and US car firm General Motors (GM)). The position in Wells Fargo was reduced in 2020, as were stakes in Bank of New York Mellon, Visa, Mastercard and US Bancorp.

Merck is also one of two companies in the portfolio's top 20 positions to have a wide economic moat, an important concept gauging competitive advantage for Warren Buffett and Morningstar. General Motors and Kraft Heinz are the only stocks in the list with no economic moat, while Snowflake does not yet have a Morningstar rating.
The trouble with Berkshire

How do you measure Warren Buffett’s performance? A conventional investment portfolio with 50% exposure to Apple would have done very well in 2020. The average share price gain for the biggest holdings in the portfolio is just below 20% (see table), which beats the S&P 500’s gain of 15% for last year.

But things aren’t that simple: Berkshire Hathaway has many facets and while the investment portfolio gains investor attention because of Buffett’s status, it’s also part of a much wider empire.

Berkshire Hathaway Energy and its railway subsidiary BNSF, for example, were hit hard in 2020. The manufacturing, services and retail (MSR) arm, with holdings in metalworking companies and aircraft parts suppliers, has also been damaged by the pandemic. And exposure to insurance has weighed on performance, with much higher payouts last year in the industry as a whole.

But Berkshire Hathaway B shares are now undervalued, according to Morningstar analysts, and retains its wide economic moat. The company could come under pressure to return more of its cash mountain to shareholders this year after a lacklustre 2020 in share price terms.

Berkshire is not easily compared with an index or a conventional investment fund. While the Berkshire Hathaway share price barely moved the needle last year, Morningstar analyst Amy Arnott says the Buffett magic keeps retail shareholders loyal:

“The legions of investors who still count on it as a quasi-fund for their life savings likely aren’t complaining.” 

Now 90, Buffett has handed the running of his equity portfolio to former hedge fund managers Todd Combs and Ted Weschler, who run $30 billion between them. After the portfolio’s surprise (and highly lucrative) punt on Snowflake towards the end of last year, Berkshire investors could see further unexpected developments this year. And with value investing making a tentative comeback and the real economy recovering, these conditions could be more favourable to Buffett’s approach of buying unloved stocks.


James Gard is content editor for Morningstar.co.uk. This article is general information and does not consider the circumstances of any investor. Any Morningstar ratings/recommendations contained in this report are based on the full research report available from Morningstar.

Register for a free trial of Morningstar Premium on the link below, including the portfolio management service, Sharesight.


Try Morningstar Premium for free


  •   27 January 2021
  • 1
  •      
  •   

RELATED ARTICLES

Three key takeaways from Buffett's annual letter

Is your portfolio too heavy on technology stocks?

Warren Buffett changes his mind at age 93

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Will you run out of money in retirement?

Fear of running out has become a defining retirement anxiety. Why do some retirees die with substantial wealth while others deplete their nest egg? Evidence suggests the answer is more complicated than we think. 

The investment that sidesteps the new tax traps

Tax rules have changed, but many investors are still using yesterday’s strategies. Insurance bonds may offer advantages for those seeking greater control, tax efficiency and certainty about their wealth.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Investment strategies

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Economy

Population growth masks Australia’s productivity problem

For years, investors have benefited from a seemingly reliable growth story. But recent national accounts raise uncomfortable questions about what has really been driving Australia’s economy and whether that can continue unchecked.

Investment strategies

Why tomorrow’s winners may not be today’s index leaders

The stocks that built retirement balances over the past decade now dominate many portfolios. The new challenge is whether these companies can continue meeting the increasingly high expectations embedded in today's share prices.

Investing

What earnings surprises reveal about future returns

Sometimes the most important information in an earnings result isn't the number itself. It's the possibility that the market's assumptions have been fundamentally wrong and future earnings may look very different.

SMSF strategies

Individual SMSF Trusteeship directly liable for ATO fines

A rarely discussed detail buried in SMSF structures could dramatically change who wears the cost when something goes wrong. With penalties rising, a decision many dismissed as administrative may deserve a second look.

Investment strategies

The currency bet you didn’t know you made

Buying global shares means making two bets: on the companies and on the Australian dollar. Most investors consciously choose only the first. Last financial year, the second bet cost 8.5% in returns for many investors.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.