Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 317

Advisers must step up and articulate their value

Market experts have been warning investors to brace for the end of the longest bull run in history. This should be a time when many Australians are turning to financial advisers as they look to preserve their wealth and financial security. But the perception of the adviser value proposition is at record lows and many financial advisers are also struggling to remain positive at this time of need for their clients.

In recognising the impact an adviser can make to an investor’s overall financial well-being, Russell Investments has quantified the contribution professional advice can add to an investor’s portfolio over their lifetime. Our aim is to aid advisers with a repeatable and memorable framework to help them have open and frank conversations about their value proposition.

Our second annual Value of an Adviser Report estimates an investor gains a minimum of 4.4% p.a. through an advice partnership, which can make a massive difference to the financial security of the average Australian investor over their lifetime.

Building blocks that comprise an adviser’s real value

Here, we take a holistic look at the building blocks that comprise an adviser’s real value proposition throughout a client’s investing journey.
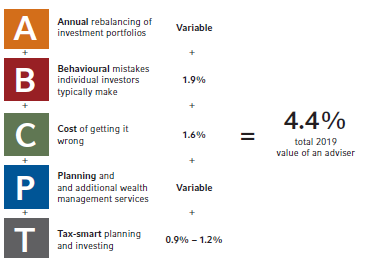
A is for Annual Rebalancing = variable % p.a.

Left to their own devices, individuals tend to let portfolios drift and, as a result, portfolios can look vastly different from their initial state over time. The potential result of an un-rebalanced portfolio is demonstrated in the chart below. A hypothetical balanced index portfolio that has not been rebalanced would look more like a growth portfolio and expose the investor to risks not initially agreed to.

Disciplined rebalancing is crucial to avoiding unnecessary risk exposure when investing. For example, if a certain asset class is performing strongly it can be tempting to hold an overweight position in that class. If the market corrects, investors may find themselves with too much invested in a volatile asset class.

Rebalancing is a key positive value add of advice, but we consider it variable as it depends on markets in the measurement period.

B is for Behavioural Mistakes = 1.9% p.a.

Despite strong evidence that portfolio value increases over time, investors can still feel compelled to react to short-term market volatility, serving to undermine their long-term objectives.

Advisers can play a critical role in helping clients adhere to their long-term financial plan and make better investment decisions by helping them skirt around some 200 identified behavioural tendencies that impact investing including Loss Aversion, Overconfidence, Familiarity and Herding.

If we just focus on herding, we look at the return if an investor bought and held an index. We then look at the flows into funds and ETFs through the market cycle. As markets rise, invariably, people put money in and buy high. As markets fall, investors lock that loss in by selling their funds and ETFs.

Our statistics show, the average fund investor’s inclination to chase past performance came at a cost of 1.9% p.a. from 1984-2018. This cost may well have been avoided with professional guidance.

C is for the Cost of Getting It Wrong = 1.6.% p.a.

There can be a clear disconnect between an investor’s risk profile and return expectations. In fact, research by Deloitte Access Economics found younger investors were more risk averse than their older counterparts. The research found around 81% of investors under 35 years old said they were seeking guaranteed or stable returns, compared to 41% of those aged over 55. On another note, 21% of the most risk-averse investors expected returns over 10%.

Looking below at average returns of Australian equity and bond portfolios over a 20-year period, an investor with 70% of their portfolio in growth assets and 30% in defensive would earn an average annual return of 10.9% over the 20-year period. Meanwhile, an investor with 30% growth assets and 70% defensive would achieve annualised returns of 9.3% over the same period.

In this scenario, an investor under 35 invested conservatively instead of in the growth option would have forgone an average of 1.6% return every year for 20 years. On $100,000 invested, that’s a significant difference of almost $200,000 to the final return.

Beyond investment-only advice

P is for Planning = variable % p.a.

Further to building and regularly updating bespoke financial plans and conducting regulatory reviews, financial advisers offer ancillary services including tax and estate planning, investment and cash flow analysis, retirement income planning and assistance with annual tax return preparation.

Like annual rebalancing, the quantification of this value add is variable as it depends on an adviser’s practice and services offered.

T is for Tax-smart investing = 0.9% – 1.2% p.a.

Lastly, quality financial advisers have the technical expertise to help clients make the most of their tax circumstances as well as avoid any unexpected surprises at tax time as regulatory changes occur.

We believe that the value of an adviser for tax-smart investing is at least the sum of tax effective investment strategies and salary sacrifice pre and post superannuation contributions (depending on account balances).

Therefore, we estimate the value of an adviser to range between 0.9%-1.2%p.a. depending on whether the client is in an accumulation or transition to retirement phase.

The bottom line

Russell Investments believes the importance of articulating the tangible benefits financial advice provides investors cannot be understated. From the knowledge and expertise required to help clients build personalised portfolios, to the support they provide when market conditions change, and the range of additional wealth management services they offer, such as tax and estate planning.

While we are empowering adviser conversation with clients, we are also providing investors with a framework of what financial advice looks like.

Looking forward, we believe advisers practicing a full value proposition will thrive in the current challenging environment.


Jodie Hampshire is Managing Director, Australia for Russell Investments. Based in Sydney, Jodie has overall responsibility for Russell Investment’s Australian business across Institutional and Advisor and Intermediaries Solutions. This article is general information and does not consider the circumstances of any individual.


  •   31 July 2019
  • 7
  •      
  •   
7 Comments
Tony Smith
August 01, 2019

the 4+% increase by using an adviser is nothing compared to the risk of losing a LOT from bad financial advice.

Steven
August 04, 2019

Yeah, because no one ever lost “a LOT” from getting no advice.

Michael2
September 29, 2019

People like Bernie Maddox don't help the situation, he even stole payouts from injuries and old people's life savings

Stephen
August 01, 2019

This is a fantastic article, I often have difficulty articulating the value of my advice, it’s just not a strength of mine. I will definitely be sending this article to my clients.

Frank
August 04, 2019

Wow, 4.4% from financial advice when the long bond is 1.3% and markets are at elevated levels. I wish.

SMSF Trustee
August 04, 2019

Frank, you didn’t read the detail did you. Almost half of that is the author’s estimate of how much a good adviser will save someone who would otherwise make dumb mistakes, like panicking out of the market last December and watching it rally all through 2019. Or, to pick up on your point, to dissuade someone from throwing more money at the stock market now at ‘elevated levels’. So, the argument being made is that the typical client will miss tax opportunities and make mistakes that reduce their portfolio by at least 4.4% compared with what it could otherwise have been, so that the return on that 4.4% adviser fee is positive. It’s harder for advisers to make their value proposition to people who have a bit of an idea what they’re doing and a bit of self-discipline. (I believe I’m in that category, and so did my adviser when we started out on our SMSF journey. I take it you think you’re also more sophisticated.) In those cases the good advisers pitch a sensible fixed dollar fee to cover the agreed scope of works. In my case, that started at the equivalent of about 0.15% and reduced from there as my fund grew over the last few years.

Carikku de Roo
August 12, 2019

Agree 100% about good advisers charging a fixed dollar fee, which diminishes as a percent of your funds as they grow This is an often-overlooked advantage of independent advisers – most people think that independence just means not affiliated with product manufacturers but actually it is the lack of asset-based fees that usually impact portfolios the most in the long term.


Leave a Comment:

RELATED ARTICLES

The value of financial advice amid rise of retail investors

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.