Costco is not just a place where you can buy a 2kg cheese wheel and a three-person sauna in the same transaction. The retailer is also in the recession prediction business.
When customers started switching from more expensive beef to cheaper proteins, it was a sign household budgets were under pressure. Comments made by Costco’s former chief financial officer Richard Galanti during a 2023 earnings call resurfaced this year. In 2023 Galanti noted that similar shifts had occurred around previous economic slowdowns. This trend is re-emerging as more consumers turn to poultry to meet tighter household budgets.
Every economic slowdown seems to produce a new recession indicator.
More traditionally minded economists point to inverted yield curves, rising unemployment or widening credit spreads. Their new age brethren turn to consumer trends. Some have loose connections to the economic climate and are household perceptions of conditions. Cheaper meat makes sense as households try to cut back on spending. Dips in restaurant bookings are consistent with discretionary income evaporating.
Other popular measures have much looser connections – shortening of women’s skirts, or the Lipstick Index which measures increases in cosmetic sales.
The Lipstick Index was popularised by Leonard Lauder, the former chairman of Estée Lauder, after he observed increased lipstick sales during periods of economic uncertainty. The underlying idea is not particularly complicated: when people cannot afford major luxuries, they may still want a small treat.
There is a temptation to treat every change in consumer behaviour as a warning that a recession is coming. It isn’t surprising that people worry about how a slower economic environment will impact our quality of life. It is natural to look for a signal one is coming.
General indicators of recession
Of the traditional indicators, the yield curve is one of the best known.
Normally, investors demand a higher interest rate to lend money for longer periods. When short-term interest rates rise above long-term rates, the yield curve becomes inverted. Historically, this has often preceded US recessions.
Yield Curves: USA and Australia
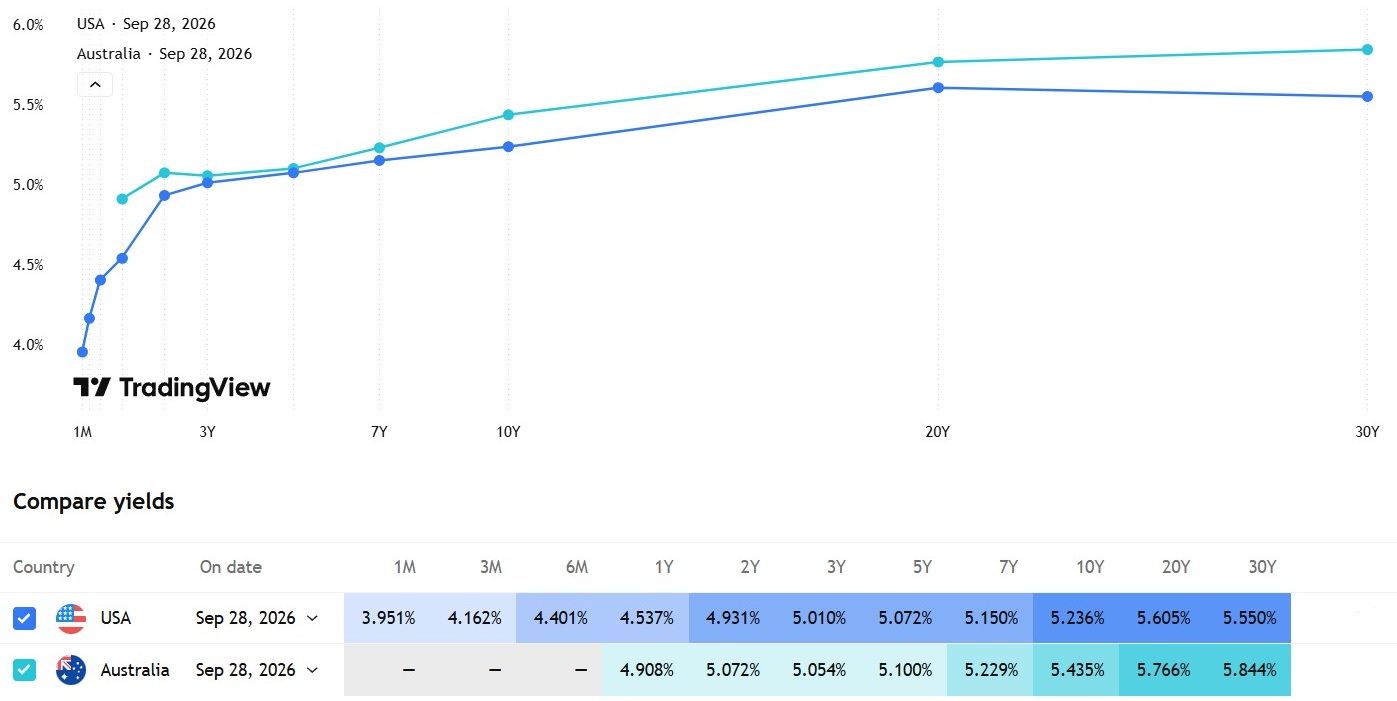
Source: TradingView. As of 28 September 2026
Currently neither the Australian nor US yield curve are inverted.
But the yield curve being the ‘right-way up’ doesn’t mean a recession won’t occur. Just as an inverted yield curve shouldn’t be treated as a recession countdown clock. It can invert well before an economic contraction and there are numerous instances when a recession didn’t follow.
Employment is another indicator. The Sahm Rule, developed by economist Claudia Sahm, looks for a 0.5 percentage-point increase in the three-month average unemployment rate relative to its low over the previous 12 months. It is designed to identify when a recession is already beginning rather than predict one in advance.
This is an important distinction as a country needs to experience two consecutive quarters of negative economic growth for a recession to be declared. You can be in a recession for six months before knowing it.
The Reserve Bank of Australia prefers to use a 0.75% trigger for Australia. The latest data shows the July three-month average for unemployment is 4.43%. The lowest unemployment rate over the preceding 12 months was 4.1%. Australia has not breached the Sahm rule by US or Australian standards.
If the lowest unemployment rate stays at 4.1%, the rate will have to reach 4.85% to trigger the Australian version of the Sahm Rule and be acknowledged by the RBA.
These indicators are useful for economists because they are connected directly to the mechanisms through which recessions occur. That is often a chain reaction – businesses stop hiring, consumers reduce spending, credit becomes more expensive and companies cut investment. This is a situation where the economy is weakening in ways that matter for corporate profits.
Australia is already showing some signs of pressure
There are legitimate reasons for Australian investors to pay attention to the economic outlook.
Consumer sentiment remains weak, while higher interest rates and elevated living costs have put pressure on household budgets. The Reserve Bank’s August outlook expects Australian economic growth to slow during 2026, with higher inflation, tighter monetary policy and softer housing conditions weighing on activity. The central bank also expects unemployment to rise gradually as labour demand eases.
The labour market is also showing some signs of cooling. The unemployment rate rose to 4.5% in July, from 4.4% in June, while underemployment remained at 6.4%.
Data from Owen Analytics shows that the rate of company insolvencies is at its highest rate in 40 years. Using ASIC data, Owen estimates that insolvencies in recent years have been well above the low levels during the pandemic and that the 2024-2025 financial year was particularly high.
The ongoing Bathla crisis has some channeling Michael Burry – predicting this is the first domino to fall in an inevitable financial crisis. The dangers of an opaque private credit investment industry have divided investors and market commentators. Some believe Bathla is the start of rising credit issues while others see the double-digit income as attractive given stable credit conditions.
The Reserve Bank addressed the issue back in March. Its Financial Stability Review said company insolvencies had stabilised around their longer-run average as a share of operating companies. It added that there were elevated rates in industries such as hospitality and construction. The RBA also noted that many recent insolvencies involved small companies with limited bank debt, so there weren’t broad-reaching implications for the economy. In other words, there are pockets of stress, but that is different from evidence of a broad financial system crisis.
These indicators have limitations for investors. They tell us something about what is happening in the economy - they do not tell us exactly what markets will do next or what we should do with our portfolios.
The danger of indicator shopping
Perhaps the biggest problem is indicator shopping. If investors look at enough data, they will eventually find something that looks worrying. A rise in insolvencies. A fall in consumer confidence. Weak restaurant bookings. A change in what people are buying at Costco. A yield curve signal. A labour-market rule. This can be a case of confirmation bias where an investor worried about the economy seeks out more signs that their thesis is correct.
We recently conducted a survey of Australian investors and their general sentiments towards the market. The most common answer was that they are feeling ‘cautious’. That feeling isn’t irrational. People experience the economy differently from the way it appears in a collection of national statistics. A household facing a large mortgage, higher insurance premiums, expensive groceries and rising fuel costs can feel that the economy is in trouble even if GDP is still growing.
This is one reason recession indicators can become so popular. Investors are trying to reconcile what the data says with what they are experiencing. We may not technically be in a recession, but many people feel like economic conditions have become significantly more difficult.
Sometimes even when several indicators are pointing in the same direction, it may be because many of these measures are related.
A weaker economy can simultaneously produce weaker consumer confidence, softer employment, lower spending and rising business failures. Counting each of these as an independent warning signal can make the evidence appear stronger than it actually is.
You don’t need to predict the recession
The lesson isn’t that investors should become better at predicting recessions and position their portfolios at the right time. It is that they should become better at building portfolios that are resilient in the face of economic slowdowns.
Lesson 1: Separate economic data from market predictions
A recession is an economic event. A bear market is a market event. They are often related, but they are not the same thing. Markets are forward looking. They can fall before a recession is officially recognised, and they can begin recovering while economic data still looks weak. An investor who waits for certainty about the economic outlook might find that markets have already moved on before they can re-position their portfolios.
Lesson 2: Understand and use economic data for the right decisions
A recession indicator is not a reason to sell. They can however help investors understand the environment in which companies are operating. Rising unemployment, falling demand and tighter financial conditions can affect corporate earnings, interest rates and valuations. This adds context to how companies and your portfolio are performing.
Ask the right questions.
Does your portfolio rely heavily on one economic outcome? Understand how diversified your portfolio really is and how it will behave in different market environments.
Do you have enough liquidity outside your investment portfolio? Consider your ability to self-insure through liquid assets to avoid selling at an inconvenient time.
Lesson 3: Be particularly careful with irreversible decisions
The danger of recession anxiety isn’t simply that investors become more cautious. It is that they make large, difficult-to-reverse changes to their portfolios based on a forecast that may turn out to be wrong.
Moving from shares to cash can feel prudent when the headlines are frightening. The difficult part is knowing when to reverse the decision. Missing a recovery can have a lasting impact on long-term returns because an investor needs to make two correct decisions - when to get out and when to get back in. It is hard enough to get one of those decisions right.
Final thoughts
Recessions are a normal part of economic life. So are periods of inflation, changing interest rates, falling consumer confidence and disappointing corporate earnings. Resist the temptation to believe that somewhere, buried among all the data, there is an indicator that will tell you exactly when the next recession is coming so you can avoid the pain.
Many investors are currently on high alert and remain cautious about the environment. Your job is to look beyond what is currently happening to focus on your long-term goals. Don’t let caution lead to irreversible decisions and instead build a system that can survive most economic environments.
Shani Jayamanne is Director, Investment Specialist, at Morningstar Australia.