Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 364

Common confusions with death benefit pensions

There are a number of issues regarding the payment of death benefits that are widely misunderstood. In this article, we review the types of accounts that can pay a death benefit as a pension, minimum pensions, rolling over death benefit pensions and tax treatment.

Death benefit pensions

A common misconception is that a death benefit can only be paid as a pension if the deceased was in pension phase. However, provided that the super fund rules allow, a death benefit may be paid as a lump sum, one or more pensions or a combination of both a lump sum and pension benefits. This ability applies regardless of whether the death benefit is being paid from an accumulation account, a non-reversionary pension or a reversionary pension.

Death benefits can only be paid as a pension to a death benefit dependant, including a spouse, a financial dependant, someone in an interdependency relationship or a child of the deceased. However, where the beneficiary is a child of the deceased, a pension may only be paid if the child:

  • is under age 18
  • is age 18 to 25 and financially dependent on the deceased
  • has a significant disability.

A child death benefit must be commuted by the time the child turns 25 unless the child is disabled.

Minimum pensions

If the deceased was in pension phase, the treatment of minimum pension payments varies depending on whether the pension was reversionary or non-reversionary.

If the deceased had a reversionary pension, then the minimum annual payment based on the deceased’s age must be paid during the year. At the next 1 July, the minimum payments will be recalculated based on the recipient’s age.

If the deceased had a non-reversionary pension, then there is no requirement to pay the minimum annual payment.

Rolling over

From 1 July 2017, a death benefit pension can be rolled over to another fund at any time. A death benefit pension always retains its identity as a death benefit. This is valuable because it means lump sum commutations from a death benefit pension are PAYG tax-free. However, death benefit pensions cannot be intermingled with other pensions and cannot be rolled back to accumulation phase.

The ability to rollover can be a valuable option in an SMSF where the surviving spouse may not wish to continue managing the SMSF on their own.

Taxation

All death benefit pensions are retirement phase pensions which means that the investment returns are not taxed.

The PAYG tax treatment of pension payments depends upon the age of the deceased and/or death benefit pension recipient and the tax components of the pension as outlined in the table below:
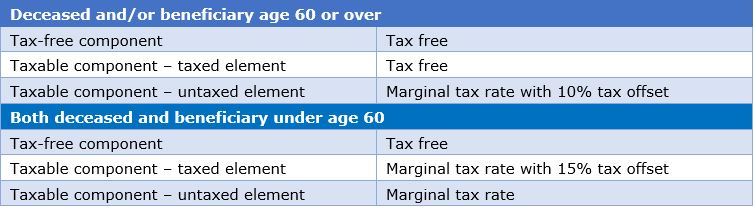
The taxable component – untaxed element will generally only arise from a constitutionally protected fund that is taxed differently to most funds.

Lump sum payments

Any lump sum commutations from death benefit pensions are PAYG tax free. Where both spouses are under 60, there may be advantages of taking the required minimum pension payment and using tax-free lump sum commutations to fund any additional lifestyle needs.

Case study

Brenda dies on her 50th birthday and has a benefit of $1,000,000 of which $10,000 is tax-free component.

If Brenda’s husband Barry who is also 50 were to take the death benefit as a pension and draw the minimum annual pension for 2020/21 of $20,000 (temporary minimum of 2%) his tax components would be as follows:
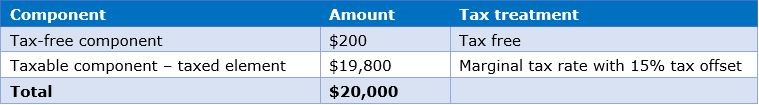
 

If this was Barry’s only income in 2020/21, he would not pay any tax on his pension income.

If, however, Barry needed $60,000 to live on he could take the additional $40,000 as a lump sum commutation PAYG tax free.

If he took the additional $40,000 as pension payments and this was his only income for 2020/21, he would pay tax (including Medicare levy) of approximately $1,941.

Assuming the death benefit pension was also $1,000,000 at 30 June 2021, if Barry was to draw the minimum annual pension for 2021/22 of $40,000 his tax components would be as follows:
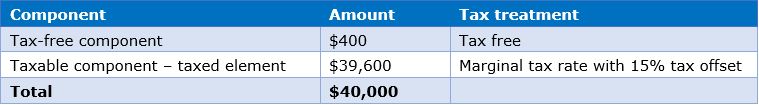
 

Assuming no changes in personal tax rates, if this was Barry’s only income in 2021/22, he would pay the Medicare levy of $792.

If however Barry needed $60,000 to live on he could take the additional $20,000 as a lump sum commutation PAYG tax free.

If he took the additional $20,000 as pension payments and this was his only income for 2021/22, he would pay tax (including Medicare levy) of approximately $1,941.

Conclusion

Being aware of common misunderstandings in relation to the payment of death benefit pensions can assist in estate planning matters. Understanding the value of professional advice during difficult times can also greatly assist individuals to understand their choices and the tax consequences that follow.


Julie Steed is Senior Technical Services Manager at Australian Executor Trustees. This article is in the nature of general information and does not consider the circumstances of any individual.


  •   30 June 2020
  • 3
  •      
  •   

RELATED ARTICLES

Division 296: the initial moves to make before the windows close

Meg on SMSFs: What do we think about reversionary pensions these days?

Meg on SMSFs: When the first member of a couple dies

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Latest Updates

Retirement

The retirement account that Australia should have

Our retirement system asks one account to do two very different jobs. A dedicated "rainy day" account separating income from emergency savings could deliver better outcomes and greater peace of mind for retirees.

Investing

What the US midterm results mean for investors

Democrats have regained control of Congress, changing the equation in Washington. Whether that proves positive for investors will depend less on the result itself and more on what happens next for growth and markets.

Taxation

Should the capital gains tax reward risk?

A reader query on the recent CGT reforms has revealed a bigger issue. One overlooked feature of the old system may have done more than compensate for inflation. As we move to indexation, are we forgetting to reward risk?

Investment strategies

Bonds: The income and diversification trade-off

Rising yields have made bonds attractive again, but that does not mean they will behave as expected. As inflation, fiscal pressures and geopolitical risks reshape markets, the role of bonds may be more complicated than it appears.

Investment strategies

Why high-dividend investing deserves another look

Income investors have endured several lean years, but signs of a recovery are emerging. As opportunities improve, investors face an important choice between chasing headline yields and building a reliable source of income.

Investment strategies

Why 'overvalued' has been such an expensive word

Investors love simple rules, especially when markets appear stretched. Yet some of the strongest returns have arrived when the outlook seemed least attractive. This leaves an important question that history struggles to answer.

Investment strategies

AI – A good kind of bubble or just a bubble?

Investor obsession with AI is attracting unprecedented amounts of capital and confidence. But beneath the excitement lies uncertainties about returns, funding and risks that enthusiasts may not be paying enough attention to.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.