Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 653

Financial advice as the pathway to economic security

The theme of International Women’s Day was “give to gain”. If you are still thinking about giving a donation or volunteering I have a suggestion. Consider giving yourself, your daughters or your mother financial advice to gain economic security. Because you probably know these stats: women tend to score lower on financial literacy tests, end up with lower superannuation balances and find themselves in a more precarious financial situation in retirement than men. So, can advice help? Let’s take a look.

Advised members report higher levels of financial knowledge

The gender gap in financial literacy levels is stark. Only 48% of Australian women are considered financially literate compared to 63% of men[1]. Our education system has got work to do, particularly when you consider financial literacy levels are lowest amongst our younger people – those aged 15 to 24. Advice can help.

In a recent UniSuper study[2], we found our advised members reported higher levels of financial knowledge compared to our unadvised members. But remember that advice isn’t just a meeting with an adviser, it can be self-served too. Many super funds provide online education, including webinars on different topics. Some funds also offer free digital advice, or one-on-one advice on topics such as the investment option you’ve selected in super and whether it’s right for you. International Women’s Day is your moment – whether it’s reading a quick article or meeting with an adviser. It can make a big difference to both your financial knowledge, but more importantly your super balance. Involve your daughters – the power of compounding means good decisions made early will have a big impact on their super balance for retirement.

Advice can narrow the super balance gender gap

And that’s important because we still lag men when it comes to our super balances. In fact, on average, women in their mid-50s have a super balance that’s $55,000 lower than the average man at the same age.[3] It’s a time when the compound lifetime effects of carer responsibilities and often lower paid work show up.
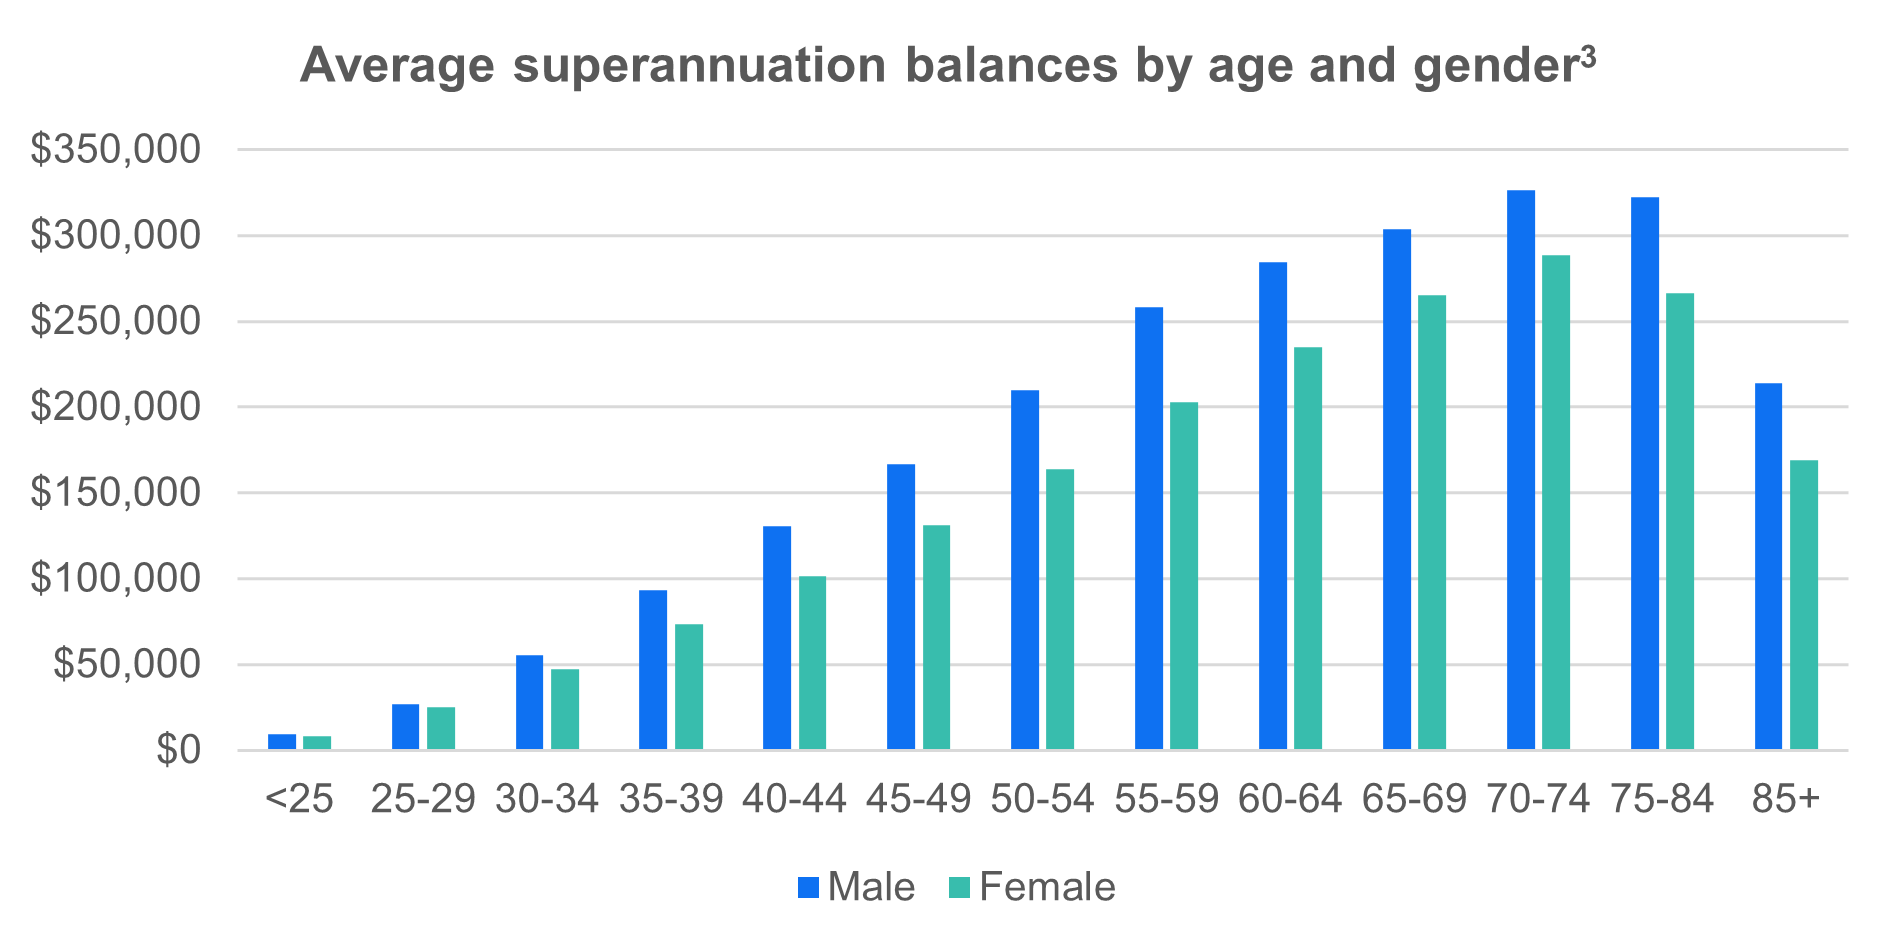
Advice can help close this gap too. Not only through the options outlined above, but through personalised strategies for women taking time out of the workforce for carer responsibilities. For example, your spouse can make an after-tax contribution to your super while you’re out of the workforce, or split their before-tax contributions into your superannuation account instead of theirs. Give yourself the gift of advice to help equalise super balances!

Advice can improve living standards in retirement

Finally, women generally retire in a more precarious financial situation than men, often for a few reasons. On average, women retire 2.4 years earlier than men; are 2.5 times more likely to face primary caregiving demands between ages 45 and 65 (after having cared for children); and often as a result retire with lower super balances. We then of course typically live longer than men. Any one of these factors impact the financial situation you find yourself in retirement. Financial advice can help. Our study showed that advised members tend to take more tangible actions towards securing their future. A few, simple decisions can make a difference to your standard of living in retirement.

What will you “give to gain” for International Women’s Day?

Gaining financial security is one of the most important gifts you can give yourself and others. Improved financial literacy, a healthier super balance and a higher standard of living in retirement is important for everyone. Advice does help. Our advised members feel more financially confident and more prepared for retirement. Use this year’s International Women’s Day as your moment to “give yourself financial advice to gain” economic security. You’re worth it.


[1] 2020 Household, Income and Labour Dynamics in Australia (HILDA) survey
[2] 2025 CoreData Research, Best Possible Retirement – UniSuper Report
[3] APRA Quarterly Superannuation Industry Publication - Sep 2025


Annika Bradley is Head of Advice Strategy, Research & Technical at UniSuper, a sponsor of Firstlinks. She brings over 20 years of experience across investments and wealth management in both the public and private sectors. In previous roles Annika worked with Morningstar and QSuper. The information in this article is of a general nature and may include general advice. It doesn’t take into account your personal financial situation, needs or objectives. Before making any investment decision, you should consider your circumstances, the PDS and TMD relevant to you, and whether to consult a qualified financial adviser. Issued by UniSuper Limited ABN 54 006 027 121 the trustee of the fund UniSuper ABN 91 385 943 850.

For more articles and papers from UniSuper, click here.


  •   11 March 2026
  • 1
  •      
  •   

RELATED ARTICLES

The retirement scorecard: how many of these questions can you answer?

When losses in super become irreplaceable

Australia has saved $4.5 trillion for retirement. Here's what matters more

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.