Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 390

Five ways to build investment portfolios amid growing inequality

Most investors are aware that COVID-19 is accelerating economic forces such as indebtedness, low interest rates and asset price inflation. But there is perhaps less awareness of another powerful trend that COVID is also accelerating: the ‘Gilded Age’-style economic inequality that has been emerging in recent decades.

Inequality is an important consequence of our economic system, and we see it becoming more extreme in a post-COVID world.

Growing inequality will lead to slower economic growth, even more indebtedness, increased financial risk, and greater political instability. These are all factors that will have a significant impact on investors’ portfolios.  

Inequality creates winners and losers. And there are key steps that investors can take to be on the right side of these changes – to not only protect their portfolios from accelerating inequality, but also generate strong investment returns into the future.

The return of the Gilded Age

At the start of the 20th Century, the world was in the grip of the ‘Gilded Age’ as described by Mark Twain. Plutocrats accumulated vast fortunes and economic inequality surged as the top 1% captured a disproportionate share of income from wages and capital.

Following two world wars, this inequality reduced dramatically with higher taxes, weak asset prices, and financial repression by governments. That continued for three generations.

But inequality began to return in the 1980s and 1990s, driven by ‘super managers’ – corporate executives earning huge wages and bonuses. And we now have a new era of billionaire plutocrats such as Gates, Bezos and Musk. Indeed, some historians are calling our current economic situation the ‘New Gilded Age’.
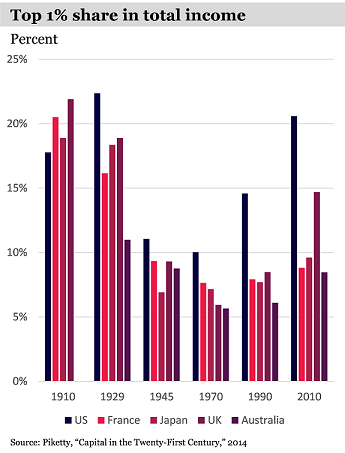
The US has found itself back to pre-WWII levels of inequality. The top 1 per cent capture more than 20 per cent of total income, up from 10 per cent just 40 years ago. What’s more, that doubling of income flowing to the top 1 per cent came from the bottom 50 per cent. More recent data from the US Federal Reserve suggests that over 30 per cent of total wealth is attributable to the top 1 per cent in the US.

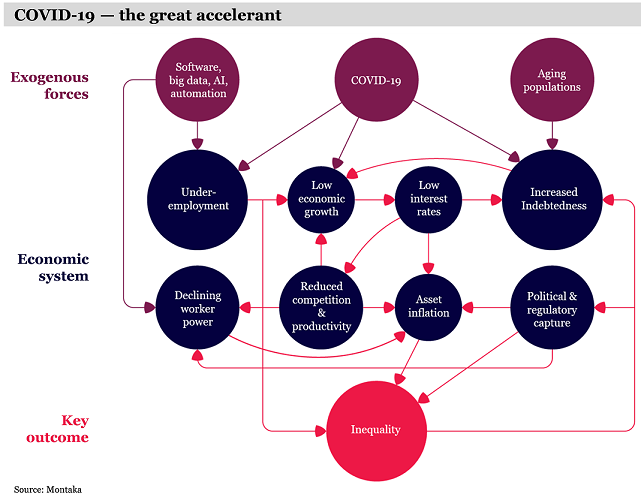
There is no doubt that inequality is being driven by an economic system in which structural forces such as technology, indebtedness, globalisation and demographics deliver low interest rates, low growth, and asset price inflation.

Other drivers – falling competition and productivity, political and regulatory capture, and declining worker power – are also creating ‘feedback loops’ that compound the dynamics above.

A natural result of this system is higher inequality, as wealth gains importance and power, while the middle and lower classes struggle to raise their incomes and maintain living standards.
Unpleasant side-effects

Growing inequality is leading to a number of adverse economic and political side effects.

The first is rising indebtedness. The wealthy can’t spend all their income, so instead use it to accumulate more assets. The value of these assets, however, is underpinned by the continued consumption of lower income earners – which can only be effected with additional borrowings, given their income stagnation. But should borrowers reduce spending to make payments on their debt, then aggregate economic growth deteriorates.
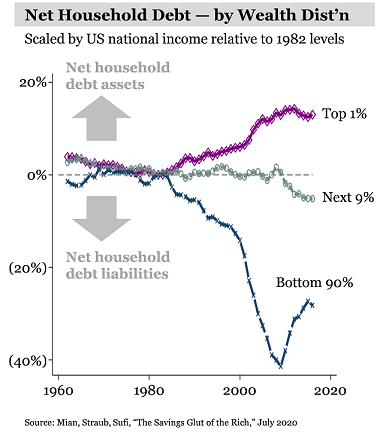
Inequality heightens financial risk. With lower income earners heavily indebted, this higher leverage exposes the economy to a greater risk of financial crises.

Inequality also increases political instability. The wealthy can use their growing power to influence Government and politicians. It can also cause political parties to ramp up rhetoric that leads to social division.

COVID-19 accelerant

Over the long run, we expect COVID-19 to act as an accelerant to an economic system that was already driving inequality higher.

For a start, COVID is disproportionately hurting low-income earners. Between March and July, 2020, 28 per cent of workers in families making less than US$40,0000 a year were laid off, considerably higher than the 13 per cent of workers from families with incomes over $100,000 a year.

COVID is also leading to increased indebtedness – particularly at the government level. Across the board, fiscal deficits for 2020 are blowing out. In the US, for example, the level of deficit spending (as a proportion of GDP) has not been experienced since 1945.
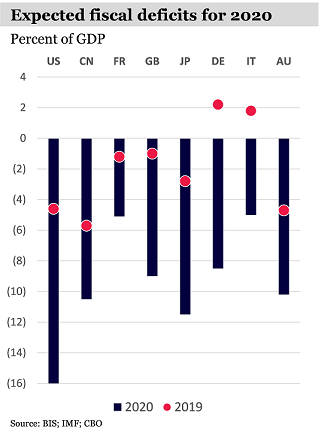
This debt will likely exacerbate the low-growth, low-interest rate environment that elevates the relative importance of wealth accumulated in the past and that exacerbates the political side-effects of inequality.

Five investment implications

So how do investors prepare for a world of growing inequality?

We believe there are five things investors should do to navigate this landscape.

1. Favour equities over fixed income assets

The economic environment described above is perversely favourable for equities (and highly unfavourable for fixed income assets). The most plausible long-term path out of our global mountain of indebtedness is via financial repression.

Financial repression will see real interest rates remain depressed (and likely negative) for an extended period. This is a painful environment for fixed income assets and a wonderful environment for equities.

2. Focus on businesses generating high-quality growth

It is logical to own businesses which can deliver high-quality growth. In the low growth world that naturally results from the current economic system, the most resilient and sustainable growth stories are those which relate to ‘penetration’ or ‘disruption’ of existing large addressable markets, rather than those which derive their growth from the broader economy. The biggest sustainable growth story taking place right now is the digital transformation of the enterprise, in our view.

3. Seek a sustainable data advantage

Investors should own those businesses that have sustainable and growing data advantages and are winning from the new technology this data unlocks. Similarly, those businesses being disrupted by these new forms of technology should be avoided.

Obvious examples of businesses with growing data advantages include Amazon, Facebook and Alphabet. Less obvious examples include Spotify, Blackstone and UnitedHealth.

4. Invest in businesses with wealthy customers

In a time of accelerating inequality, companies with wealthier customers are preferable and more likely to deliver the high-quality growth we seek.

On the consumer side, Apple has demonstrated the enormous value of a relatively wealthier customer base (versus, say, the Android customer base); as has Salesforce and ServiceNow on the corporate/enterprise side.

5. Buy businesses contained in borders

And finally, investors should prefer businesses which are contained within borders, or stable economic blocs.

Higher inequality increases cross-border trade imbalances, and we see a high probability of ongoing economic nationalism, trade disputes, as well as a likely decoupling with China – at least along the dimensions of critical technology and data.

Microsoft dominates the world outside of China in cloud-based platforms and productivity applications, for example. While Alibaba and Tencent dominate the Chinese mainland in cloud, e-commerce, digital advertising and gaming, for example. The cross-border overlap here is favourably minimal.

Prepare your portfolio

There is no doubt that growing inequality is one of the major trends of our era. And it is accelerating post-COVID-19. Inequality doesn’t just have social implications, it has economic and investment implications as well.

The Gilded Age eventually ended and after World War II as we entered a new period of equality. We don’t know how long this new ‘Gilded Age’ of growing inequality will continue, nor how it will end.

But investors need to prepare their portfolios to navigate a landscape of low-growth, low interest rates, and rising inequality.


Andrew Macken is Chief Investment Officer at Montaka Global Investments. This article is based on a new in-depth Montaka research paper titled Covid-19: accelerating our journey to inequality which can be found at montaka.com/blogs


  •   13 January 2021
  • 4
  •      
  •   
4 Comments
chris gallus
January 13, 2021

What level of Moat does Microsoft have? Does Microsoft have a sustainable moat?

Graeme
January 13, 2021

Interesting that Macken sees the "long-term path out of our global mountain of indebtedness is via financial repression" and asserts that "Financial repression will see real interest rates remain depressed (and likely negative) for an extended period."

So the way to fix too much borrowed money is to encourage borrowing more money, resulting in "a wonderful environment for equities" with continued "rising inequality." This is of course what's been happening for several years. Unfortunately, with central banks knowing no different and encouraged by the gilded 1%, I fear Macken will be proved correct. One should also, of course, show not the slightest surprise by the resultant continued rise in social unrest.

Dudley.
January 16, 2021

Missing from the flow diagram: China.

After awakening from it's totalitarian nightmare, China wanted less dogma, more material progress. It set about that goal in most deadly earnest. That resulted in great inequality but also a large economy based on ultra cheap manufacturing labour, Western technology - and Western markets.

Western enterprises out sourced production to China resulting in trade surpluses for China and deficits for most Western countries. Lower costs but also lower wages for Western manufacturing workers.

High growth in China. Low growth in the West - and low interest rates - and high debt - requiring massive government action to prevent a cascade of debt defaults - which supposedly would result in economic depression.

As faith in governments ability to keep the house of cards aloft decreases, interest rates will decrease and blow the house down.

Trevor
January 19, 2021

"But inequality began to return in the 1980s and 1990s, driven by ‘super managers’ – corporate executives earning huge wages and bonuses. And we now have a new era of billionaire plutocrats such as Gates, Bezos and Musk. Indeed, some historians are calling our current economic situation the ‘New Gilded Age’."....."Obvious examples of businesses with growing data advantages include Amazon, Facebook and Alphabet." Why not add "Tesla". But the very businesses owned by Gates, Bezos and Musk are the ones that you advocate owning "3. Seek a sustainable data advantage" which should exacerbate the "Growing inequality [ which] will lead to slower economic growth, even more indebtedness, increased financial risk, and greater political instability." ......according to you! "But investors need to prepare their portfolios to navigate a landscape of low-growth, low interest rates, and rising inequality."........ By buying the very companies that are creating all this inequality? We are living in the best of times with the least poverty and the most well-being ever experienced in human existence. The covid vaccines and the general good health, good food and the good living conditions we enjoy will see us through this temporary "glitch" and it will all seem like a bad dream and not Armageddon ! Things will return to normal. I disagree with the content and ominous portent of your article. "Brother, as you ramble on through life , whatever be your goal , Keep your eye upon the doughnut and not upon the hole!"


Leave a Comment:

RELATED ARTICLES

Five structural headwinds hitting the global economy

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.