Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 413

How are high net worths investing and thinking now?

The pathways to wealth are many and varied. For one person it may come from manufacturing, for another it may be entrepreneurial flair, while for another it may come from working the land.

A common misconception is that people that have achieved significant wealth are automatically good at managing it and understanding the investment opportunities available to both protect and grow that wealth. The reality is while someone may be very clever in their area of expertise, most of us cannot be experts across multiple disciplines.

Investing has become more difficult

Since the GFC of 2008-09, there has been a series of events that have made investing more problematic, including:

  • The descent into an extended low interest rate environment, making some of the more common investment products like savings accounts and term deposits less attractive.
  • Less stable global environment, driven by a retreat from globalisation and the rise of nationalist interests and leading to real and threatened trade wars.
  • Increased digital disruption creating both rapid transformation and disruption in many industries, making equity investments more difficult to formulate.
  • ‘Black swan’ events like COVID-19 have made forward forecasting particularly difficult, even impacting resilient markets like property.
  • Lack of knowledge of investment alternatives outside of the big three – cash, shares and property.

The last point showed up clearly in research undertaken this year by Citi, with over half of wealthier investors citing lack of knowledge as the greatest impediment to examining other investment opportunities.

How do Australia's HNW investors feel about investing?
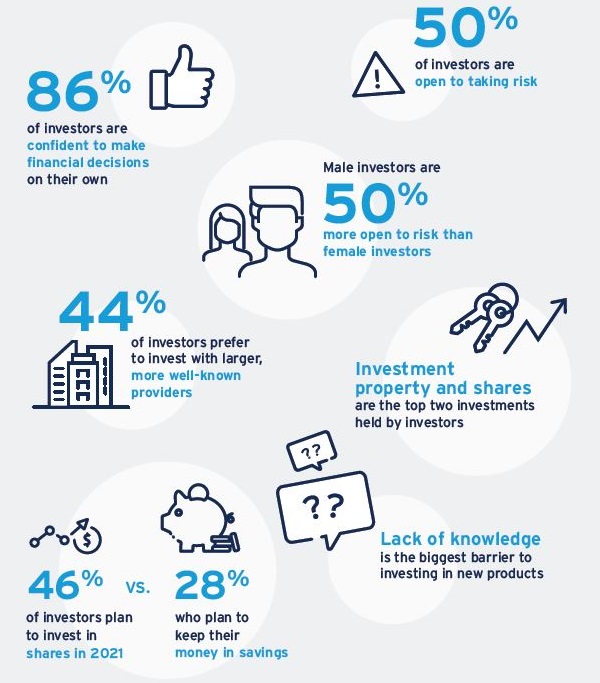
Outlook gives investors optimism

However, investors are also eager to take advantage of what they perceive as improving economic conditions. The research showed wealthier investors are 2.5 times more optimistic about the outlook this year compared to lockdown riddled 2020.

How do Australia's HNW investors feel about today's economic outlook?
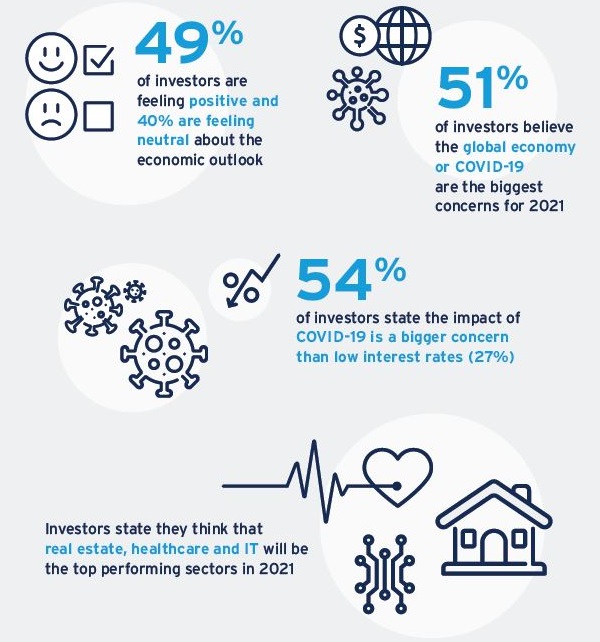
COVID-19 remains the main concern to the outlook, followed by trade wars. Low interest rates are a major concern for less than one-third of surveyed investors.

That is likely because many wealthier investors are also approaching or in retirement and are more concerned with preserving wealth than high growth strategies. For that reason, they can build portfolios that carry less risk but still provide an acceptable return.

Diversification remains an elusive goal

The research shows wealthier investors are still struggling to embrace portfolio diversity, with 54% only holding domestic shares in their portfolio. It’s likely increased education on the benefits of diversity both by asset class and geography would see this concentration reduced. Citi’s clients tend to favour greater exploration of investment opportunities available, with 57% taking some form of international investment by the end of the first quarter of 2021.

Where do Australia's HNW investors choose to invest?
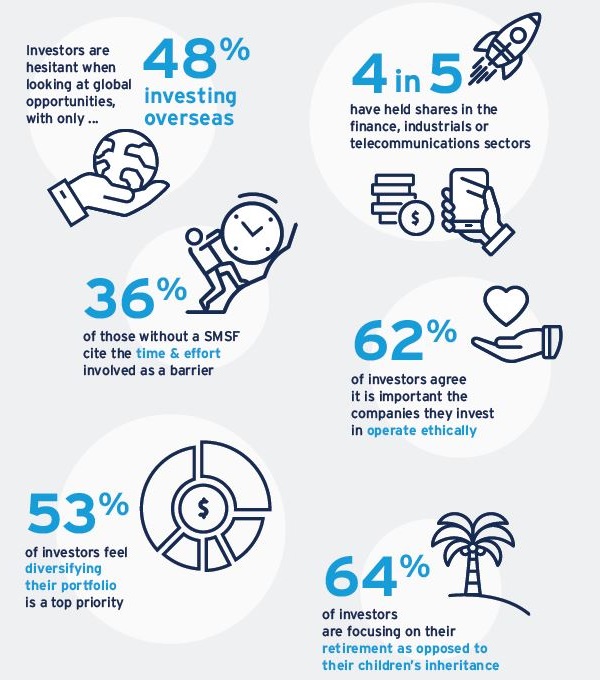
Investment areas of interest

Two areas that wealthier investors are showing particular interest in is healthcare and property.

Australian healthcare stocks, which include some leading global companies, have underperformed the ASX200, by 30% over the past 12 months. It is not a phenomenon restricted to Australia. In the United States the price of healthcare stocks, based on forward earnings estimates, trade at a 30% discount to the S&P500 index.

This is an real opportunity to gain an exposure to one of the few sectors remaining that we do not consider expensive following 15 months of stocks rising since markets started pricing in a COVID-19 recovery.

In property, we expect buying strength to remain robust for the remainder of the year with price growth exceeding 10% for the year. However, we view increasing issues with affordability to temper growth next year, with growth contained below 4%.

Despite outbreaks of the pandemic continuing to impact many parts of the world we are solidly in a global recovery phase. It aligns us with investors optimism going forward, but we remain cautious that volatility has been a consistent driver of markets over the past decade and will likely remain a significant element in portfolio construction for the foreseeable future.


Gofran Chowdhury is Head of Investment Specialists at Citi Australia, a sponsor of Firstlinks. Information contained in this article is general in nature and does not take into account your personal situation.

For other articles by Citi, see here.


  •   23 June 2021
  • 13
  •      
  •   
13 Comments
Humphrey
June 23, 2021

Dear Noel Thank you for your very informative article. Humphrey

William Clarke
June 23, 2021

I am amazed that Corporate Bonds are not included. I have 50% of my portfolio in bonds, 15% in US stocks and the balance in the ASX.
Regards
William

CC
June 23, 2021

corporate bonds. watch out when interest rates rise...

Warren Bird
June 30, 2021

Good on you William! I don't have as much as 50%, but that's purely a personal asset allocation thing. I certainly have them though - all my fixed interest is in diversified, well managed corporate and high yield bond funds. As for CC's concern to 'watch out when interest rates rise', I can only refer to my several articles about this subject, in which I argue that rising yields result in higher returns beyond the very short term. I would make the additional note that even in the short term corporate bond funds have less to be concerned about because they tend to be shorter duration than broader bond funds that have longer term government securities in them.

Peter
June 23, 2021

What is the definition of a High Net Worth investor?

Jason
June 23, 2021

HNW investor is normally from the $10m mark.

Niki
June 30, 2021

Over 10 million each person
Lower is
Comfortable living

Sparty
June 30, 2021

"From a sample of 1000 high-net-worth (HNW) individuals – defined as those having a minimum of $1 million in investable assets – and ultra-high-net-worth (UHNW) individuals, with at least $10 million in investable assets –" https://www.afr.com/companies/financial-services/australian-investors-lack-sophistication-20190724-p52a5p Jul 24, 2019

Abraham Robertson
June 26, 2021

Great article Gofran - very interesting insights. When we surveyed our client base (wholesale investors only) in May we found sentiment shifting from bullish to bearish in terms of equities, and we have noticed a swing in demand towards products I'd classify as "risk-off". While our clients are positive about the future, the short term outlook for equity markets was that we are at the pointy end. Did you conduct any sentiment analysis in your survey that you could share?

Graham Hand
June 26, 2021

High Net Worths in this survey are defined as: “A minimum of 250k investable assets excluding property, or personal income above 250k for at least 2 years, or total assets, including equity in property, of $2.5m”

Kelvin Russell
June 27, 2021

We should note that COVID-19 and it's market effects are not "Black Swan" events. Nassim Nicholas Taleb, who wrote the book "The Black Swan", has specifically stated this. The timing and severity of COVID-19 was not predictable, but the market fluctuations are part of the normal volatility that forecasting takes into account.

Ruth
June 30, 2021

Yes Kelvin, Taleb says the disease is not a black swan event. But what was for me was the cover-up. For decades there has been understanding between nation states to promptly report disease so it can be contained. Unless that disease is a bio-weapon. But I suppose use of a bio-weapon is something that's not unforeseeable either. I like his books.

Lisa
June 30, 2021

It's encouraging to see HNW investors are ready to embrace diversification, which has seen me through these difficult times since 2008. It certainly has taken a long time for the local stock market to regain values it had before the GFC. Without the addition of bonds, property and cash, the average shares investor would have waited a long time for improvements.


Leave a Comment:

RELATED ARTICLES

Wealth doesn’t equal wisdom for 'sophisticated' investors

Do HNWI get better advice?

Today’s case for floating rate notes

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.