Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 618

Investors might be paying too much for familiarity

In today’s investment landscape, the dominance of the US—especially a handful of mega-cap technology companies—is hard to ignore. These firms have powered a disproportionate share of global equity market returns in recent years, and the US now accounts for around 75% of the MSCI World Index. The so-called ‘Magnificent Seven’ have captured investor imagination and capital alike. But when nearly everyone is crowded around the same trade, it’s worth asking: what if we’re all looking behind the wrong door?

Enter the Monty Hall problem. This classic probability puzzle, loosely based on a 1970s game show, involves a contestant picking one of three doors—behind one is a car, behind the others, goats. After the contestant picks, the host (who knows what’s behind each door) opens one of the remaining doors to reveal a goat. The contestant is then given the option to switch. While most stick with their initial choice, switching actually doubles the contestant’s odds of winning the car!

The puzzle is a compelling metaphor for today’s markets: just because something feels obvious—or has worked recently—that doesn’t make it the right choice in future.

Lesson 1: The obvious choice isn’t always the best one

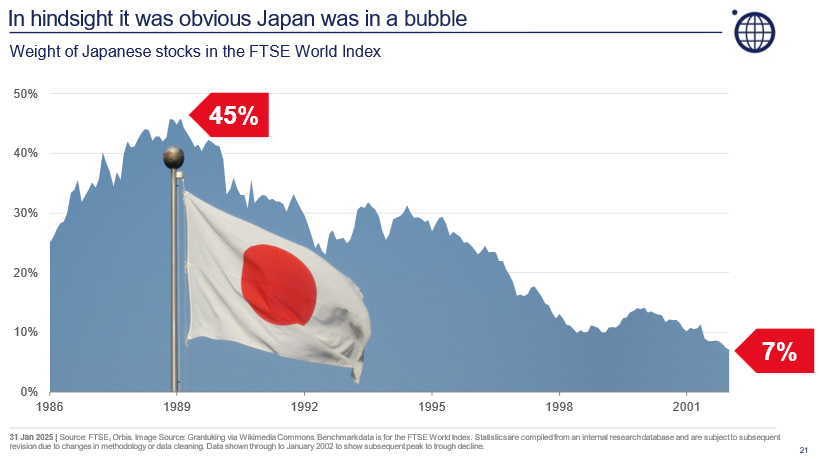
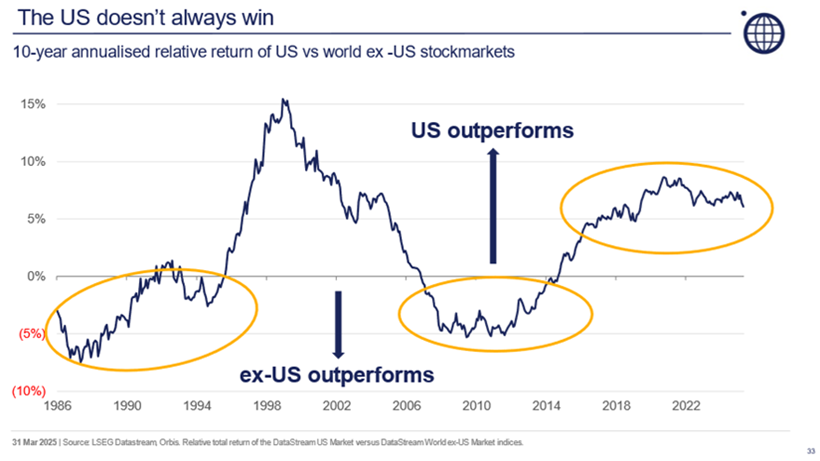
On the surface, staying heavily invested in US equities looks sensible. It’s the world’s largest economy, home to dominant companies, and it has outperformed for over a decade. But history reminds us that market leadership shifts. In the late 1980s, Japan made up more than 40% of the global index—before its bubble burst. Similarly, the dot-com crash of 2000 exposed the perils of speculative excess in the technology, media and telecoms sectors. Both events were obvious in hindsight, but herd mentality and a fear of missing out clouded judgements at the time.
Today’s US equity market shows signs of similar concentration and froth. President Trump’s renewed tariff threats have unsettled markets as well as global supply chains, and fresh US export restrictions on chips to China prompted warnings from NVIDIA about billions in lost revenue. Meanwhile, valuations remain stretched.

For a generation of investors raised on uninterrupted American outperformance, it may be time to reassess where the real risks—and opportunities—now lie.
Lesson 2: Insight matters—but only if you act on it

Spotting market dislocations is one thing, acting on them is another. Investors may sense that sentiment is frothy but going against the crowd is always difficult. It’s particularly hard when the prevailing narrative is that “AI is the tide that will lift all boats” and investors are surrounded by highly speculative activity being wildly profitable.

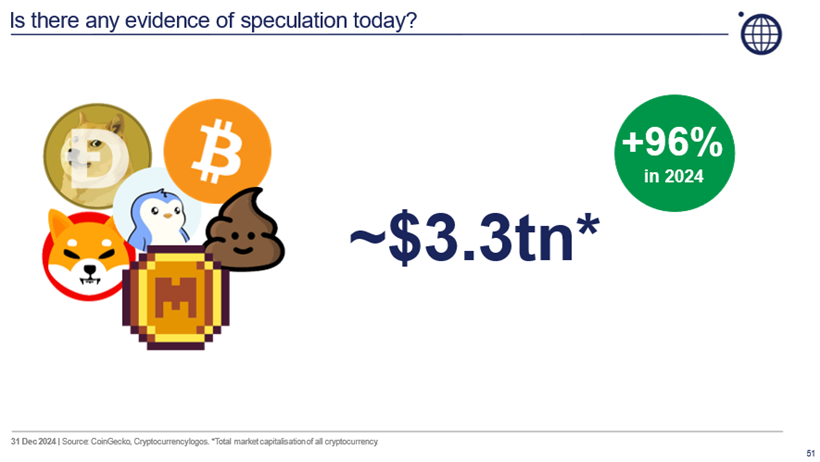
At the end of 2024, cryptocurrencies and digital tokens were valued at $3.3 trillion—up 96% in a year. In a sign of the times, ‘Fartcoin’ which was launched in October ended 2024 with a market cap just shy of $1 billion. That’s more than three times the peak valuation of Pets.com, the dot-com bubble’s poster child, which managed to go public and go bankrupt in the same year back in 2000.
Meanwhile, US hyperscalers have been ramping up capital expenditures to chase AI dreams—with no clear line of sight to monetisation. Their ratios of capex to sales are rising sharply, and it’s not clear that returns will justify the outlays.

And that’s the crux of it: markets aren’t always efficient—especially when investors are chasing hype over substance. As the Monty Hall problem teaches us, knowing the odds isn’t enough. You need to tune out the noise and have the conviction to switch, even when it feels uncomfortable.

Lesson 3: Nothing is certain—apart from death and taxes

Even with the optimal Monty Hall strategy, contestants only win two-thirds of the time. In investing, research shows that even top-tier managers only get it right about 60% of the time. That’s why broad and thoughtful diversification—across sectors, geographies, and styles—is so valuable.

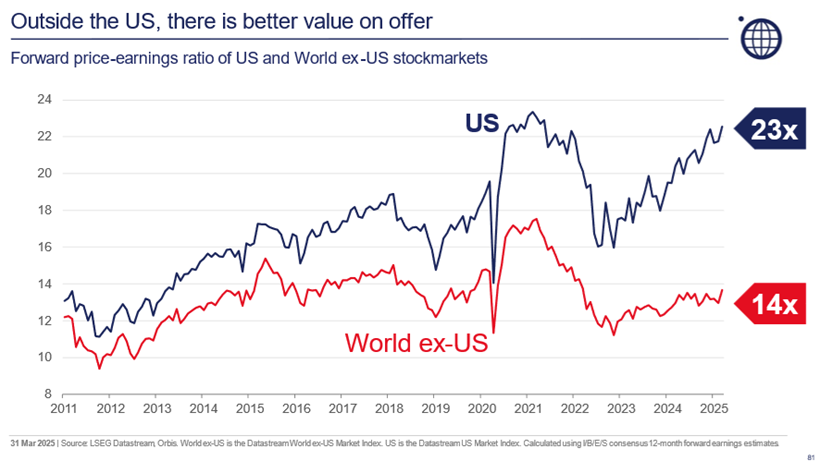
Many investors today believe they’re diversified because they hold global index trackers. But with US stocks now making up nearly 75% of global benchmarks like the MSCI World Index, many portfolios are far more concentrated than they appear. That concentration is made more problematic by valuation levels. The S&P 500 trades at around 23 times forward earnings—well above its historical average and significantly more expensive than global markets, which average closer to 14 times. This discrepancy suggests that investors might be paying too much for the comfort of familiarity.
Meaningful diversification is about holding assets that behave differently—and the benefits are felt most when the prevailing market trends reverse. Investors need to ask whether their portfolios are truly positioned to weather regime changes. And if they aren’t, what’s stopping them from switching?

Reframing comfort zones

The Monty Hall problem teaches us that the obvious answer isn’t always the correct one. The same holds true in investing. Sticking with the US and big tech may have felt safe, until very recently at least, but sticking with what’s familiar can offer false comfort. In today’s environment, defined as it is by extreme market concentration and investor herding, the real edge lies in having the conviction to take a different path.

Ultimately, investors must always be sceptical about simply following the prevailing market consensus, as current prices already reflect those views.  Proper diversification today also requires going beyond simply mirroring global benchmarks.

Just as switching doors improves your chances in the Monty Hall problem, being willing to look beyond the obvious and focus on where value is being overlooked is the key to long-term success in investing.


Werner (Vern) du Preez is an Investment Specialist at Orbis Investments, a sponsor of Firstlinks. This article contains general information at a point in time and not personal financial or investment advice. It should not be used as a guide to invest or trade and does not take into account the specific investment objectives or financial situation of any particular person. The Orbis Funds may take a different view depending on facts and circumstances.

For more articles and papers from Orbis, please click here.


  •   2 July 2025
  • 4
  •      
  •   
4 Comments
Nadal
July 03, 2025

"While most stick with their initial choice, switching actually doubles the contestant’s odds of winning the car!"

This is false. Both doors at this point have a 50% probability of hosting the car.

Jeff
July 04, 2025

It sounds counter-intuitive but the Monty Hall paradox is mathematically proven to be true:

https://en.wikipedia.org/wiki/Monty_Hall_problem

Ian
July 06, 2025

You would be correct if the host opened one door BEFORE you made your original choice, however once you have made your choice (with a 1/3 chance of being correct), he is not opening a random door anymore. The two doors he now has to choose from have a combined probability of 2/3 of hiding the car, and since he must choose a door that doesn't have it, it leaves only the other with that 2/3 chance. Thus doubling your chances of winning if you swap. A key here is that he is always committed to opening one of the doors before you make your selection - if he only offered it sometimes, it could indeed be used to sway you to make the change when you have actually selected the car.

Peter
July 07, 2025

Afraid I don’t get it and can’t see why Nadal is wrong. At the start of the game, the player always knows that the host is going to remove one of the doors with a goat behind it. So the player’s initial selection does not matter. The player knows that with his final choice there will be be only two doors, giving him a 50% chance of choosing the right one by either changing his initial selection or not.


Leave a Comment:

RELATED ARTICLES

The diversification illusion: why 'balanced' portfolios may be exposed

The problem with concentrated funds

The enduring wisdom of John Bogle in five quotes

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.