Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 591

Is Medibank Private a bargain?

The Medibank and ahm private health insurance brands serve over 4.2 million customers and play a vital role in funding medical care in Australia. In the most recent financial year, Medibank paid out $6.3 billion in health insurance claims, taking a significant burden off the public healthcare system.

Yet recently, the sector has come under fire from both the government and hospitals accused of making too much profit. In this article, we explore this regulatory tension and why we think Medibank looks an attractive investment opportunity.

Private hospital profits affected by new models of care

There is no doubt the past few years have been challenging for hospitals – labour shortages have affected service levels and inflation has been rampant. Private hospital operators have responded by launching a campaign against the health insurers and pressuring the government for a bailout. While additional payments or a tax may provide short-term relief to hospitals, they do not solve the structural issues facing the sector and ultimately would drive up the cost of healthcare and premiums for millions of Australians. To build a sustainable private healthcare system, all participants must work together to find efficiencies and drive down the overall cost of care.

Medibank is doing its part to lower costs by investing in new models of care away from overnight stays in expensive acute care hospitals to virtual, short-stay hospitals and home care. Without this transition, Medibank estimates the government will need to spend 50% more on healthcare as a percentage of GDP in 40 years. While this transition does come at the expense of hospitals that typically earn more for longer in-hospital stays, it is beneficial for the wider healthcare system. Higher hospital costs would simply translate to higher premiums, which are likely to push more members out of private health insurance and place further strain on an already stretched public healthcare system.

It is for this reason the Federal Health Minister following a review has conceded, “There’s no silver bullet from Canberra or funding solution from taxpayers to deal with what are essentially private pressures in the system”. Ultimately, it is not the government’s job to prop up unprofitable business models and in some cases, it is healthy for some private hospitals to shut where there is overcapacity in the system.

Has Medibank profited at the expense of hospitals?

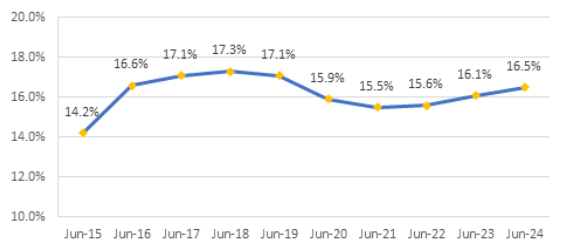
Medibank has stuck to its promise not to profit from the pandemic and returned a total of $1.46 billion in givebacks to customers for permanent claims savings due to COVID-19. This is evident in the chart below which shows Medibank’s health insurance gross profit margin is still below FY19 levels.

Figure 1 – Medibank Health Insurance Gross Margin
Source: Company filings

Fear of regulation creates opportunity to invest

While there remains uncertainty as to how the regulatory situation will unfold with a federal election coming up, we think it’s unlikely the government will step in and prop up private hospitals where there is a clear shift to lower-cost care outside the hospital. In the meantime, we believe this creates an opportunity to invest in Australia’s largest health insurer, which has grown its earnings per share at 8% p.a. over the past decade.

Medibank screens as a high-quality business under our investment process for the following reasons:

  1. Financial strength: Medibank has a strong capital position with a capital ratio of 14.1%, well above its 10-12% target range, and has zero debt on its balance sheet.
  2. Business quality: Medibank is Australia’s largest health insurer with 4.2 million members (27% market share). This scale enables Medibank to negotiate better terms with hospitals keeping a lid on claims inflation while sharing these savings with members to lower premiums and improve retention.
  3. Management quality: David Koczkar has been the CEO since 2021 and prior to this was the COO since 2014. Over this period, the company has seen a return to policyholder growth, expanded its health offering and tightly managed its costs.

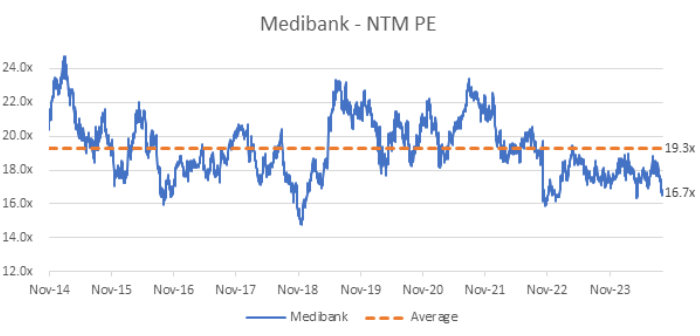
Finally, from a valuation perspective, Medibank is trading on less than 17x P/E (below its long-term average of 19x) and offers investors an attractive dividend yield of 4.6%.

Figure 2 – Medibank NTM Rolling PE
Source: FactSet


Emma Fisher is a Portfolio Manager and Deputy Head of Australian Equities, and Vinay Ranjan is Deputy Portfolio Manager at Magellan-owned, Airlie Funds Management. Magellan Asset Management is a sponsor of Firstlinks. This article has been prepared for general information purposes only and must not be construed as investment advice or as an investment recommendation. This material does not consider your investment objectives, financial situation or particular needs.

For more articles and papers from Magellan, please click here.


  •   18 December 2024
  • 7
  •      
  •   

RELATED ARTICLES

Picking the next sector winner

Is ResMed a trap or an opportunity?

Reece Birtles on selecting stocks for income in retirement

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.