Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 327

Markets relying on central bank sugar hits

Calendar year 2019 has been a tremendous year for returns from investment assets of just about every flavour except cash. The single most important driver of financial markets in Australia and around the world has been US interest rate policy. Share markets sold off sharply in late 2018 and the main cause was the US Fed’s four interest rate hikes during the year, as shown below. Their stated intention was to continue raising rates several more times despite gathering signs of economic slowdown and fears of negative impacts from Trump’s escalating trade wars.

Then from the start of January this year, the Fed suddenly did a backflip and put further rate hikes on ‘pause’. Short-term rates started to drift down in anticipation of Fed cuts, and shares suddenly switched from the sharp sell-off to a strong rebound in 2019. The chart shows global share prices over the past five years through the US rate hikes (red dots) and now the rate-cut rebound (green dots).
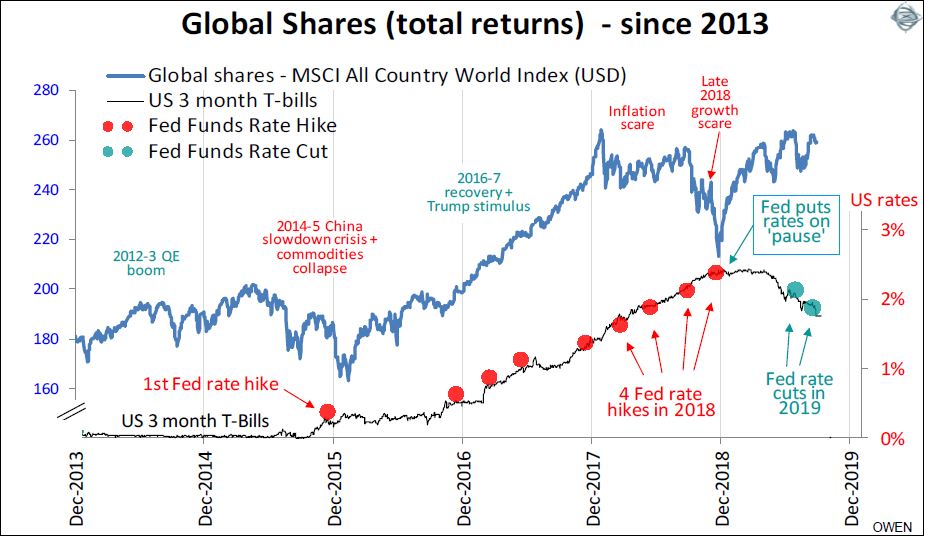
The Fed is driving markets

Under intense pressure from President Trump, the Fed started cutting rates on 31 July. When it cut rates again on 8 September, Fed chair Jay Powell noted: 'Trade policy tensions have waxed and waned and elevated uncertainty is weighing on US investment and exports' - without actually naming Trump. Ever since nominating Powell to the Fed role, Trump has attacked him for not cutting rates back to zero.

The Fed is also coming under pressure to re-start its ‘QE’ bond-buying programme. Trump's trillion dollar deficits need funding, and that means the government is scaling up the issue of new bonds. The sheer volume of new bonds, plus the fact that China is now selling US bonds, will put pressure on yields to rise, unless the Fed starts buying them again. Share prices surged during the last ‘QE’ boom in 2012-14, and the prospect of more QE is also supporting share prices this year.

In Europe, the central bank had ended its ‘QE’ last year but with European economies, inflation and jobs growth still stagnant, on 12 September the ECB resumed its rate cuts (further into negative territory) and announced a re-start of its ‘QE’ program of direct bond buying. It didn’t work last time so there is little reason to think it will work this time. But it certainly did artificially boost returns from bonds and shares.

In Australia, the Reserve Bank has also cut rates three times more this year (including 1 October), bringing the total to 15 rate cuts in the current cycle that started in November 2011. It is running out of room to move. The banks are not likely to pass on any more rate cuts to borrowers as they are already facing margin squeeze and declining profits. The RBA has even talked up the idea of Australian ‘QE’ bond purchases.

Several other countries have also cut rates as Trump’s trade wars continue to escalate and growth prospects dim. (There are exceptions to this global trend – Norway has hiked rates four times to try to rein in rampant debt-funded property speculation). With interest rates on deposits cut almost everywhere, investors have stampeded back into shares, commercial property, infrastructure and bonds this year – boosting returns on all asset classes – except cash.

Although investment returns have been boosted across the board this year, it is unsustainable of course because interest rates can’t continue to be cut into negative territory forever. 

What lies ahead?

Investors should not become complacent just because shares are doing well again. The rebound in 2019 has been due mainly to artificial and non-sustainable sugar hits from central banks. Meanwhile, out in the real world, economic activities like spending, lending, capital investment, trade and hiring, are slowing across the board.

It is true that Australia has managed to produce a rare budget surplus (and an even rarer current account surplus) but these have been due to unsustainable windfall gains from export commodities prices rather than spending cuts. On the contrary, government spending in Australia has increased at several times the rate of population growth and inflation, and in recent years the government has been the largest driver of employment growth. Outside of the government sector, the rest of the economy has been very weak.

What lies ahead is probably lower interest rates in Australia and in the major global markets - US, Europe and Japan – at the short end and also at the long end. This will most likely be accompanied by increases in government spending in Australia and the US, although there is less scope in Europe and Japan. These sugar hits will probably support asset prices as they have done in past rounds of rate cuts and QE. Governments cannot continue to increase their spending ahead of the growth in tax revenues required pay the interest bills.

There are two types of scares that rattle investment markets - inflation scares and slowdown scares. We have seen many examples of both types of scare in the past and we will see many more in the future. The difference between the two types of scare is their impacts on shares and bonds. Both shares and bonds suffer in inflation scares (both sold off in the February and October 2018 inflation scares), but in slowdown scares share markets fall but bond prices rise, as they did in the December slowdown scare. Inflation scares are the more difficult for investors as they hit both shares and bonds (including bond proxies).

The good news is that inflation scares (where both shares and bonds are hit) are less likely to be on a global scale now. The only risk of serious (say 5%+) inflation is in the US and Australia and some other small markets like Canada. We are unlikely to see serious inflation in Europe or Japan for many years – or perhaps ever, under their current political regimes. The problem (or good news for bond investors) is that Europe and Japan are dying – literally – with aging and declining populations, declining tax-payer bases, but rising welfare bills. One solution is immigration but this is proving politically impossible. The likely future is decay and deflation, not inflation.

On the other hand slowdown scares are more likely but they are less of a threat to investors because bonds (especially government bonds) tend to do well in big slowdown scares like the GFC, 2001-02 tech wreck and 1990-01 contraction. 


Ashley Owen is Chief Investment Officer at advisory firm Stanford Brown and The Lunar Group. He is also a Director of Third Link Investment Managers, a fund that supports Australian charities. This article is for general information purposes only and does not consider the circumstances of any individual.


  •   9 October 2019
  • 4
  •      
  •   
4 Comments
Garry
October 10, 2019

Here is the dilemma. Sell too early and you lose- do nothing and you lose.Sell all and stay in cash- you survive but you run down your savings and hence future earning capacity.
Socially,the less wealthy get even more disadvantaged the longer low/negative interest rate policies persist.
The GFC insight was that some debt became highly illiquid but blue chip stocks , even though the price got smashed, retained high liquidity.
The ever-mounting pile of government debt (and corporate debt in the US),may suggest when Armageddon hits, stay clear of bonds but keep a fair chunk in low-geared blue chip stocks. Their prices will also get hit but they will remain liquid and the companies will have every opportunity to acquire at fire sale prices/not be caught up in ugly/challenging restructures etc.
It also suggests that while we might bemoan Australia, our government debt and especially future public liabilities are not too onerous.
Living in the fastest growing part of the world , and with a growing population,is also a major advantage.
Regards Garry.

stefy
October 11, 2019

Where does this all end? It is surely not sustainable forever more.

Albert
October 11, 2019

Although investment returns have been boosted across the board this year, it is unsustainable of course because interest rates can’t continue to be cut into negative territory forever.

Why not??
Just because it's never happened?
It has now.

Governments cannot continue to increase their spending ahead of the growth in tax revenues required pay the interest bills.

Again why not?
After all if interest rates are zero or below ......

Personally IMO, QE and zero interest rates are the natural result of the insatiable appetite of the populace for endless consumption and hence ever mounting government debt. There is only one way to finance this -- QE and ZIRP

Warren Bird
October 13, 2019

This sort of analysis is fairly common, but like all the others that say the same thing they make one significant presumption. Which is that the central banks are acting exogenously to the economy and financial system; that interest rates and monetary policy could be something completely different if only each central bank chose to put them there; or that central banks are artificially setting rates at levels not justified by economic fundamentals.

What if that presumption is wrong? What if central banks are endogenous players, who operate within a system that impels them to take certain actions? What if rates are where they are because they have to be there and central banks are merely an agent that recognises that?

There's at least a strong element of endogeneity about their actions. Almost all of them - certainly the RBA, but also the Fed and others - set their policy interest rate relative to the idea that there's a neutral rate of interest. When the economy is overheating, generating inflation, they set the cash rate above that neutral rate; when the economy is struggling they set it below the neutral rate. The policy setting - tight, easy or neutral - is in their control, but the level of the neutral rate isn't. It's a reflection of the interplay between the real economy and the demand/supply balance for borrowed/loaned funds (saving and investment).

The goal is, in essence, to assist the economy to get back to a position where it's operating in a manner consistent with the neutral rate, move the Funds rate to that level and hold it there.

The Fed thought the neutral rate was around 3% so set off in that direction in 2018, only to discover that it was actually lower than that, hence their change of course in 2019.

The RBA thought we were there with the cash rate at 1.5% for 3 years and things humming along. And that may have been the case for a while, but our neutral rate isn't independent of global rates (we're all endogenous in reality) and they found that the neutral rate has now fallen. Hence the cash rate has also fallen.

Of course the Fed could have said 'stuff it, we're going to 3% no matter what because there are all these analysts out there who think we're keeping rates artificially low and we want to appease them'. But they didn't, because they've placed themselves in an endogenous position where they react to information about the neutral rate and the cyclical state of the economy, rather than acting capriciously or randomly. (That sort of behaviour characterised monetary policy making when politicians had control of it back in the 1970's and later.)

The idea of central banks providing a 'sugar hit' is to my mind nonsense. Yes, when the discount rate is lower then that supports valuations in long term asset markets such as shares and property. But rather than being a sugar hit, I see it more like an antibiotic drip that helps to prevent the underlying fundamentals that have pushed rates down from causing companies to die from infection.

It's time now, though, for other arms of policy to step in and help the healing of a very damaged world economy. For instance, when I read about the growing suburbs of Melbourne that have no public transport, no schools, etc I can see a very straightforward argument for more infrastructure spending, to enhance efficiency in both economic and social terms. Without such measures, the neutral rate of interest isn't going to go back up to anywhere near its old levels and central banks will need to keep the antiobiotic drip going.


Leave a Comment:

RELATED ARTICLES

The challenges with building a dividend portfolio

Finding single-digit PE stocks in an overvalued market

Will the RBA cut rates before the Fed?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.