The Treasury Laws Amendment (Improving Accountability and Member Outcomes in Superannuation) Bill 2017 proposes to expand the existing scale test of performance against costs for members to an outcomes test. This will require superannuation trustees to determine, on an annual basis, whether the fund’s MySuper products are meeting the clients’ best interests.
Many of these questions apply to SMSF trustees who are managing their own superannuation funds.
The intent of the change is to allow APRA to assess the overall governance and performance of default funds. APRA has advised what needs to be addressed but not ‘the how’. Trustees will need to develop their own framework.
Is there a need for the change?
To respond to this question, we need to answer the following two questions:
1. Has the scale test achieved what it was set out to achieve?
2. What should an outcomes test do differently?
What should an outcomes test do differently?
Some cynics say the scale test has failed. In the main, the scale test assesses performance and fees, seeking to prove a correlation between these and the size of the fund. However, in this case, size doesn’t always matter. Many small funds have proven the test wrong, consistently demonstrating good returns and low fees.
What should an outcomes test do differently?
The focus of the outcomes test is on sustainability, which in my opinion is a much better measure of a fund’s performance against costs to members. Ultimately its aim is to have funds determine what is in the best interest for their members and test the sustainability of this model.
In reality, most members rely on their employers to make the important decision when it comes to choosing their superannuation fund. But, superannuation is not most employers’ core business. So, how are they to know what is in the best interest of their employees? This question will become more important if the proposed changes to default fund status are legislated. Regardless of any new regulatory impositions though, all members should receive what’s in their best interest, but many funds, regardless of size, have struggled to define it.
How can a fund define best interest?
Firstly, funds need to define the most important goals for the members to achieve. In other words, what outcomes would the funds’ members like as a result of their experience with the fund? Each fund has different cohorts of members, so this definition of goals needs to be done at the member level, rather than at an overall fund level.
Funds then need to collect information that tells them whether the services, products and experiences offered are having the desired impact on its members. Is the fund making a difference in the lives of the members it serves and does it really know its members? Funds often say “we know our members better than anyone.” While this may be true, how does a fund support this bold statement?
The next step is for funds to define the strategy needed to meet these goals. The scale test drove a pattern of including growth in funds’ strategies, as there was a fear of not being at scale. Under the new outcomes test, strategies should be about ensuring the fund will continue to be sustainable and achieve the best interests of its members as previously defined. This may not always include growth.
Finally, funds need to set measurable metrics to support these goals. This is where funds need to be honest with themselves about future sustainability.
There is no single approach to a best interest assessment and APRA has not defined this. Funds will need to develop their own policy and practices, which reflect the specific circumstances of the fund and its members. It should be based on what the fund’s members value as far as possible.
How to conduct an outcomes assessment
Funds will need to evaluate how well they have achieved the defined goals for their members. Have they delivered what they set out to deliver, keeping in mind the different cohorts of members?
From there, funds should use the results to improve the experience. This is where funds may need to make the hard decisions. If goals have not achieved their desired outcome, the fund must understand why and determine the next steps. What can be done to fix it? And, where things have worked, could the fund be doing more?
Can we learn from our global counterparts?
Around the world, regulators are steering in the same direction when it comes to measuring funds’ performance against costs to members. However, the UK seems to be the most advanced, with similar thinking and the imposition by the UK Pension Regulator of a legal duty to assess value. The UK schemes are required to carry out an assessment at least annually, that focusing on the value provided by the scheme for the costs paid by members across the preceding year, and the influence this could have on future outcomes for those members.
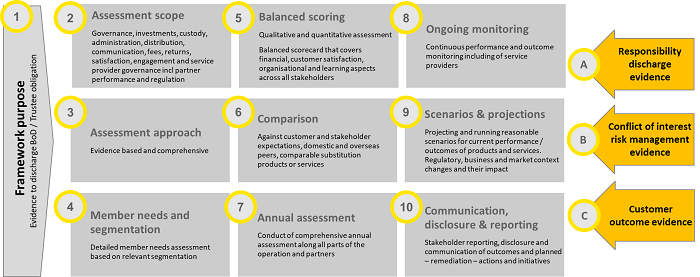
The UK regulator has also issued an illustrative example to the Pension Schemes, highlighting the areas that need to be captured, considered and assessed in order to assess value properly.
Best interest duty test dominates
Whatever approach is chosen, one key test has to be met – the best interest test. Funds should document the steps taken and be prepared to demonstrate the execution of a proper process and provide an explanation of how and why conclusions have been reached.
Maree Pallisco is the EY National Superannuation leader. The views expressed in this article are the views of the author, not Ernst & Young. The article provides general information, does not constitute advice and should not be relied on as such. Professional advice should be sought prior to any action being taken in reliance on any of the information. Liability limited by a scheme approved under Professional Standards Legislation.