Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 251

Rob Prugue’s spiritual super journey

Managing Editor's note: Rob Prugue is a leading figure in Australian funds management. He was most recently Senior Managing Director and CEO of Lazard Asset Management (Asia Pacific), responsible for the business across Asia. Rob is one of those executives and fund managers who always takes a broad view of the world. Conversations are not only about markets and economics but philosophy and social obligations, and he was actively involved in charity fund-raising. He retired after 15 years at Lazard to give himself a long sabbatical before considering his next role.

Part of this break from work includes an 800-kilometre walk along El Camino. The Camino de Santiago pilgrimage ends in the Spanish province of Galicia, believed to be the resting place of St James the Apostle. This has been a spiritual trail for pilgrims since medieval times and it has no real starting point. Rob thinks of his trip in thirds:

“The first third is one of physical exhaustion, or getting our bodies into its rhythm. The second third is about ‘letting go’, while the final third is about understanding what El Camino has taught us. I like this, not because I look forward to the final third, but because I too am learning to let go of certain things.”

This journey of self-discovery took a remarkable twist, as Rob describes in this extract from his blog (which can be followed here):

“As I entered this little stone chapel, I noticed it wasn’t a church after all, but a shrine. I asked the gardener to whom it was for, and he answered it was for Archangel Michael. Perfect, I thought. A place to pray for family and friends fighting for health.

A few hours later, I received a message from my brother-in-law in Lima, Peru. He said a few hours earlier, my 92-year-old mother’s heart just stopped. My beautiful mother, Norah Salkeld de Prugue, passed away on the morning of 24 April 2018 in Peru.

I now realise that my being compelled to enter the little stone chapel was no coincidence. My mother’s soul was speaking to me, asking me to come in to say goodbye. While my prayers were for family and friends, I interestingly enough did say an extra-long one for my lovely mother.

I still cannot believe this. As I later entered into Carrion, my final destination today, I immediately went to the lovely church, said a prayer, and lit a candle. A sister saw me weeping and asked if she could help. I told her the story and she said she would speak to the local priest. The nun made sure the evening service was in my mother’s honour. The priest and the town congregation were so very kind in giving that service in her name. The town people all came around to wish their sympathies. Truly generous hearts here in rural Spain.

Before you roll your eyes, I appreciate this is likely a coincidence. But perhaps, just perhaps, it’s my mother suggesting I continue and finish this 500-mile walk.” 

Then a few days later, this update:

“Clearly the Camino must think I’m one bad ass as only hours after my pulling myself up from my mother’s funeral half a world away, I learned that my sister-in-law, Paloma, had just passed away following her 13-year battle with breast cancer.” 

It's turning into quite a journey.

Earlier, Rob had sent me this email:

“Oddly enough, as well as reflecting on life, my reflections have been on superannuation. A recent article in The AFR about industry funds got me going. Here’s my thoughts from El Camino.”
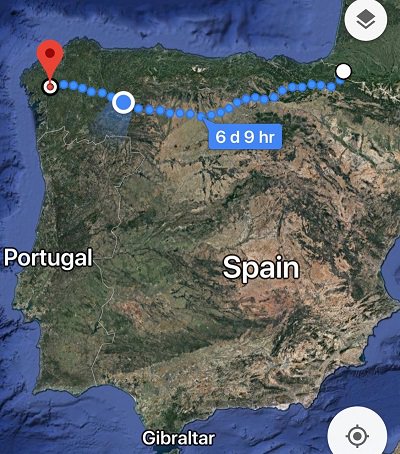
As at 4 May, Rob had walked 590 kms, with another 210 to go. He's due to reach his destination by 11 May.

Superannuation: it should not be 'us versus them'
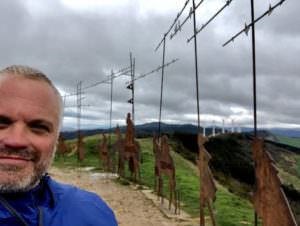
Coming to my second month of my three-month sabbatical, and now 200 kilometres into my 800-kilometre Way of St James (the Camino) here in Spain, I was hoping to find some sort of spiritual self-fulfilment through my daily routine of 30,000 steps. And while on this self-introspection, it took an opinion piece in The Australian Financial Review on 11 April 2018 titled Why Industry Funds Are Not So Super to remind me just how much superannuation is a part of me.

As Al Pacino said in Godfather 3, just when I thought I was out, they pull me back in!

Peer rankings useless for superannuation

What bothered me most was less the continued division between industry and for-profit super providers, but the continued focus on peer rankings. In all my years of learning and working within superannuation, I have yet to find ANY academic book which suggests that the best way to immunise a pension liability (i.e. matching future assets to future pension liabilities) is by choosing a top quartile performer.

And while of course it’s true that returns do matter (to be precise, net of fees and net of taxes), pension liabilities are acyclical whilst asset returns are cyclical and subject to market forces. Peer performance rankings, therefore, are futile within superannuation.

Funds in net outflow compounds problem

This bee in my bonnet is equally founded on demographics, as an increasing number of both retail and industry funds are experiencing net outflows given baby boomers have already begun to retire. Once retired, pension immunisation is all the more important. The ability to forecast steady cash outflows off an increasingly cyclical economic environment is paramount in planning retirement years. Yet, the media and agents remain consumed on metrics that play no part in pension management. Perhaps this is due to the fact how within the financial services industry, wealth management is itself a big component therein.

Whatever the reason, superannuation is not wealth management, it’s about optimising assets around returns required to immunise pension liabilities. Pure wealth management, on the other hand, cares little about asset/liability immunisation.

Let’s move beyond political name-calling

My secondary beef is the obvious political affiliation intended behind their defining what is an ‘industry fund’ and what is a ‘for-profit fund’. Calling an industry fund a ‘union fund’ is naive. I neither belong to a union nor do I belong to a party, yet I have my super within a so called ‘union fund’. Having attended conferences run by both sides, I’ve always rolled my eyes when discourse turned to political affiliations. Who cares? If super fails, it will affect ALL tax payers as neither party will allow its retired voters to live in the streets. How we tax any fund may be politically aligned, but their policy for superannuation should be nonetheless apolitical.

I pose this piece not to continue to divide, but to hopefully remind us to challenge anyone who feels it necessary to divide superannuation funding into an ‘us versus them’ debate. What defines our industry isn’t ‘for profits vs not for profits’, but superannuation itself. Sadly, both sides are guilty of this division, and equally, both sides will need to come together if we are going to achieve our true purpose.


Rob Prugue was Senior Managing Director and CEO at Lazard Asset Management (Asia Pacific) for 15 years until March 2018. These opinions are his own.


  •   3 May 2018
  • 3
  •      
  •   
3 Comments
Rod
May 03, 2018

Lovely to read and how valuable it is to get out of the usually stressful work routine and do such a walk... useful to be reminded that behind life and death is a BIG mystery!
Then perhaps we can come back to the old routine with a deeper insight, even a detachment, and perhaps do a better job overall.

Steve
May 05, 2018

David Whiteley would be thrilled by such comments. Meanwhile, out here in the real world, a lot of advisers are quite rightly sceptical about the tight relationship between asset consultants & industry funds (who direct members funds to Unions, unlike their competitors).

Maria
August 25, 2018

No, industry funds do not direct or syphon funds to unions as you suggest. What happens is that some directors are employee organisation nominated. These directors are paid directors fees, along with the employer nominated and independent directors. Once directors receive their directors fees they are free to do what they wish with the money. Some directors then give their fees to their affiliated trade-union or guild. It is their fees they receive and they are free to do with it as they wish, just as employer nominated directors are free to do as they wish with their directors fees.
Some employee nominated directors give their fees to the sponsoring trade unions, others keep the money. It is money they receive for performing directors duties, so why shouldn't they be allowed to hand it over to their sponsoring union, if that is what they choose?


Leave a Comment:

RELATED ARTICLES

What Australian super funds can learn from the UK

On franking, all public funds are not the same

Not all lifecycle funds are created equal

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.