Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 666

The most important investment decision you’ll ever make

I used to believe the process of investing was all about selecting the right stocks, locking in a great return, rinse and repeat. Stock picking intuitively aligns with the way many people imagine investing works. While it might be easy to blame the glamour of Scorsese’s Wolf of Wall St, most financial commentary tends to focus on individual companies and quirky market personalities. It’s certainly more entertaining to read about what Elon Musk has said this week than to dive into the merits of Modern Portfolio Theory.

In reality, the most important investment decision you’ll ever make probably won’t be that speculative small cap bet or the hot stock tip your neighbour was talking about. It is far more fundamental than that.

Your asset allocation decisions will always be the biggest driver of long-term returns, and therefore your investment success. One of the most cited studies in modern investing is Determinants of Portfolio Performance by Brinson, Singer, and Beebower (1991). The research estimates that asset allocation explains 94% of a portfolio’s return variability over time. Your mix of growth and defensive assets will dictate not only long-term returns, but also how you align your investment strategy to your goals and manage risk appropriately.

Why it matters

If investors could look into a crystal ball and be told which asset class was going to outperform each year, asset allocation decisions would be easy. But this is far from reality. There is a degree of randomness inherent in determining which assets perform best on a short-term basis.

The chart below demonstrates how difficult it is to consistently pick winners and losers. Allocating capital across a range of asset classes helps investors avoid anchoring their portfolio to a single narrative.
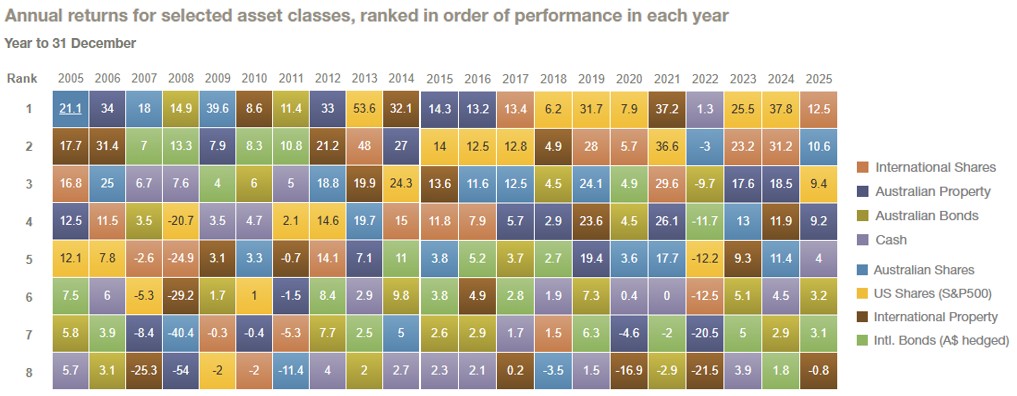

Source: Vanguard Asset Class Tool.

But most retail investors don’t ponder correlation metrics over breakfast. They’re focusing on outcomes like purchasing a home, generating a steady income or retiring comfortably. The fuss over asset allocation is justified. It is the primary mechanism that turns goals into a sound investment strategy.

For instance, a long-term goal e.g. a comfortable retirement with decades to run, means an investor may allocate higher exposure to growth assets. On the other hand, if an investor is looking to purchase a home in the next three years, they may favour a larger allocation to defensive assets to manage risk and achieve this goal.

The subtle differences

Many casual investors demonstrate lower levels of engagement with their asset allocations, especially when it comes to super. For example, AustralianSuper currently has over 90% of members in the balanced option, which targets a 75/25 split between growth and defensive assets. Given the average age of an AustralianSuper member is around 42, one could argue that a significant portion of investors may be positioned more conservatively than their time horizon requires.

Even small differences in allocation can compound into surprisingly large gaps over time. No allocation is inherently ‘wrong’, but it may not be optimal for every investor and the cost of being misaligned can accumulate over decades.

The key point is that your allocation should be an intentional decision that reflects your goals, risk capacity and ability to withstand short-term fluctuations. Most investors will need some level of equity allocation to achieve their long-term goals, but determining the ‘right’ level will be highly personal.

The part investors often miss

There is no perfect formula to determine your asset allocation. Traditional frameworks can provide useful guidance, but they cannot fully capture the personal nature of the decision.

An overlooked implication is that market dynamics are constantly shifting. The risk profile of asset classes and the correlations between them are not static. But that doesn’t mean investors should attempt to time the market. Instead, it highlights the importance of understanding how the landscape has evolved.

I believe The Callan Institute illustrates this point well. Their research suggests that investors are required to take on almost twice the risk they did 30 years ago to achieve a nominal 7% expected return in the next decade.
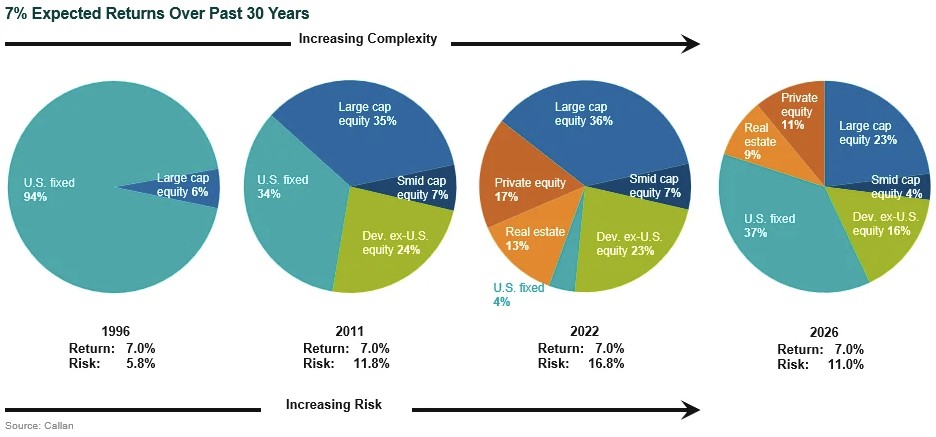

Source: The Callan Institute. 2026.

Although, the report notes that the mid-90s were uniquely characterised by not only higher fixed income yields but also higher inflation. To adjust for this, researchers looked at what it would take to earn a 5% real return instead. The figure below shows that the conclusion remains similar.
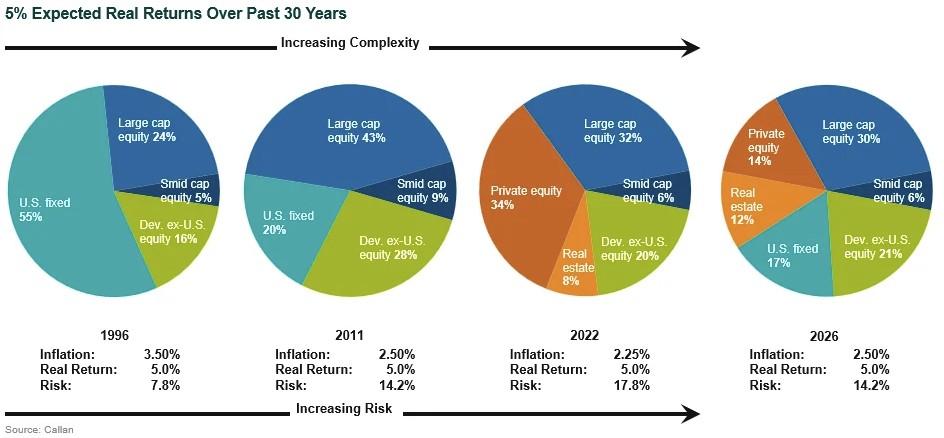

Source: The Callan Institute. 2026.

Market dynamics don’t just change over the long-term either. The environment has shifted even in the last few years. Achieving a 7% expected return is now far more feasible than it was in 2022. Back then, an investor would have needed to allocate ~96% of their portfolio to growth assets to reach 7%. In 2026, Callan believes over a third of a portfolio can sit in fixed income whilst still maintaining the same expected return.

The broader takeaway is that the mix of assets required to meet return objectives evolves over time. Investors today face an increasingly complex landscape. It is difficult to set an asset allocation and expect it to remain appropriate in the long-term.


Simonelle Mody is an Investment Specialist at Morningstar Australia. She writes for retail investors and financial advisers on topics spanning portfolio construction, market trends, ETFs and investor behaviour. 


  •   9 June 2026
  • 3
  •      
  •   
3 Comments
Lauchlan Mackinnon
June 11, 2026

I completely agree with you that asset allocation is the most important investment decision we can make.

I think your point that "There is no perfect formula to determine your asset allocation" is a profoundly important point that deserves much more attention in investing education, and it's great to emphasise it here.

There is one point I'd like to explore and expand on though, and that is the investment time horizon.

A lot of discussion of investments looks at which asset classes, or specific stocks, are performing well this year or performed well last year. The Vanguard chart is providing data long those lines.

But as you point out, that is not really relevant to investors with longer time frames. You give two examples:

"For instance, a long-term goal e.g. a comfortable retirement with decades to run, means an investor may allocate higher exposure to growth assets. On the other hand, if an investor is looking to purchase a home in the next three years, they may favour a larger allocation to defensive assets to manage risk and achieve this goal."

Discussion of asset allocation is kind of meaningless without the context of that investment time horizon.

And if we do have that context, then a lot of issues become simplified. For example, the Vanguard 30-year performance chart at https://fund-docs.vanguard.com/AU-Vanguard_Index_Chart_poster.pdf makes clear that over the long term shares outperform bonds. Therefore the role of bonds in a portfolio like 60/40 or 70/30 is largely to dilute growth, in order to reduce volatility. But the goal of the portfolio is growth over a particular investment time horizon, not low volatility at any given time. So as long as the investor can handle volatility by other means (for example a significant cash reserve so that they never need to sell, or by understanding market cycles and that down cycles are buying opportunities), then some of the mainstream asset allocations such as 60/40 simply have no real value to an investor in the accumulation phase with a long investment horizon. That's before considering the erosion of the historical "non-correlation" between stocks and bonds.

Similarly, we could look at shares by region. US shares clearly outperform both Australian and International shares over 30 years, but the story over shorter time horizons is more ambiguous. That invites a closer study of what's driving the US, Australian and international economies and what the patterns and cycles are over time.

Along sector lines, if we look at long-term performance of US stocks, there's a difference between the S&P 500 and the NASDAQ. The NASDAQ typically outperforms the S&P 500 over the long term, and the reason is, presumably, that it contains high-growth tech stocks. That insight may be a useful input to an asset allocation decision, for a long-term investor.

At the end of the day, what matters is the purchase price and sale price of the asset, not the variations along the way. And that's driven by long-term performance of asset classes. :)


Mark Hayden
June 13, 2026

Risk should not be defined as volatility. If part of your funds (part of your bucket) will not need to be sold for many years, then that portion can (and should) be prepared to accept negative returns over certain periods. Correlations over short to medium periods are unhelpful. In fact they lessen the long-term returns.


Leave a Comment:

RELATED ARTICLES

When defensive assets become indefensible, turn to tech

Clime time: Asset allocation decisions for SMSFs

The 60/40 Portfolio – saying bye to old friends and welcoming new ones

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.