Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 379

When defensive assets become indefensible, turn to tech

The appeal of owning traditional defensive assets of any type is currently less than in almost any other period in history. In fact, in this extremely low rate environment, we are seeing just how unattractive traditional defensive assets can become. 

But despite the serious headwinds facing defensive assets, investors started moving billions into these safe havens well before COVID-19 struck, as many feared equity markets were toppy and it was late in the economic cycle. This may have proven a saviour for some investors in March 2020.

A redefinition of what is defensive

In the flight to safety, many investors took their medicine even though the cash rate was at an historic low, term deposits above 1% were rare and incomes from investment grade bonds had plummeted. The riskier high yield bonds broadly tracked the share market which calls into question their raison d'être as they do not have the desired defensive qualities in a downturn.

With income generation previously a major drawcard for a defensive allocation, many investors have realised they can no longer rely on an income of 5-7% a year and are having to rethink their future. Or at least change their investment strategy.

It is time for investors to broaden their approach to defensive investing and take a closer look at defensive sectors, rather than just the asset class.

To look only at defensive asset classes is a narrow view of the investment universe. This fails to take into consideration one critical factor that impacts the success or failure of the underlying companies, and that is the sector in which they operate.

For those more sophisticated investors who already take a sector approach to portfolio construction, it may also be time to look outside the usual suspects of consumer staples, healthcare and utilities, where demand for these goods and services are relatively inelastic and as a result they perform relatively well in a downturn.

Technology has joined the defensive club

During this pandemic and early days of the economic recession, we are seeing a surprising new entrant to the defensive sector grouping. Technology shares have been behaving a lot like defensive shares such as food and utilities.

The S&P/ASX 200 is down 12.6% since February 2020, while the S&P ASX All Technology Index, a broad index of technology companies, is up 30%. Over the same period, the S&P500 is up nearly 8%, while the NASDAQ, the home of many technology companies, is up over 25%. This is not a fluke. See the chart below for a comparison between the NASDAQ, S&P 500, and DJIA.

DJIA v S&P 500 v NASDAQ
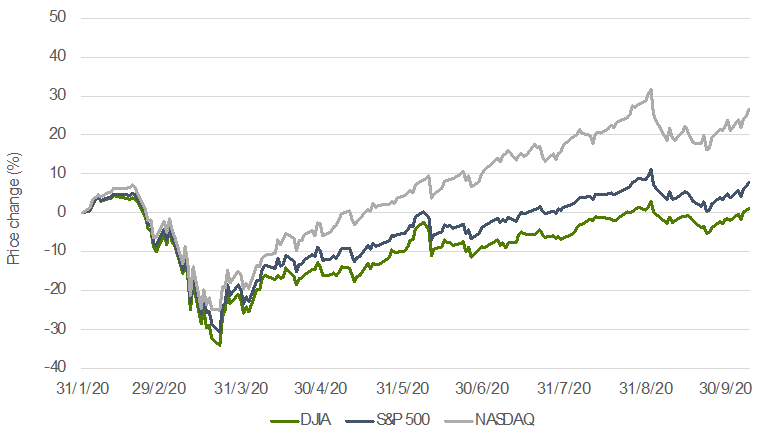
Source: S&P Global

Technology is holding its own and providing investors with a defensive position in this time of great uncertainty, with the NASDAQ fuelled by the strong revenues and forecast growth rates of many of its technology companies.

The reasons are plain to see, not least because technology has been the lifeline for individuals and businesses during lockdown. In the US, a recent Fortune 500 CEO poll found that 75% of companies plan to increase spending on technology.

So while the NASDAQ suffered a fall in September due to investors reducing their valuations for companies such as Apple and Tesla, and further exacerbated by the number of equity derivates involving both retail investors and SoftBank, the index has stabilised (and recovered) recently. Their traditionally higher valuations can be attributed to drivers such as high margins, growth rates and their ability to be agile in adapting to consumer and businesses changes caused by COVID-19.

History has proven that technology thrives on shocks. These are events that are, by and large, unexpected and bring out changes in real economic growth, inflation and unemployment.

There has been no greater shock in a generation than COVID-19. This is a shock that will have lasting effects and technology will exacerbate the impact on certain sectors and force changes that allow businesses to survive. COVID-19 has accelerated innovation in sectors including ecommerce, cloud computing, gaming, streaming and remote communication such as videoconferencing.

Technology is a deflationary force

Investments in technology by companies are made to reduce costs, increase profits and improve efficiencies. It is difficult to imagine that any business will reject technology that enables them to produce more product, more quickly and ultimately make larger profits.

Investors are already shifting away from the today’s sunset industries and hedging with investments in technology. As a resource economy, it has been difficult to avoid investing in large mining companies but the shape of our economy is changing. Some commentators have suggested that COVID-19 has hastened the slow passing of the oil age and is driving an increasing focus on sustainability generally. Technology drives this sustainability.

Investors taking stock of tech opportunities

Investors will undoubtedly be taking stock and assessing their investment portfolio as the world waits and watches to see what happens next in these strange times. With tech shares currently trading at high multiples, we can expect investors will look across the spectrum of tech investment opportunities. Venture capital funds are sought after as investors seek exposure to early stage tech businesses in what is ultimately a long-term game plan.

Technology has never been more important. This holds true in daily lives, in business and in the global economic recovery. When times are tough, corporates slash procurement costs, automate procedures and optimise back-office efficiencies. Technology delivers on all of these fronts. In better times, we can expect to see high growth tech businesses continuing to innovate and bring new products to consumers and business.

With a greater focus on defensive sectors rather than poor-performing defensive asset classes, investors may just be able to have their cake and eat it. A strategy that is both high growth yet defensive, supporting economic recovery and creating an economy of the future.


Benjamin Chong is a partner at venture capital firm Right Click Capital, investors in high-growth technology startups. This article is general information and does not consider the circumstances of any investor.


  •   14 October 2020
  • 5
  •      
  •   
5 Comments
Alex
October 14, 2020

Never thought I'd see the day when growth stocks with P/E north of 30 were called defensive. May they grow forever, or until they are themselves disrupted. TikTok anyone?

Brett
October 14, 2020

It's one thing to explain the benefits of a sector, like Tech. To claim this sector is a defensive by handpicking one example to make your point is concerning. Tech in 2000 underperformed; tech underperformed the initial recovery from the GFC - it all depends on the circumstances (a pandemic forcing people to stay home is obviously tech friendly).

Tech investments, to use your examples Apple and Telsa, sell products that are non-essential. Therefore, at some point in the future the earnings of these companies will likely act in a non-defensive manner. Utilities and healthcare are essential items that have provided relatively more stable earnings profiles.

I'm not discounting your ability to pick great investments within the sector. I disagree with your claim that the entire sector is a defensive asset.

Brendan
October 15, 2020

Couldn’t agree more. Well said.
The article read more like a sales brochure than analysis.
Be good at what you do, but don’t pretend you’re something you’re not.

Vince
October 14, 2020

Technology is the future and the future is here. The dot com bust in 2000 happened in my view, because tech wasn’t yet mature. Just look around and you can see technology is entrenched in just about everything we do. However, there will be winners and losers. That’s just natural.

Trevor
October 17, 2020

This honestly reads like a VC sales pitch and is a poorly thought out thesis about defensiveness being intrinsic, whereas it is so more likely incidental. Tech is not intrinsically defensive, it was incidentally defensive because of the particular circumstances created by this very particular crisis. The pandemic itself was tech friendly, retail investor mania has fuelled their price growth called and cheap money and MMT has been highly supportive of the sector. If you are relying on money printing, low rates, retail mania and everyone locked up at home for a stock to be defensive, than good luck in the next crisis, which will have its own flavour. Let's see how these stocks fare in a crisis induced by taking the foot off the monetary pedal or indeed anything that hits momentum.


Leave a Comment:

RELATED ARTICLES

The most important investment decision you’ll ever make

Clime time: Asset allocation decisions for SMSFs

The 60/40 Portfolio – saying bye to old friends and welcoming new ones

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.