Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 223

Understand the retirement income challenge

Recent research on over 5,500 senior Australians showed most are aware of their increasing longevity, but there were some surprising findings into retirement expectations. National Seniors Australia (NSA) and Challenger surveyed a broad representation of NSA members. Regular, constant income covering essential needs came out as the major requirement in retirement, but other results were less predictable.

Limited intentional bequests

While Treasury officials might be worried that older Australians are looking to build up a tax-free super nest egg and pass it all onto their kids, that is not the motivation for older Australians. Only 3% of respondents indicated that they intended to preserve all their capital for the next generation. These are probably wealthy older Australians who can afford to live off the income from their assets, rather than having to draw down the capital.

This doesn’t necessarily mean that senior Australians have turned stingy. Indeed, the split was roughly even between those leaning towards preserving capital and those looking to spend it down. Only 10% want to spend down everything. In practice, it seems that retirees are not spending it all (at least not yet).

So, what is driving the observed behaviour?

Understanding the implications of longevity

The survey highlighted that most retirees are aware of their increased longevity. 83% reported an awareness of a likely 6-year increase in life expectancy compared to their parents’ generation. 49% reported making financial plans for retirement and 47% have plans for medical and health expenses. These are all signs that Australian retirees are aware of the need to manage for longevity.

This awareness could also indicate why they don’t think they will be leaving money for the kids. They’re not sure that they will be able to afford it.

Living longer means that retirees will have to fund their spending for longer and it is probably more that the retirees are looking after themselves first. Only if they don’t need it will they leave something for the kids. Comments from individual respondents reflected the theme that kids are in a better place than current retirees, potentially due to the existence of superannuation (i.e. they already have their own retirement savings).

In terms of planning, making sure that they have income for the rest of their lives was a high priority, but it wasn’t what they were most concerned about.

Preference for regular income

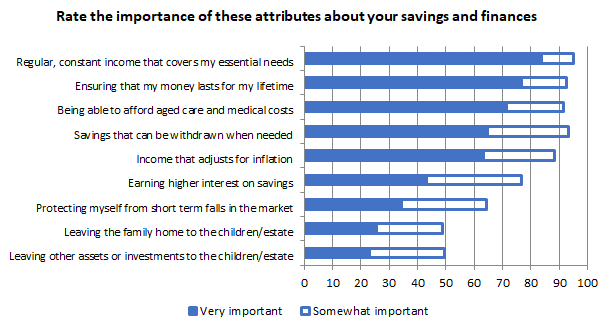
Top billing in this year’s survey went to the need for regular income to meet essential needs. A previous survey in 2012 had ranked money for health costs as the top priority, but a broader focus, that includes other essential needs, topped the list this time.

The chart below indicates the key concerns that seniors have around their finances. While lowest ranked, many still consider it important to leave an estate, suggesting it is more about the capability, rather than the intention, that is likely to limit what the average Australian retiree will bequest.
Seeking financial advice

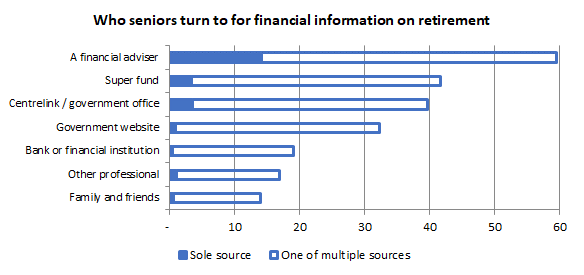
Another element of the report that might surprise was the high number (59%) who reported using a financial adviser. With around 160,000 households retiring every year, this suggests that there are around 100,000 pieces of advice (or information) from advisers about retirement. This might seem a little high, but it includes some limited advice (including general advice). Based on other surveys, it’s likely that less than half of them maintain an ongoing relationship.
With a growing number of baby boomers set to retire in the coming years, the demand for quality advice will only increase. With the increase in goals-based advice strategies, the report also gives some pointers about the key goals for retirees.

In summary, beyond the timing of the next overseas trip, the key goals are to generate a regular stream of income to meet essential spending and meet health and aged care costs later in life.

It would be hard to argue an adequate goals-based plan has been developed if it does not include solutions to meet each of these goals for a retiree.


Aaron Minney is Head of Retirement Income Research at Challenger Limited. This article is for general educational purposes and does not consider the specific circumstances of any individual.


  •   19 October 2017
  • 4
  •      
  •   
4 Comments
Ashley
October 18, 2017

I see that only 3% of respondents indicated that they intended to preserve all their capital for the next generation, but what if the question were: “Do you intend to preserve PART, or a substantial part, for the next generation?" You might get a different story.

Aaron Minney
October 19, 2017

Hi Ashley
That was covered by the question in the report which is available from the National Seniors Australia website (https://nationalseniors.com.au/be-informed/research/publications/seniors-more-savvy-about-retirement-income).
The responses to the question split down the middle between spending most/ all or preserving some/ all (51/49).
An inheritance was also the lowest ranked priority with 23% viewing it at very important to leave something to the next generation.
While it is important to many (certainly not all), there was a strong suggestion that they want to spend their money on themselves first, and the estate was a residual rather than an explicit objective.

Jack
November 23, 2017

If life expectancy is such that many people are now living until age 90, it is likely that their children will be in their late 50s or early 60s when they inherit.

In that circumstance it is debatable how much of a helping hand from their parent's inheritance these children will need at that age.

Graham Hand
November 23, 2017

Completely agree, Jack. I think that's why 'The Bank of Mum and Dad' is such a major factor in the property market. If you have the money now and plenty for the future, what's the point of your kids inheriting the money when they are 60, after they've struggled when they were 30 to 40 to pay off the mortgage on a modest home while bringing up a family and holding down two jobs. Then the kids leave home and they don't need the money. Better, if possible, to give a chunk to them at age 30 and let your extended family enjoy a better quality of home. I'm not saying you make life easy for them, but $500,000 buys nothing in Sydney.


Leave a Comment:

RELATED ARTICLES

It's not a shock that retirement is different

Super was built for a very different Australia

Super is catching up, but ageing is a triple-threat

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.