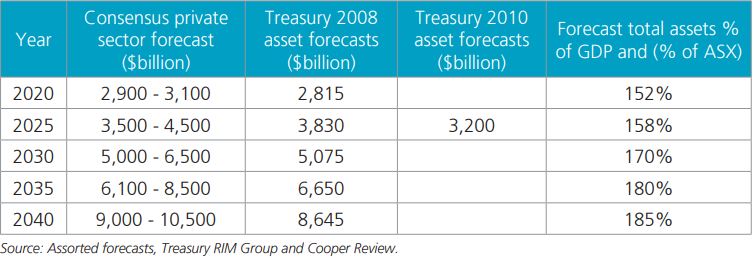
Sometime in the next year, if there is no major market fall, total assets in superannuation will hit $3 trillion on the way to a forecast $10 trillion in 20 years, as shown below. Not bad for a country with GDP of about $1.9 trillion. The entire market value of all listed companies in Australia is about $2.1 trillion. While super funds obviously invest in a wide range of other asset classes, super investments will increasingly move offshore.
Projected superannuation assets, 2020 to 2040
Source: Association of Superannuation Funds of Australia
Already, this is making a major contribution to Australia's current account balance, which recently went into surplus for the first time in 44 years. With foreign equity holdings reaching $1.5 trillion, Australian investors now hold a record $141 billion more foreign equities than the amount of Australian equities owned by foreigners. AustralianSuper holds 44% of its assets overseas, or $76 billion, a doubling in five years. It contrasts with the heavy home bias in SMSFs.
Does history really repeat?
A phrase commentators love to trot out in its many variants is, "Those who cannot learn from history are condemned to repeat it." It's in contrast to, "This time it's different." One reason history might not be much of a guide to market behaviour is that we live in an age of automated trading driven by algorithms. History did not have powerful computers obeying quants.
Take the case of people arguing that the inverse yield curve is a sign of impending recession. A trader-friend offers another theory. In the US, borrowers can repay fixed rate mortgages without penalty. As rates fall, they refinance into lower rates, which means mortgage-backed securities are repaid at a much faster rate than expected. Large insurance and pension funds hold these assets against long-term liabilities. As the mortgage bonds are repaid, algorithms automatically buy longer-dated bonds to manage the maturity mismatch, driving down long bond rates.
Other factors suggest history offers no guide. Former Federal Reserve Chairman, Alan Greenspan, thinks the yield curve will continue to invert due to changing demographics. He said recently: “An ageing population is driving demand for bonds, pushing their yields lower.”
In this week's packed edition
Last week we showed how the Future Fund is investing in different fixed income assets, including peer-to-peer lending. Continuing our Interview Series, Daniel Foggo, the CEO of RateSetter, explains how 'marketplace' lending works, with some surprising insights. He thinks of his business as a fund manager for the large asset class of consumer finance.
While there is no doubt the financial advice industry needed to fix clients' best interest duty, an unwelcome consequence of the Financial Services Royal Commission inquisition is that full-service advice will increasingly be confined to wealthier people. On Tuesday this week, the Ending Grandfathered Conflicted Remuneration Bill 2019 passed which bans commissions paid to financial advisers from 1 January 2021, only 15 months from now. Many advisers will not survive this change.
Treasurer Josh Frydenberg's announcement said:
"Grandfathered conflicted remunerations can entrench clients in older products even when newer, better and more affordable products are in the market. Ending the payment of grandfathered conflicted remunerations will remove this inherent conflict and restore trust in the financial advice industry."
No mention of what new business model is supposed to pay for compliance-heavy and complex financial advice, because the majority of people cannot afford it. We ask if FoFA now stands for Failure of Financial Advice, and jump into the comments section if you have a view.
Peter Thornhill has a big following among our readers with his unconventional approach to asset allocation. He argues that chasing dividend yields is the wrong approach to finding income.
SMSFs are coming under increasing regulatory scrutiny. Graeme Colley provides a detailed checklist for trustees to review whether they are risking non-compliance and their tax status.
Investors need to watch that they are not buying into a company at the very peak of its growth, just as it enters a flat period. Nick Griffin describes how watching the S-curve works.
The Governor of the Reserve Bank, Philip Lowe, has warned the Government that interest rates can't do the heavy-lifting for the economy, and more fiscal stimulus is needed. July retail sales fell 0.1% despite recent rate cuts and tax refunds. He told a group of central bankers in New York:
"We can be confident that lower interest rates will push up asset prices, and I think that later on, we will have problems because of that."
It's timely that Michael Collins reviews the declining influence of interest rates and central banks.
The decline in the Australian dollar in the last year has boosted performance of foreign assets, and Gofran Chowdhury looks at the merits of holding cash in a foreign currency.
Finally, Peter Rae explains how many LIC's are struggling to remove their large discounts to NTA, as well as reviewing the latest new transactions in the market.
This week's White Paper from Legg Mason is 'Solving for the Retiree Problem with Innovation' and looks at research and philosophy for retirement income assets.
Graham Hand, Managing Editor
For a PDF version of this week’s newsletter articles, click here.