Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 323

The merits of holding some cash in US$

In the past decade the value of the Australian dollar has dropped more than 35% against the world’s most important currency, the US dollar. Since the start of 2018 the Australian dollar has declined 18%, a significant enough fall to have real impacts on investments and prices.

A clear impact is on travel. If you were planning to buy US dollars for your travel needs a decade ago and converted A$5000, you would have received about US$5,350 in your pocket. Today, those same savings will only be worth about US$3350.

Your exposure to currency

The direction of a currency has other significant impacts unrelated to travel yet important to your purchasing power and even your overall wealth. For instance, we purchase a lot of overseas goods, including food, cars, fuel, clothing and electronics.

When our dollar is down, retail prices for those goods tend to rise, as importers usually pass on the added costs to end customers.

The ebb and flow and interdependence of global trade has made foreign exchange the world’s largest financial market, with more than $US5 trillion a day worth of currency exchanged. In Australia, nearly $120 billion of currency changes hands every day and its growing rapidly.

There are several factors driving forex growth in Australia, including increased inbound and outbound travel, a growing number of foreign students undertaking study in Australia, and new migration.

Given the sheer size and pace of growth in this market, it is surprising that more Australians are not attuned to the implications of currency movements on their hip-pocket.

How can you do more with your cash?

Australians hold a large portion of their wealth in cash and, not surprisingly, specifically in Aussie dollars.

When investors do this, they expose their portfolio to substantial downside risk.

A portfolio, with only Australian-focused assets, is dependent on the outlook for the local economy. If our economy has a downturn, a localised portfolio will take a similar or even greater hit.

Currently, this risk is heightened, with the outlook for the Australian dollar uncertain because of low wage growth, low inflation rate, a softened housing market and issues relating to trade wars and markets.

By holding different denominations in overseas currency and investments in a portfolio, investors can spread risk across different geographic regions.

This can potentially smooth out investment returns over the long term, as Asia, the US and Europe will follow divergent growth paths.

During the GFC, for instance, when developed countries saw their growth downgraded, Asian economies scraped through relatively unscathed.

A currency's importance in the global economy will also determine how it’s affected by internal and external events. The US was one of the countries hardest hit by the GFC and yet its dollar actually appreciated.
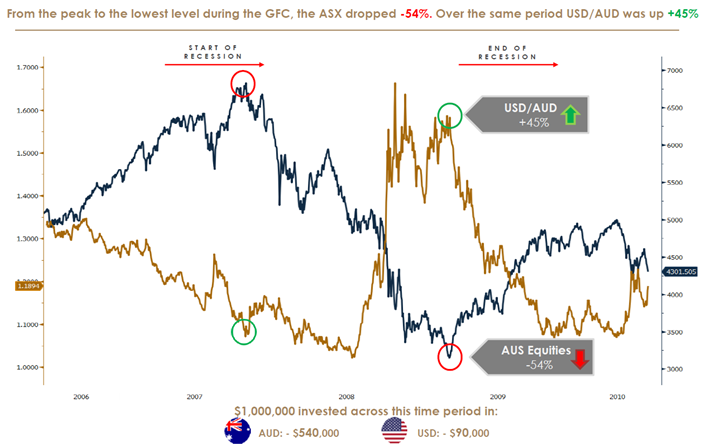
As the globally-recognised reserve currency, the US dollar is what’s known as a ‘safe haven’ currency, meaning people buy it if they are uncertain of the direction of less globally-important currencies, like the Australian dollar.

So money often flows into US dollars in times of uncertainty. Even if the US economy suffers a shock, the US dollar can still remain strong.

This compares with the Australian dollar, which can be sold off aggressively in times of risk.

The Aussie dollar's value is tied to its dependence on the export of minerals, gas, agriculture and bulk commodities, such as iron ore, bauxite and coal.

Earnings on cash

The cash rate is another factor to consider when looking at currencies. If we look to next year, if you hold Australian dollars in 2020, the cash rate may be around 0.50%. If you hold US dollars in 2020, the cash rate may be around 1.50% to 1.75%. Both of these levels factor in a further two predicted rate cuts in Australia and the US. 

While holding cash in different currencies may seem difficult, recent digital advancements have made this a relatively-straightforward option for ordinary Australians. Locally, international banks and fintechs have good options for customers to keep their money in a variety of currencies.

However, people still need to do their research to ensure they are choosing an option that best suits their needs, paying particular attention to any hidden fees.

Depending on the situation, this could just relate to holding currency or perhaps doing more with it such as buying foreign currency bonds. We are seeing a trend among our high net worth clients where they are buying US$ as a safety proxy, and then investing in high quality US dollar bonds. Year-to-date, we’ve seen a 36% increase in US$ bond purchases.

For investors and savers alike, managing currency exposure within a portfolio is an important part of a wealth management plan. It can both protect and enhance returns while improving risk management.


Gofran Chowdhury is Head of Investment Specialists at Citi Australia, a sponsor of Cuffelinks. This article is general information and does not consider the circumstances of any individual.

For other articles by Citi, see here.


  •   11 September 2019
  • 1
  •      
  •   

RELATED ARTICLES

Four foreign exchange secrets for travelers

ASIC warns retail investors of dangers in FX trading

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Latest Updates

Retirement

The retirement account that Australia should have

Our retirement system asks one account to do two very different jobs. A dedicated "rainy day" account separating income from emergency savings could deliver better outcomes and greater peace of mind for retirees.

Investing

What the US midterm results mean for investors

Democrats have regained control of Congress, changing the equation in Washington. Whether that proves positive for investors will depend less on the result itself and more on what happens next for growth and markets.

Taxation

Should the capital gains tax reward risk?

A reader query on the recent CGT reforms has revealed a bigger issue. One overlooked feature of the old system may have done more than compensate for inflation. As we move to indexation, are we forgetting to reward risk?

Investment strategies

Bonds: The income and diversification trade-off

Rising yields have made bonds attractive again, but that does not mean they will behave as expected. As inflation, fiscal pressures and geopolitical risks reshape markets, the role of bonds may be more complicated than it appears.

Investment strategies

Why high-dividend investing deserves another look

Income investors have endured several lean years, but signs of a recovery are emerging. As opportunities improve, investors face an important choice between chasing headline yields and building a reliable source of income.

Investment strategies

Why 'overvalued' has been such an expensive word

Investors love simple rules, especially when markets appear stretched. Yet some of the strongest returns have arrived when the outlook seemed least attractive. This leaves an important question that history struggles to answer.

Investment strategies

AI – A good kind of bubble or just a bubble?

Investor obsession with AI is attracting unprecedented amounts of capital and confidence. But beneath the excitement lies uncertainties about returns, funding and risks that enthusiasts may not be paying enough attention to.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.