Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 344

Welcome to Firstlinks Edition 344

There's always more happening in money markets than most people realise, with significant implications for investors and borrowers. Like an iceberg with more under the surface than we see from above, the Reserve Bank of Australia (RBA) injects or withdraws billions of dollars into the financial system each week to manage liquidity. In the professional cash markets, the RBA is currently providing plenty of stimulus and banks are funding loans easily.

This lack of need to compete aggressively for deposits is one reason why bank cash accounts pay negligible returns and term deposits are not much better. Worse for people relying on these accounts for income, Governor Phillip Lowe has outlined the circumstances in which cash rates could go lower.

"If the unemployment rate were to be moving materially in the wrong direction and there was no further progress made towards the inflation target, the balance of arguments would tilt towards a further easing of monetary policy."

Lowe went on the explain the requirements for an Australian version of Quantitative Easing (QE), where he appeared to rule it out:

"The threshold for undertaking QE - that is, the RBA purchasing assets through balance sheet expansion - has not been reached in Australia and I do not expect it to be reached. So, it is not on our agenda at the moment."

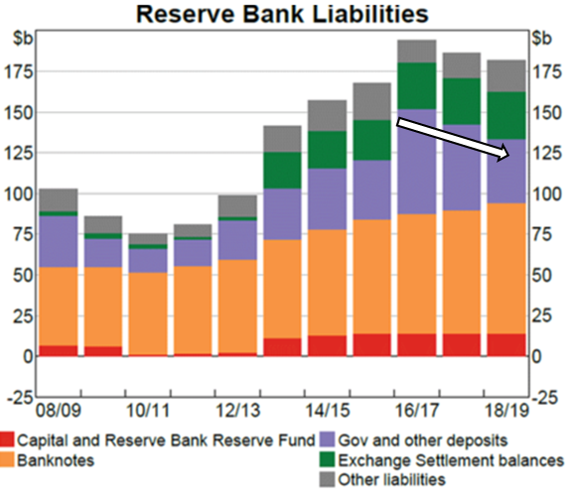
However, Peter Sheahan, an institutional deposit broker at Curve Securities, told me that a form of QE is already underway. He points to the level of Government deposits held by the RBA (the purple bar in the chart below). It has been falling rapidly as Government agencies appear to be circulating money back out to the financial system as soon as possible and not holding deposits with the RBA. The amount on deposit has fallen a further $23 billion from $41 billion to $18 billion since 30 June 2019. Some banks believe there is already more liquidity in the system than ever before and it's one reason the RBA did not cut rates last week. It's "cash flow optimisation to stimulate activity."
Nobody has spent more time in Australian money markets than Tony Togher. He oversees the $60 billion cash and fixed interest portfolio at First Sentier Investors for both retail and institutional investors. In this interview, he explains the wide variety of securities in his funds, and how the market has changed fundamentally in the last decade. Cash is not just cash.

In a wide range of other important investment topics ...

Joe Magyer describes the value of letting your winners run, and anyone who sold out of a great growth story like CSL, Xero, Amazon or Magellan will know the pain of taking profits early.

Bank hybrids have become a massive sector in the 'reach for yield', especially for retirees replacing term deposits, and part of the return assumption depends on when a bank will repay this perpetual instrument. Fixed interest experts, Justin McCarthy on one side and Simon Fletcher and Charlie Callan on the other, disagree on a NAB hybrid which has seen significant price movement recently.

Fidelity International has released new research on the value of advice. Alva Devoy reports on the higher proportion of people who worry about their future when they do not seek advice, but most importantly, there is a link between financial and mental health.

The wide margin between low bond rates and the yield on high-quality non-residential property continues to drive flows, and Adrian Harrington shows the sectors attracting the most attention. Like residential property, the market is very strong.

The window for submissions to the Retirement Income Review recently closed, and Roger Cohen highlights the 'retirement gap' that punishes saving, and he offers an alternative.

Finally, Peter Cook believes low interest rates force a rethink of 'Total Return Investing', because below a certain income threshold, investors need to accept some level of capital volatility.

This week's White Paper from Magellan looks at the ways technology is changing modern medicine. No wonder we are living longer, and many companies are benefitting.


Graham Hand, Managing Editor

For a PDF version of this week’s newsletter articles, click here.


  •   13 February 2020
  •      
  •   


Leave a Comment:

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.