Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 459

When will I retire? Economic impact of an ageing population

Meeting the changing needs of older people in terms of housing, support services and work arrangements is a significant challenge facing Australia.

Demographers, economists and policy makers are increasingly concerned about the ageing population and the increasing number of people aged over 45 who will start to transition into retirement over the next 20 years. In 2021, 39% of the labour force was aged over 45-years-old, compared to 32% in 2001. Over the next 20 years, an increasing number of people will start to transition into retirement.

Age of retirement

In 2021, men aged 45-years-old were expected to retire at age 65.2 and women were expected to retire almost one year earlier at 64.3. Over the past 30 years the expected retirement age for women has increased by 3.5 years and 1.9 years for men.

Intergenerational reports prepared for the Commonwealth and State Governments highlight the challenges of an ageing population, including significant impacts on the labour force, consumption patterns, public finances and – in turn – economic growth.

Comparing the major Australian cities (based on the greater capital city statistical area), people in the larger cities of Sydney and Melbourne tend retire earlier than their counterparts in Brisbane Perth and Adelaide. This may be driven by the relative cost of living in Sydney and Melbourne, which encourages older people to shift out of the city as they age to a lower-cost regional area.

Important factors increasing the expected age of retirement:

  • A shift towards service-based jobs and away from more physically-demanding jobs.
  • Overall increased labour force participation among women due range of policy measures that have helped women strengthen their links to the labour force during their 20s, 30s and early 40s.
  • Increased demand for paid paternity leave (for both men and women), access to affordable childcare and early childhood education, and greater focus on gender equity within the society and in public policy.
  • Strong labour market conditions helping to retain older workers in jobs.
  • Changing social attitudes towards older workers.
  • Increasing trend towards part-time work amongst older workers.

Length of retirement

By combining life expectancy data with the expected age of retirement, an expected ‘length of retirement’ can be estimated. The length of retirement has implications for individuals as they manage their personal finances, the aged care sector, and for the government in terms of transfer payments and healthcare costs.

Men have seen a significant increase in expected length of retirement – from 9.3 years in 1978 to 17.3 years in 2019. This has been driven by increases in life expectancy, while age of retirement has remained relatively steady between 63 and 65 years old. Women have seen a 3.5-year increase over the same period.

Expected Age of Retirement & Length of Retirement, selected years
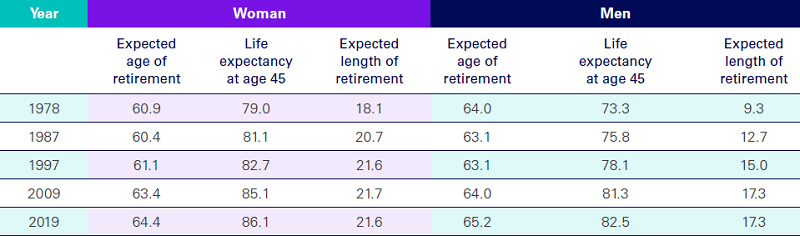
Source: Australian Bureau of Statistics – Life tables, and KPMG Australia

Key considerations highlighted in new report

Based on analysis of an age of retirement dataset prepared by KPMG Australia, the 'When will I retire' paper considers:

  • Implications of the length of retirement for both individuals’ personal finances and for government spending.
  • How an increasing age of retirement indicates that businesses will be able to access skilled labour for longer, although the data suggests that older workers would prefer to work part time.
  • The opportunity for both workers and businesses to come together to retain skilled workers and provide older people with income, social interaction and intellectual stimulation.
  • The move by older people away from the major cities into regional areas and the challenges and opportunities this presents.
  • The need to continue to maintain momentum on gender equity and what actions can be taken to address this.
 

Download report

Our latest thought leadership paper When will I retire? explores the implications and opportunities of the changing retirement landscape.


Terry Rawnsley is a Director, Demographics & Urban Economics, Planning & Infrastructure Economics, and Asaf Cohen is a Senior Consultant, Planning & Infrastructure Economics at KPMG. This article is general information only and does not consider the circumstances of any person. See report for full disclosure.


  •   25 May 2022
  • 6
  •      
  •   
6 Comments
Alex
May 25, 2022

Some day, I'd like to hear more about what people actually do in retirement. What replaces 10 hours a day of work?

Kevin
May 25, 2022

One word Alex,freedom.Life is no longer ruled by a clock or what day it is.
Summer the sun wakes you up.Winter you get to lie in until 7 - 7.30 am when the sun comes up.
The fun and exercise of cycling is great.An easy 5 - 7 hours a day doing that,the outdoor gyms that are built,sit ups,butterfly press,rowing machines and cross trainers .All the people that you meet being out all day,young and old.
When people said I don't know how I found the time to go to work and you thought they were slightly mad,it is true.There aren't enough hours in the day.to enjoy freedom .
The only regret I have is that I didn't retire earlier.
Then there is planning holidays,organising flights etc,loads of things to do.

Rob
May 25, 2022

Lots to do - I've been retired since age 53 (now 59). Read books, take long walks, manage SMSF & own/families' personal investment portfolios/admin, joined a local history group, volunteering, day trips, etc. Or even just doing nothing is sometimes good.

Mark
May 25, 2022

You can play 3 rounds of golf,or more,swimming,walking,dine out,rowing on local lakes,travel for $2 any where on govt transport after 60,travel overseas,cruising,meeting friends,cycling,donate time for charity work,etc
Many things to do Alex
Especially after working from the age of 15 it is my free time now to enjoy

Clark
May 25, 2022

I would endorse the comment that "I don't know how I ever found the time to go to work" I am luckier than most; I enjoyed my working life and was able to retire gradually between the ages of about 69 and 72. Retirement activities include a lot of volunteering - Rotary club, Board of a local not-for-profit aged care facility, membership of Aust. and international working groups, keen interest in recycling and reaching carbon-negative status, etc.
Also keeping fit, helping kids and grandkids establish themselves, managing SMSF, gardening, reading etc.
We (my wife and I) have recognised that at 78 we are not as strong or active as we used to be, and have abandoned caravanning in favour of less strenuous accommodation when travelling. I have also reluctantly abandoned climbing trees with the chainsaw running. We both think international travel is generally becoming too difficult to bother with. However I still think a week or so in countries like Cambodia or Timor Leste evaluating a project and finding out what the locals really need , and how the local system works (usually thoroughly corrupt), is much more fun than a trip or cruise organised to the nth degree by some profit-making group. It may be a bit uncomfortable - lots of dusty travel on dreadful roads and tracks - but it is not expensive when the locals book your accommodation. Try $15 a night in Cambodia for accom with basic ensuite, noisy but effective aircon, and beer downstairs at $1 a can!
I am sure I will die with unfinished projects but I hope not soon.

Steve Halloway
May 28, 2022

I am 73 and have been visiting and volunteering in Cambodia for 14 years,going back soon.


Leave a Comment:

RELATED ARTICLES

The big questions facing retirees

Does an American retirement rule work for Australians?

Why spending more in early retirement can improve lifetime income

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.