Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 678

Who really loses from the SMSF borrowing ban?

The wealthy were never the borrowers

Investors with substantial wealth generally have alternatives to borrowing inside super to acquire property. They can often buy outright or use borrowing arrangements outside super that offer greater flexibility and liquidity. Limited recourse borrowing matters to a different group: people with enough super to be credible borrowers, but not enough to write a cheque for a property outright.

The ATO’s own statistics bear this out. About 58% of SMSF members report taxable income below $100,000, and 74% below $150,000. Only 3.2% report income above $500,000. The balance data says the same thing. In the most recent annual breakdown, limited recourse borrowing is most concentrated in funds holding between $500,000 and $1 million, and that band alone accounts for roughly a third of all LRBA exposure. That is the group for whom borrowing is likely to be most relevant: large enough to contemplate property, nowhere near large enough to buy it outright.

The data therefore raises the question of whether the measure primarily affects the investors it was designed to target. It closes a pathway that many middle and upper-middle balance funds used to obtain an asset, while large funds continue to access the same asset class through scale.

A rule that tracks structure rather than risk

It is worth being precise about what has changed, because the shorthand has been loose. LRBAs are not banned. From 10 August 2026, real property acquired under a new LRBA has to be business real property. Residential dwellings fail that test, as does some mixed-use property that falls short of the technical definition. Arrangements entered into before commencement are grandfathered, along with the refinancing of them.

Meanwhile, the large APRA-regulated funds most Australians belong to still hold residential property and will continue holding it. They simply do not do it by buying individual dwellings.

Australian Retirement Trust has flagged its largest annual investment in Australian property, committing $3 billion over twelve months to developing housing supply, new offices and industrial land, on top of the roughly $19 billion it already holds in real estate equity. Aware Super’s property portfolio runs to about $12 billion, roughly 70% of it in Australian real estate, including build-to-rent apartments and its Essential Worker Housing program.

That is exposure built through scale, property platforms and partnerships with developers and fund managers. A fund with a few hundred thousand dollars cannot assemble anything like it. What the new rule removes is one of the practical ways a smaller, self-directed investor could obtain direct residential property exposure within super.

Two investors can seek exposure to the same underlying asset class yet face very different regulatory treatment depending on the structure through which they invest.

Why hold any property in the first place

Few would sensibly argue for putting an entire retirement portfolio into housing. The argument is for holding a portion of it. Shares and residential property do not move in lockstep, and that is part of what makes a portfolio resilient. In calendar 2008, Australian shares lost 39.2% including dividends, while capital city established house prices fell 4.1%. Both recovered the following year, shares by 37.9% and house prices by 13.8%. A fund holding both came through that period better than a fund holding shares alone.
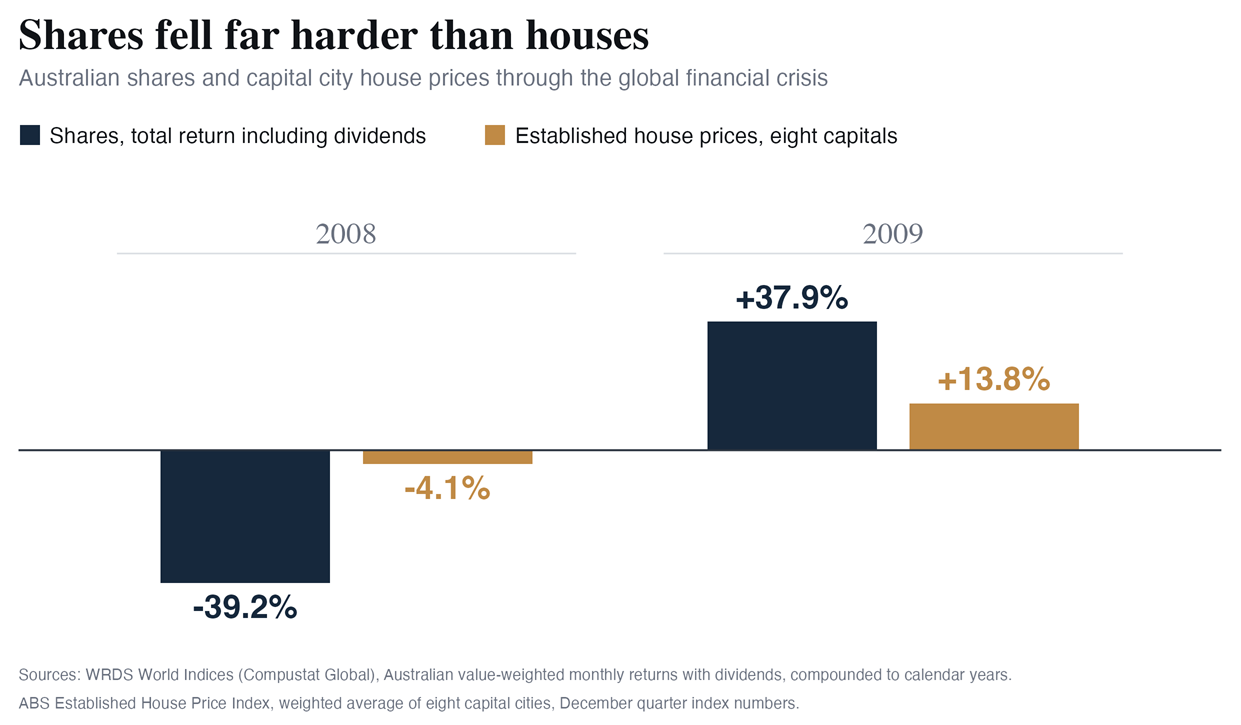
Restricting a smaller investor’s ability to own residential property directly within super may reduce one source of risk, but it can also leave their retirement savings more exposed to whatever the share market happens to do that year.

The risks are real. They are not universal.

None of this means the concerns behind the change were invented. Borrowing to buy property inside super can create genuine problems: excessive gearing, over-concentration in a single asset, liquidity pressure when rents fall or rates rise, and the high-fee property spruiking that has shadowed this corner of the industry for years.

But those risks are not present in every arrangement. A conservatively geared purchase supported by a liquidity buffer and proper advice presents a different risk profile from a heavily geared bet on a mediocre property.

The aggregate numbers also raise questions about the scale of systemic risk involved. As at the March 2026 quarter, self-managed funds held just under $30 billion in borrowings against more than $1 trillion in assets. Across the geared arrangements themselves, borrowings run to about 36% of the value of the assets sitting under them. That is real leverage. But it is happening in a small corner of the system now served by only around 20 lenders, the major banks having withdrawn years ago. The market remains relatively small and specialist compared with mainstream mortgage lending.

What a proportionate approach would have looked like

Where the risks are genuine they can be dealt with directly. Cap the gearing. Limit how much of a fund can sit in one asset. Require a liquidity buffer. Large funds already manage exactly these risks inside a prudential framework overseen by APRA. Self-managed funds sit largely outside that framework, and one response to that gap would be to extend proportionate safeguards to them, not to remove an asset class from one group of investors while leaving everyone else untouched.

A blanket prohibition cannot tell a reckless arrangement from a prudent one, so it ends both.

That distinction will matter well beyond this particular measure. The provision arrived late, by amendment, without consultation or an explanatory memorandum, and industry submissions have already pressed for a carve-out for newly built housing. If the policy is revisited, the key question worth asking is not whether borrowing inside super carries risk. It plainly can. The question is whether the regulatory response is directed at the risk itself or primarily the investment structure through which the risk arises. Retirement policy should be slow to narrow what an ordinary saver is allowed to hold while the large and the wealthy carry on exactly as before.

Figures in this article are drawn from the ATO’s Self-managed super fund quarterly statistical report, March 2026.


Dr. Ruchith Dissanayake is a Senior Lecturer in Finance at the Queensland University of Technology and a Chief Investigator on an AHURI-funded housing finance research project. Ama Samarasinghe is a Lecturer in Financial Planning and Tax at RMIT University. Ruchith is also Principal of BID Capital, a mortgage and finance brokerage whose business has included arranging SMSF loans for residential property. This article is general information only and does not consider the circumstances of any investor. The views expressed are those of the authors and do not necessarily reflect the views of QUT, RMIT or AHURI.


  •   2 September 2026
  • 10
  •      
  •   
10 Comments
OldbutSane
September 03, 2026

I don't think SMSFs should have been allowed to borrow in the first place.

It also wasn't a level playing field as it was practically impossible to borrow for anything other than property.

3
Graham W
September 05, 2026

A SMSF can use a borrowing strategy by using a geared share fund or ETF and some property funds also use gearing. A far safer stragey in my opinion than buying an expensive property using an LRBA and far easier and less costly to do so. Also easy to sell of over time if circumstances change.

Peter
September 03, 2026

These people may have been much better off with the geared property outside of super. Was this considered? The research looks limited in scope.

1
Ruchith
September 03, 2026

Thanks Peter. That’s a fair question.

Buying a geared property outside super may well have been better for some members, but it isn’t a like-for-like alternative. Capital held inside super generally cannot be withdrawn and used as the deposit for a personal purchase. Buying outside therefore requires a separate deposit and sufficient personal borrowing capacity. The tax treatment is also different.

There is a further distinction in the loan structure. Under an LRBA, the lender’s recourse against the SMSF trustee is limited to the acquired asset. An ordinary property loan outside super is generally full recourse, although guarantees and individual loan terms still matter.

The aggregate data cannot tell us how many LRBA users could have purchased the same property outside super, and the article does not claim that borrowing inside super was always the better strategy. Its narrower question is whether a restriction framed as targeting the wealthy falls primarily on that group. The ATO data suggests LRBA exposure was concentrated among funds holding between $500,000 and $1 million.

The inside-versus-outside comparison is a worthwhile question, but it requires a separate analysis.

1
Peter
September 04, 2026

Best you make a start. Your analysis is too narrow and slanted

AndyDandy
September 07, 2026

Short answer is NO.
The net position is far more higher benefits with property inside super than outside assuming it is same asset quality.
People who have actually used SMSF borrowing know how it works. Others are guessing, including politicians, hence this problem. I would have expected Mr Chalmers to have a broader lens on this issue but he seems to have lost his way with Greens on this.

This scenario applies to people who have already used their personal borrowing capacity to buy their home (PPOR). For them, borrowing outside super may simply not be an option.

For eg- If they have $250,000 or more in super, they may be able to invest through an SMSF without affecting their personal borrowing capacity.

The other major advantage is tax. The tax rate inside an SMSF is generally much lower than holding the same investment personally.

Also, borrowing outside super affects your personal borrowing capacity and tax position. SMSF borrowing does not have the same impact.

So the real comparison is not always "property inside super versus property outside super". For many people, it is "property inside super versus not being able to invest at all".

My own example is I had $250k in super which I used to estalish smsf and acquire a residential asset (duplex) valued at $1mil with yield of 6%. Now with interest rate of 6.99% and tax savings including depreciation, it is likely to be cashflow positive after 2 years.
Another way of looking at it is if the rental income and depreciation benefit can support the mortgage payments, the property is break even and within 30 years will have $1mil in the portfolio. NOTE that I have not used any of my new contributions which I am free to invest.
In my opinion, the smsf borrowing is one of the best tax effective way for both the individual and government to fund the housing market supply and allow a safe return to smsf investors. Of course there needs to more guard rails than the current rules.

Manoj Abichandani
September 03, 2026

There are many reasons why an SMSF should purchase an investment residential property via an LRBA

1) The property can be sold to the trustees to downsize at the time of retirement. Hence buying a retirement property at today’s prices and renting for 20 years and then moving in - makes sense.

2) Due to inflation (I am not talking about natural growth) values would generally be more in 20 years time. On the other side of the coin LRBA loan amount reduces its intrinsic value over time. Thereby creating a gearing benefit to the investor - using preserved funds (inside super)

3) If the asset is sold – it can generate Nil or 10% tax on gain (avoiding the Div 296 discussion) whereas tax will always be higher outside of Super

Most of the buyers after the May 26 budget were setting up new fund. We are still waiting for June 26 QTR SMSF statistics to be released by ATO on newly set up funds – I can almost with certainty guess it will be almost double to the number of funds set up in June 25 Qtr. This I say with confidence observing the number of funds set up by accountants in June 26 QTR.

When ATO data shows 74% of members of SSMF have less than $150,000 taxable income – it does not mean that they are lower income – it can also mean that they are over 60 and withdrawing a non-taxable income.
Hence in my opinion, to claim that funds holding between $500,000 and $1 million are borrowing is incorrect or just a wild guess.

It is wild guess because, firstly there is no such data available and secondly if you were to observe most recent activity (prior to 10th Aug 26) in SMSF residential property purchases – it was mostly where the members had less than $500,000 as most purchases were by new funds rather than an established fund. Generally members set up funds with a lower than $500,000 roll over amounts.

Lastly and most importantly, I agree, that larger SMSF’s belong to wealthier members and for them holding a large SMSF balance, that is above $3M or over $10M is not in any way beneficial than having assets in other structures outside of SMSF.

As far as risks are concerned on holding LRBA and almost no diversification in SMSF with a single asset, members of SMSF are smart and the sensible ones and will ensure that there is no negative gearing happening inside of super and will be mitigating this risk by higher concessional contributions via salary sacrifice or other methods like personal deductible contributions.

They know when they turn 67 – either the age will be pushed back or the governments will not have enough money for every retiree. 

1
Richard Lyon
September 05, 2026

Two things:

First, the latest ATO statistics show (with a bit of work and a reasonable assumption or two) that the average SMSF in the $500k to $1m bracket that had a limited recourse borrowing arrangement probably had about $800k backed by that arrangement in 2023-24. That's not an unreasonable value for an investment property (either a capital city unit or a regional house). The SMSF could borrow about 67% loan-to-value, so a new investor has borrowed north of $500k. Before that borrowing, it was a $200k to $500k fund. Thinking only about funding sensibly for retirement, is it really good advice to replace almost $300k of cash in such a fund with a geared exposure to a single illiquid asset to the tune of $800k? It may be a gravy train for some financial advisors, but it's NOT good advice.

[And, yes, the ATO statistics are for gross assets; the overall average of assets backed by LRBAs, for the roughly 56,000 funds that had them in June 2024, is about $1.26m per fund, and 55% of the funds with LRBAs are in the $500k to $1m gross asset range. That limits the range of the possible average size of the LRBA-backed asset in the average such fund.]

Secondly, the implication of "we must - and will - make housing more affordable" is that residential property will experience lower capital growth in future. Again, this screams that geared exposure to a single property, chosen for price rather than prospects, may be a bad idea, relative to (say) a broad share portfolio.

Perhaps the Government simply believes that small SMSFs need protection from themselves (or, more likely, from rogue financial advisors)?

Richard Lyon
September 06, 2026

Two things:

First, the latest ATO statistics show (with a bit of work and a reasonable assumption or two) that the average SMSF in the $500k to $1m bracket that had a limited recourse borrowing arrangement probably had about $800k backed by that arrangement in 2023-24. That's not an unreasonable value for an investment property (either a capital city unit or a regional house). The SMSF could borrow about 67% loan-to-value, so a new investor has borrowed north of $500k. Before that borrowing, it was a $200k to $500k fund. Thinking only about funding sensibly for retirement, is it really good advice to replace almost $300k of cash in such a fund with a geared exposure to a single illiquid asset to the tune of $800k?

[And, yes, the ATO statistics are for gross assets; the overall average of assets backed by LRBAs, for the roughly 56,000 funds that had them in June 2024, is about $1.26m per fund, and 55% of the funds with LRBAs are in the $500k to $1m gross asset range. That limits the range of the possible average size of the LRBA-backed asset in those funds.]

Secondly, the implication of "we must - and will - make housing more affordable" is that residential property will experience lower capital growth in future. Again, this screams that geared exposure to a single property, chosen for price rather than prospects, may be a bad idea, relative to (say) a broad share portfolio.

Perhaps the Government simply believes that small SMSFs need protection from themselves?


Leave a Comment:

RELATED ARTICLES

30 years on, five charts show SMSF progress

Watch SMSF borrowing rules for separate assets

Meg on SMSFs: How wide is the ban on LRBAs?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Will you run out of money in retirement?

Fear of running out has become a defining retirement anxiety. Why do some retirees die with substantial wealth while others deplete their nest egg? Evidence suggests the answer is more complicated than we think. 

The investment that sidesteps the new tax traps

Tax rules have changed, but many investors are still using yesterday’s strategies. Insurance bonds may offer advantages for those seeking greater control, tax efficiency and certainty about their wealth.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Latest Updates

Planning

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Investment strategies

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Economy

Population growth masks Australia’s productivity problem

For years, investors have benefited from a seemingly reliable growth story. But recent national accounts raise uncomfortable questions about what has really been driving Australia’s economy and whether that can continue unchecked.

Investment strategies

Why tomorrow’s winners may not be today’s index leaders

The stocks that built retirement balances over the past decade now dominate many portfolios. The new challenge is whether these companies can continue meeting the increasingly high expectations embedded in today's share prices.

Investing

What earnings surprises reveal about future returns

Sometimes the most important information in an earnings result isn't the number itself. It's the possibility that the market's assumptions have been fundamentally wrong and future earnings may look very different.

SMSF strategies

Individual SMSF Trusteeship directly liable for ATO fines

A rarely discussed detail buried in SMSF structures could dramatically change who wears the cost when something goes wrong. With penalties rising, a decision many dismissed as administrative may deserve a second look.

Investment strategies

The currency bet you didn’t know you made

Buying global shares means making two bets: on the companies and on the Australian dollar. Most investors consciously choose only the first. Last financial year, the second bet cost 8.5% in returns for many investors.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.