Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 149

Why SMSFs should have a corporate trustee

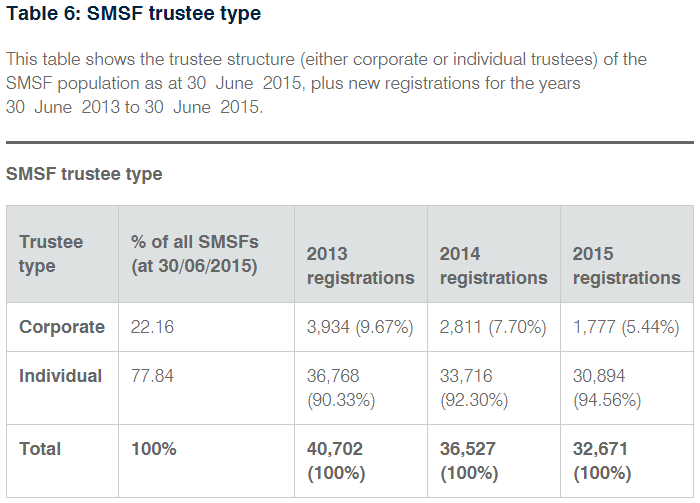
Did you know that 78% of SMSFs are set up with individual trustees but that over 90% of professional advisers I have canvassed would always recommend a Sole Purpose Company trustee? In the haste to set up funds, most people miss this vital step with many having to pay high fees to change trustee later.

The issue is worsening as in the three years to 2015, there was a 4% decline in SMSFs registering with a corporate trustee. Of newly registered SMSFs in 2015, an incredible 95% had individual trustees (see: ATO Self-managed super fund statistical report – June 2015 appendix 1, table 6)
I believe it is essential to have a company as trustee and that the option to have individual trustees is short-sighted.

Benefits of a corporate trustee

A corporate trustee facilitates:

  • Time to grieve or adapt. The strongest reason from 10 years’ experience with SMSFs is respect for your spouse or family’s needs in times of grief. Do you really want to leave them an awkward and expensive set of tasks to carry out just to save $700?
  • Continuous succession. A company has an indefinite life span; it does not die. A corporate trustee can ensure control of an SMSF is more certain following the death or mental or physical incapacity of a member.
  • Administrative efficiency. When members are admitted to, or cease, membership of the SMSF, all that is required is that the person becomes, or ceases to be, a director of the corporate trustee. The corporate trustee does not change as a result. Therefore, title to all the assets of the SMSF remains in the name of the corporate trustee, especially useful when dealing with property in an SMSF.
  • Sole member SMSF. An SMSF can have one individual as both the sole member and the sole director. Likewise, if a spouse is incapacitated, then the husband or wife can act as director under an enduring Power of Attorney to run the fund on their own without the need for interference by others.
  • Meets lenders’ requirements. Most lenders require a corporate trustee in the SMSF as it is easier to deal with.
  • Higher Loan to Valuation Ratios accepted. With a corporate trustee, many lenders will go to 80% on residential loans and 70% on commercial real estate.
  • Greater asset protection. As companies are subject to limited liability, a corporate trustee will provide improved protection for the directors where a party sues the trustee for damages. I use an electrician as an example here when I discuss this with clients. If he is on your property and is electrocuted because of the owner’s (SMSF) negligence, then the SMSF may be sued but your own personal liability is limited to your shareholding and member balance rather than your entire wealth

Problems with individual trustees

Individual trustees cause issues with:

  • Paperwork at the worst time. Welcome to a nightmare. When a spouse has barely had time to start grieving, they need to manage the SMSF and administer pensions, investments and deeds. Minutes to record death of trustee, deed update to add a new trustee or move to a corporate trustee, off-market transfer forms and identity forms and probate forms to put every investment in correct name(s). Worse still, deal with the Land & Property Management agency or Office of State Revenue and their endless forms!
  • Complexities relating to death. If the SMSF has individual trustees, e.g. a husband and wife, then timely action must be taken on the death of a member to ensure the trustee and member rules are adhered to properly. For example, SMSF rules do not allow a sole individual trustee/member SMSF.
  • Extra and costly administration. To bring in a new member to an SMSF with individual trustees requires that person to become a trustee. As trust assets must be held in the names of the trustees, the title to all assets must be transferred to the new trustees.
  • Sole member SMSF. A sole member SMSF must have two individual trustees. Does a spouse need to rely on the children, possibly from the first marriage? That’s really not going to work as we know what a problem blended families are when it comes to estate planning.
  • Tighter lending rules. Lower LVRs are common, due to legal concerns, lenders restrict the maximum borrowing of an SMSF with individual trustees to 70% for residential properties and 55-60% for commercial real estate.
  • Less asset protection. If an individual trustee suffers any liability, the trustee’s personal assets may be exposed. The trustee as well as the SMSF may be sued by someone doing work for the SMSF.

What do the ATO and ASIC think?

The Australian Securities & Investments Commission (ASIC) and the Australian Taxation Office (ATO) prefer corporate trustees. Last year, ASIC released a number of documents which outlined the advantages of an SMSF corporate trustee.

More recently, the ATO released an article and video on SMSFs titled Choose individual trustees or a corporate trustee that objectively outlines the pros and cons.

And even more advantages of a corporate trustee

With a bit of preparation and planning, combining your will and enduring powers of attorney, minuted resolutions and if needed clauses written into the deed, a person (usually the Executor or Legal Personal Representative) can be immediately appointed as a director so that the fund can continue to operate in the event of death regardless of whether a death certificate or probate have been granted.

Likewise, a person who loses mental capacity needs to be replaced if they were individual trustees. With a company, the constitution can immediately have a mechanism which allows the person holding the enduring power of attorney to be appointed as a replacement director, resigning the incapacitated director at the same time.

Under ASIC’s new administrative penalties, if a fine is made in relation to an SMSF that has individual trustees, then each trustee will be fined in their personal capacity. The fine is personally payable and cannot be reimbursed by the fund. Only one fine is payable by a corporate trustee.

It is also easy for Superannuation Industry Supervision (SIS) regulation 4.09A(2)(a) to be contravened by an individual trustee. It says:

“A trustee of a regulated superannuation fund that is a self-managed superannuation fund must keep the money and other assets of the fund separate from any money and assets, respectively: … (a) that are held by the trustee personally …”

For example, if individual trustees receive rental property income or a dividend into a personal account in their own names instead of an account in their personal names but with the account designation of their SMSF, it is a contravention. With a corporate trustee, it’s far less likely to mix fund assets with personal assets.

Summary

It’s difficult to believe that 90% of SMSFs are currently being established with individual trustees. Even if some costs of registering a company are initially avoided, the trustees are almost certainly inviting complications later in the life of the SMSF.


Liam Shorte is a specialist SMSF advisor and Director of Verante Financial Planning. This article contains general information only and does not address the circumstances of any individual. Professional personal financial advice should be sought before taking action.


  •   31 March 2016
  • 8
  •      
  •   
8 Comments
SMSF admin
March 31, 2016

These numbers are a mystery. I spoke to a few online providers and they say the stats don’t reflect their business which is about 80% corporate trustee. Everyone is perplexed about who is actually opening those individual trustee funds.

Wife about to win an argument..again!
April 01, 2016

Thank you, thank you, thank you. I have been arguing with my husband about this for a few years now and this is the best laid out set of reasons for moving to a corporate trustee I have seen. I am sure that my beloved hubby is just delaying because he is miserly and thinks he will pass away first and I can deal with the paperwork...like I do for everything else in our business.

Liam Shorte
April 02, 2016

Glad I could help you. Remember you can get a discount on the annual ASIC review fee for the Corporate trustee by paying up to ten years in advance at today's rate.

Randall Kingsley
April 01, 2016

Thanks for quite a good article, even if I disagree with the notion. Might be a tad aspirational but we have opted to have the maximum allowed four trustees in our smsf-two in retirement now and two in the 30s and building their super. Our hope is that our smsf will become almost perpetual and as hand the running off to the next generations. Almost like the now defunct idea put forward by our poor PM who is trying to get our leaders to take on more financial responsibilities. And after 12 years or so we are working well, I only wish we were allowed more trustees!

Liam Shorte
April 02, 2016

Randall, there are always exceptions to a rule. Hopefully your family will continue to benefit from your obvious good guidance to take super serious from an early age.

Jonathan Hoyle
April 02, 2016

Well argued, Liam. A Corporate Trustee is nearly always the preferable option.

Denzil
May 02, 2024

My SMSF was established over 20 years ago when corporate trustees were not nearly as common as they are now.
Even though I see the advantages of a corporate trustee and would like to make the change, the capital gains implications of transferring all holdings to a new name are too horrendous to contemplate.

John
June 26, 2024

I suggest checking this. I understand that as there is no change in beneficial ownership there is no CGT implications


Leave a Comment:

RELATED ARTICLES

SMSFs and the control over estate planning

Importance of updating your SMSF Trust Deed

Individual SMSF Trusteeship directly liable for ATO fines

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.