Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 466

ASA’s view on the banning of LIC commissions

This is a copy of the ASA's submission to Treasury's post-implementation review of the banning of stamping fees, in response to this request:

Treasury is seeking feedback from consumers and industry stakeholders on the 2020 change which extended the ban on conflicted remuneration to ‘stamping fees’ paid by Listed Investment Companies (LICs) and Listed Investment Trusts (LITs).

Treasury is seeking feedback on

  • the policy’s regulatory impacts on advisers and stockbrokers
  • changes to consumers' investment choices
  • competition settings for managed funds, and
  • any other unintended consequences in the market.

Stamping fees are an upfront one-off commission paid to Australian financial services licensees for their role in capital raisings associated with the initial public offerings of shares.

***

The Australian Shareholders’ Association (ASA) represents its members to promote and safeguard their interests in the Australian equity capital markets. The ASA is an independent not-for-profit organisation funded by and operating in the interests of its members, primarily individual and retail investors, SMSF trustees and investors generally seeking ASA’s representation and support. ASA also represents those investors and shareholders who are not members, but follow the ASA through various means, as our relevance extends to the broader investor community.

Consultation process on stamping fees

Thank you for the opportunity to submit comments to the post-implementation review on the removal of the stamping fee exemption.

We will briefly address 4 of the 5 questions posed, grouping 1 and 3:

1.What impact has the policy change had upon retail investors?
3.How have consumers’ investment choices been affected?
4.Has the policy beneficially changed competition settings in the managed funds sector? and
5.Have there been unintended consequences resulting from the policy changes?

1 and 3. What impact has the policy change had upon retail investors and how have consumers’ investment choices been affected?

We maintain the policy stance enunciated in our submission in 2020 on the merits of the current stamping fee exemption in relation to listed investment entities, that there be no carve out of a subset of listed entities from the overarching exemption. We remain concerned that access to initial public offers (IPOs) is denied to many retail shareholders, denying them the ability to access risk- and price-appropriate assets.

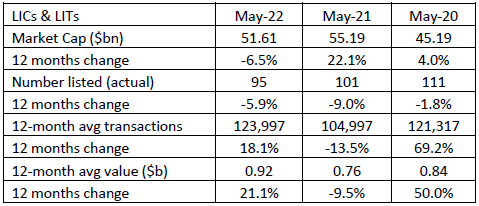
We consider the removal of the stamping fee exemption has reduced the number of listed investment companies (LICs) and listed investment trusts (LITs) coming to market and hampered the creation of new and innovative listed entities designed to meet perceived investor need.

Since the policy change in May 2020, there have been few IPOs of LICs and LITs, with fewer being made available as general offers. The Magellan Global Fund (MGF) listed in November 2020 and was a compliance listing merger of two pre-existing funds; Salter Brothers Emerging Companies Limited (SB2) listed in June 2021; WAM Strategic Value Limited (WAR) listed in June 2021; Touch Ventures Limited (TVL) listed in September 2021 (and had no general offer); and Cadence Opportunity Fund Limited (CDO) listed in November 2021 after commencing as an unlisted fund in January 2019.

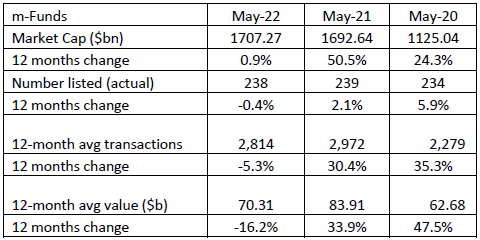
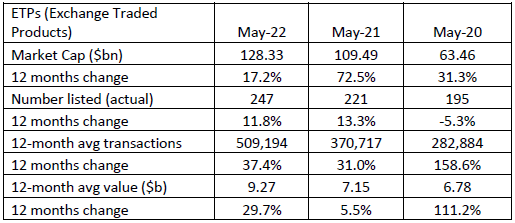
The overall statistics in the three tables below, show a reduction of the number of listings of LICs and LITs, and modest growth of $0.08b in the 12-month average transaction value from 2020 to 2022. This compares to an increase in number and lift in the 12-month average transaction value of $7.63b for selected unlisted managed funds available via the ASX (m-Funds) and $2.49b for exchange traded products (ETPs).
Source: ASA and ASX Investment Products reports May 2022 and May 2020

4.Has the policy beneficially changed competition settings in the managed funds sector?

There has been an increase in the number and the market capitalisation of m-Funds as shown in the table below and for unlisted funds. ICI Global, in its Worldwide Public Tables for the end of 2021, stated the total assets in Australian unlisted managed funds were valued at about $3.5 trillion, or in US$2.6 trillion and increase from US$2.5 trillion.
Source: ASA and ASX Investment Products reports May 2022 and May 2020

5.Have there been unintended consequences resulting from the policy changes?

It is our understanding from reading the initial consultation paper that the intention of the removal of the stamping fee exemption was intended to relatively advantage managed funds compared to LICs and LITs. It also appears to have advantaged exchange traded products.
Source: ASA and ASX Investment Products reports May 2022 and May 2020

In summary, ASA considers the removal of the stamping fee exemption should end, and retail investors be allowed to choose appropriate investments.

We also flag the short eight working day consultation period, with the notification email received at 5pm Tuesday, 28 June and comments required by Sunday, 10 July. We believe short notice periods act to limit the consultation, reducing the number and depth of submissions. We request that longer consultation be considered for future stakeholder engagement on important matters to retail investors.


Rachel Waterhouse is Chief Executive Officer of the Australian Shareholders’ Association. 


  •   13 July 2022
  • 3
  •      
  •   
3 Comments
John Abernethy
July 16, 2022

Thank you Rachel,

A well written submission noting the short time frame for the consultation period.

You rightly note the time frame that suggests a lack of intention to properly review the law.

It is interesting to note that in recent hybrid or capital notes issued by major banks to be listed on the ASX, that so called “advisor fees” were paid. These are “wholesale / sophisticated offers” raising billions.

So why allow advisor fees on wholesale offers but not on retail offers? They are really distribution fees cloaked as another name.

The acknowledgement of the fee is that there is a cost of distribution that the authorities accept in some circumstances but not in others.

Intermediaries play an important role in the capital markets. They play a role in both primary and secondary markets. The issue of a security ( primary) and the trading of it ( secondary) involve the same security.

The question is this. Should the issuer pay the cost of a transaction or distribution or should the purchaser/ investor?

Further - why are wholesale offers treated differently to retail offers?

The review needs to be conducted with a lot more diligence then is suggested by the current time frame set.

John Abernethy
Chairman
Clime Capital Limited

C
July 16, 2022

People have switched to ETFs ( both passive and active ) largely because of lower fees, more diverse and focussed choices ( eg Healthcare ETF ) and buying & selling at NAV rather than the crazy discounts and premiums that marr LICs.
Investors have not made this change because of removal of stamping fees to brokers !

Goronwy Price
July 17, 2022

I have no problem organisations earning a commission for selling any product or service. However they should not be called “Financial Advisors” if they are selling something to you for their benefit and not giving impartial advice. They are in that context brokers or agents and not advisors. Advisors should charge a fee for service and give impartial advice.


Leave a Comment:

RELATED ARTICLES

Conflicted selling fees are back, and it’s game on

Four ways to invest in the same fund and save money

ETFs are the Marvel of listed galaxies, even with star WAR

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.