Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 173

Australian and US house prices remain firm

House prices in Australia suffered only about half of the declines seen in the United States during the GFC. They then resumed their climb in 2012, fuelled by cheap debt courtesy of 12 interest rate cuts by the Reserve Bank of Australia since November 2011.

The chart below shows real house prices (i.e. after inflation) in the major capital cities over the past 45 years.
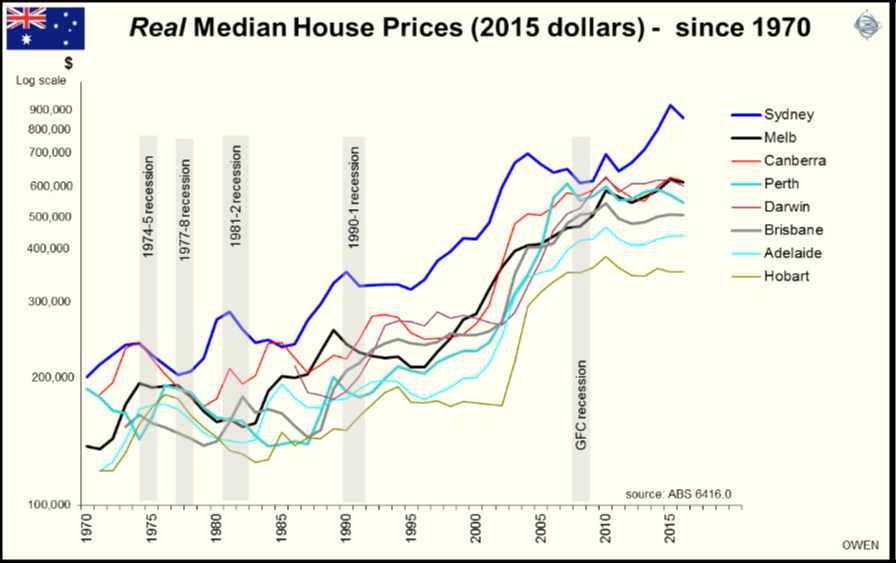
Prices have fallen in each of the major economic contractions, but have generally moved steadily upward for more than a century. Growth in house prices has been driven largely by steady population growth (mostly from immigration) in each of our main cities, a feature that is unique in the world.

Rises softening but support remains

House prices have started to soften in all the major markets over the past year. The local economy is heading for a slowdown with the end of the mining boom and the upcoming end of the housing construction boom, but there are several factors that should provide some support for house prices:

  • Interest rates are low and more cuts are on the horizon
  • Banks remain keen to lend for housing (but little else)
  • There is a seemingly never-ending flood of cashed-up immigrants (and locals) looking to buy here
  • Little risk of high unemployment (eg above 10%) for a while
  • Potential changes to superannuation rules may encourage more investment in the family home, which is likely to remain free from capital gains tax.

The high rise apartment market, however, is another story altogether. In the coming year or so we will probably see many thousands of high rise unit buyers in Melbourne and Brisbane lose money as they struggle to obtain finance to complete their purchases at boom-time prices.

US housing – recovery on track

Readers often ask why I pay so much attention to bond markets. One reason is that they are critical to the US housing market (unlike in Australia) and that in turn is an important driver of the US economy, which is still the engine of world growth and investment markets.

The US housing finance bubble was the underlying cause of the ‘sub-prime’ crisis that triggered the deepest US and global recession since the depression of the 1930s. It is also central to US economic recovery. House prices across the US more than doubled during the 2000s boom but then crashed by more than one third on average in the bust, with many cities suffering declines of 60% or more. Prices have been recovering steadily since early 2012. The key has been mortgage interest rates, which have come down from 8.5% in 2000 to below 4% since 2012.
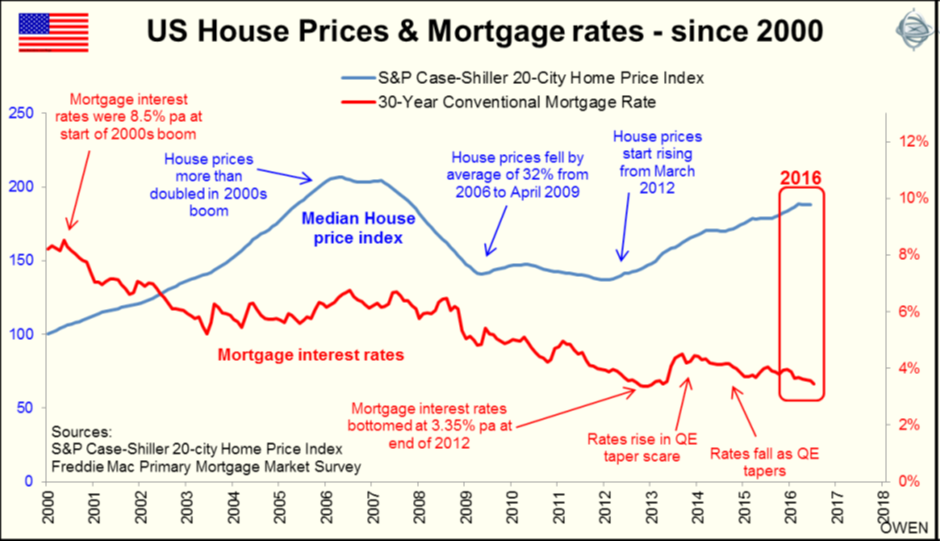
Most Australian mortgage interest rates are variable and driven by short-term interest rates, so mortgage borrowers here are directly hurt by cash rate hikes. But the US market is different. Most US mortgage rates are fixed for up to 30 years and linked to long-term bond yields.

Because of this, as the Fed raises short-term rates in the coming years, long-term bond yields (and with them mortgage interest rates) may stay relatively low. Even when economic growth and inflation rates do rise (which they surely will in time), there is a good chance that each Fed rate hike will dampen expectations of future inflation and work to keep long yields relatively low.


Ashley Owen is Chief Investment Officer at independent advisory firm Stanford Brown and The Lunar Group. He is also a Director of Third Link Investment Managers, a fund that supports Australian charities.


  •   15 September 2016
  • 1
  •      
  •   
1 Comments
Brett Edgerton
September 15, 2016

To preface my comment, this is a general comment about our housing markets and it is not specifically meant to contradict or argue against Ashley's article.

I would simply make the point that the price falls in Australian markets were coincident with the GFC, not due to it. Look at the graph for Sydney 2003 to 2009 - a cause and effect relationship is certainly not present there. It is my strong belief that the GFC had a net positive effect on the housing market (or most markets - the obvious exception is the more international Gold Coast market) over what would have happened if the GFC did not provide the government with the political cover to protect from popping what was clear to the regulators a housing bubble presenting significant risks to financial stability (as was shown by recent FOI investigations).

That is what is concerning about the RBA under Glenn Stevens in recent years - understanding those risks, but still turning to reinflate the bubble once they realised that they had severely underestimated the longevity of the resources boom. (And in the complete absence of other growth drivers... perhaps an economic contraction was worth the price of preventing a much greater one once the housing bubble pops, even if our politicians could no longer brag at the G20 about how our economy is the envy of the world!)

At least enough dwellings have been built this time - mostly apartments - to ensure the end of affordability issues for young Australians. Others can draw their own conclusions on what channels this will occur through... nonetheless, I do prefer to think positively about people, and I recall Glenn saying on a number of occasions what a pity it was that the housing "boom" was not accompanied by more building to affordably housing our people... perhaps he leaves his post with some small degree of satisfaction in that regard...

Still I think it is wise to consider the non-trivial possibility of a disorderly unwind to our housing bubble in all risk management strategies... One can listen to the purveyors of confidence and fairy dust - and allow themselves to be blinkered - or maturely consider all risks and adjust their strategy as they themselves deem necessary...


Leave a Comment:

RELATED ARTICLES

China's little emperors prop up Aussie housing market

The housing slide could become a crash

The 5% deposit scheme is bad for homeowners and Australia

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.