Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 220

Bond demand is dumb, dumber and dumbest

One of the classic signs that the strong credit cycle is nearing its end is that borrowers that should not be getting financed are not only raising money, but doing so on terms that seem crazy. I have recently written about the silly things happening in global high yield debt, Chinese debt and the global attitude to sovereign debt. Continuing this theme are recent examples of emerging market sovereign debt in Greece, Argentina and Iraq. Each of these should not have been funded, but the desperation for yield saw all three achieve crazy funding levels. Here are the details to show how investors have gone mad.

Argentina

In June, Argentina sold $2.75 billion of US dollar denominated 100-year bonds at a yield of 7.92%. This was a mere 5.18% yield pick-up over 30-year US Treasuries. Argentina has a long history of defaulting on its government debt, including four defaults in the last 35 years. The 2001 default took 15 years of negotiation and litigation to resolve, with most bondholders losing their shirts and a few who bought late and fought hard achieving extraordinary returns.

The current outlook shows that not much has changed for Argentina. Inflation is running at over 20% and the government is aiming to cut the deficit this year to 4.2% of GDP, hoping to stimulate the economy out of recession. Investors are banking on the recent change in government to increase foreign investment and see sound economic management implemented. The need to reduce politically popular subsidies will be a major hurdle to that plan. S&P’s rating of “B” and Moody’s at “B3” reflect the country’s weak credit profile. Taking all of this into account, Argentina is unlikely to get through a decade without defaulting, let alone 100 years.

Greece

In July, Greece sold €3 billion of five-year bonds at 4.63%, a 4.78% yield pick-up relative to five-year German government bonds. Investors have particularly short memories on Greece’s sovereign debt, with the 2012 default seeing bondholders take losses of around 75%. The 2014 issue of five-year bonds traded as low as 56% of face value, a horrible ride for those who bought into it. The constant negotiations for further bailouts always come with the threat that Greece will not make further concessions and this time the Europeans and the IMF might have had enough.

Greece’s position remains precarious as debt to GDP currently stands at 179%. The economy has been stagnant for years as its government continues to resist the structural reforms proposed by the IMF and Europeans. Some are optimistic as Greece recorded a primary surplus (before interest expenses) in 2016. Unlike the buyers of the recent bond issue, S&P (B-) and Moody’s (Caa2), do not see a good prospect of Greece paying back its creditors.

Iraq

In early August, Iraq sold $1 billion of five-year bonds at 6.75%, a 4.93% premium to US Treasuries. Iraq faces three major medium-term issues: the ongoing war, export revenues reliant on oil prices and dependence upon military and financial support from the US government. Each of these is out of its control. The 2016 deficit at 14% of GDP shows Iraq clearly cannot service its debts without a substantial financial turnaround. By buying the bonds, investors have effectively banked the equity case of the war ending and oil prices improving. The credit ratings from S&P (B-) and Moody’s (Caa1) are a better reflection of Iraq’s economic prospects.

Conclusion

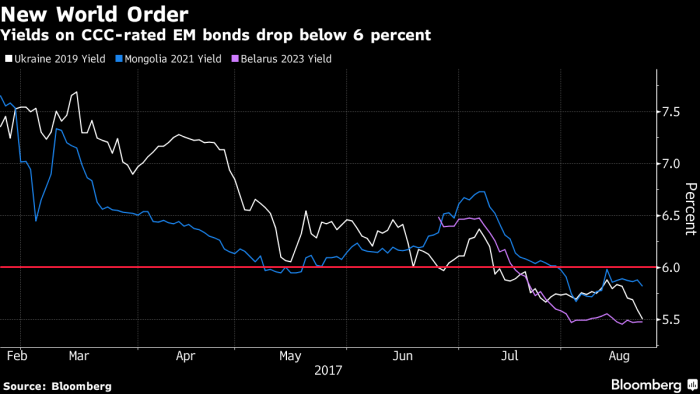
In considering emerging market sovereign debt, investors must consider each country on its own merits. In the examples of Argentina, Greece and Iraq, bond buyers have suspended sceptical analysis. They have banked the equity case, hoping for a substantial change from historical precedents, even though they will not get a share of the upside if the rosy scenario occurs. The examples are not unusual, as shown in the graph below from Bloomberg. Belarus, Mongolia and Ukraine are all CCC-rated but have bonds yielding less than 6%.

Yields on CCC-rated emerging market bonds
sovereign debt

sovereign debt

These examples point to the greater fool theory playing out in many credit markets. We have now reached the point in the credit cycle where further gains seem dependent upon more dumb money arriving and pushing spreads even tighter. Calling the top of any cycle is nearly impossible, but calling out the current higher risk/lower return environment is simply common sense.


Jonathan Rochford is a Portfolio Manager at Narrow Road Capital. This article has been prepared for educational purposes and is not a substitute for tailored financial advice. Narrow Road Capital advises on and invests in a wide range of securities.


  •   21 September 2017
  • 3
  •      
  •   

RELATED ARTICLES

Fear of missing out trumping fear of loss

Hedge funds seizing ships – what next?

Australia’s default: who do you rescue?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.