Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 193

Applying CGT relief for SMSFs and TTR pensions

Much has been written about capital gains tax (CGT) relief, and it’s worth understanding how it works. Transitional CGT relief is available for SMSFs affected by the new $1.6m transfer balance cap, or for SMSFs paying a transition to retirement income stream (TRIS).

With relief available, important decisions need to be made as we head towards 30 June 2017. These choices will have a direct effect on the amount of SMSF income tax paid in future years.

What is CGT relief in a nutshell?

The new CGT relief rule, which applies in particular circumstances, enables the cost base of fund assets to be reset to market value.

The intent of the new rule is to provide CGT relief on gains made before 1 July 2017, so as not to disadvantage fund members who are required to commute a pension due to the new transfer balance cap, or the TRIS tax changes. Whilst the focus has been on relief for retirement phase pension funds, relief also applies for funds paying transition to retirement (TTR) pensions.

Even though there’ll be no requirement to commute from a TTR pension to comply with the transfer balance cap (TTR pensions don’t count towards the cap), the introduction of the new TTR pension integrity measures will result in:


  • assets being transferred from the segregated current pension asset pool to the segregated non-current asset pool, for a fund using the segregated method to claim Exempt Current Pension Income (ECPI), or


  • a change in the proportion of total fund assets used to discharge pension liabilities, for funds using the unsegregated method.


What’s the process and which SMSFs should be looked at?

In essence, the process is the same as a fund with members who are required to comply with the transfer balance cap (see our CGT Relief explained article), except there’ll be no pension commutation. As there is no reference to the $1.6 million transfer balance cap, when reviewing which SMSFs will be eligible for CGT relief, this is not restricted to SMSFs who have members with pension accounts in excess of $1.6 million.

Fund with TTR members under $1.6 million eligible for CGT relief

Let’s consider an SMSF with two members and total assets of $700,000. At first glance, this SMSF would not be eligible for CGT relief, however, one member has a TTR pension with a balance of $500,000. Assuming the SMSF is using the unsegregated method to claim ECPI in 2016/17, you would expect an ECPI% of around 70%. From 1 July 2017, the new TTR pension integrity measures will mean that the level of ECPI claimed will be nil. This will have an effect on the amount of tax the fund pays when an asset is sold as any gain accrued since acquisition date to 30 June 2017 will be fully assessable (subject to CGT discount rules) when sold after 1 July 2017.

Consequently, this SMSF is eligible to apply the CGT relief rules. As the SMSF is using the unsegregated method to claim ECPI in 2016/17, all of the assets are eligible for CGT relief.

Let’s assume the SMSF has the following assets (all held for at least 12 months):
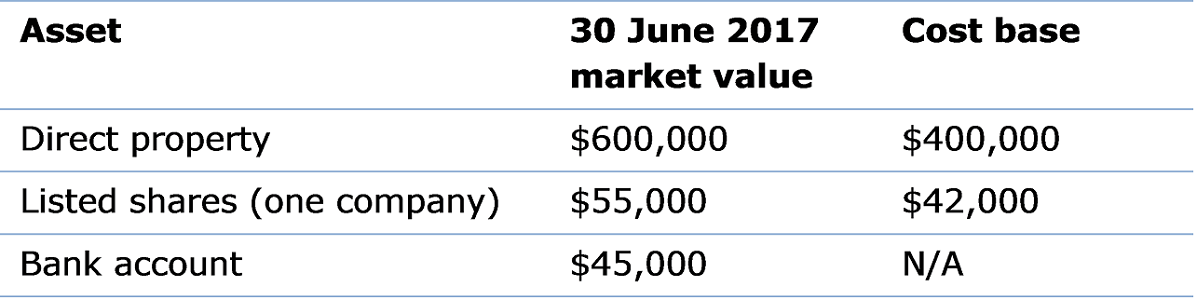
The SMSF then has the choice to either include the assessable gain for each of the assets, or defer until the asset is sold. The election to defer is made on an asset-by-asset basis and is also an irrevocable election to be made on the approved ATO form.
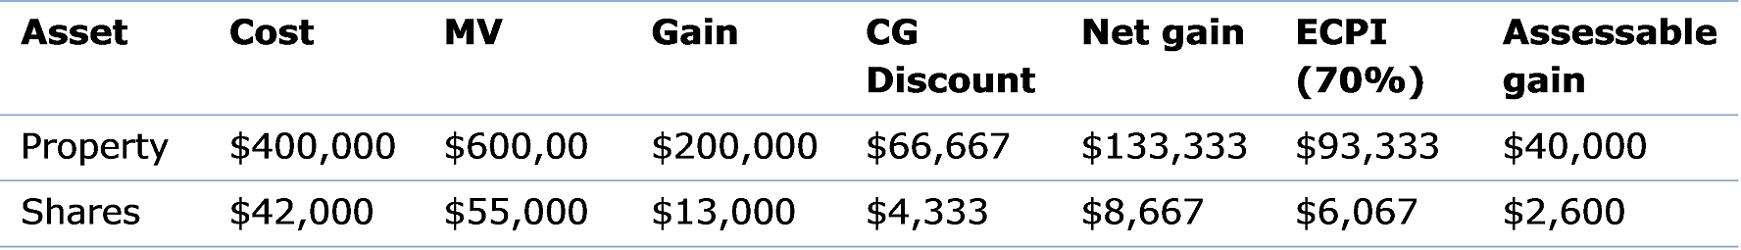
When the asset is sold after 30 June 2017, the assessable capital gain will be calculated based on a cost base of the respective 30 June market value and using a purchase date, for CG discount purposes, on 30 June 2017. The deferred assessable gain will also need to be included in the income year the asset is sold. For example, let’s say the listed shares were sold in 2019/20 for $60,000 and the notional gain in 2016/17 was deferred, the total assessable amount from this disposal will be calculated as follows:
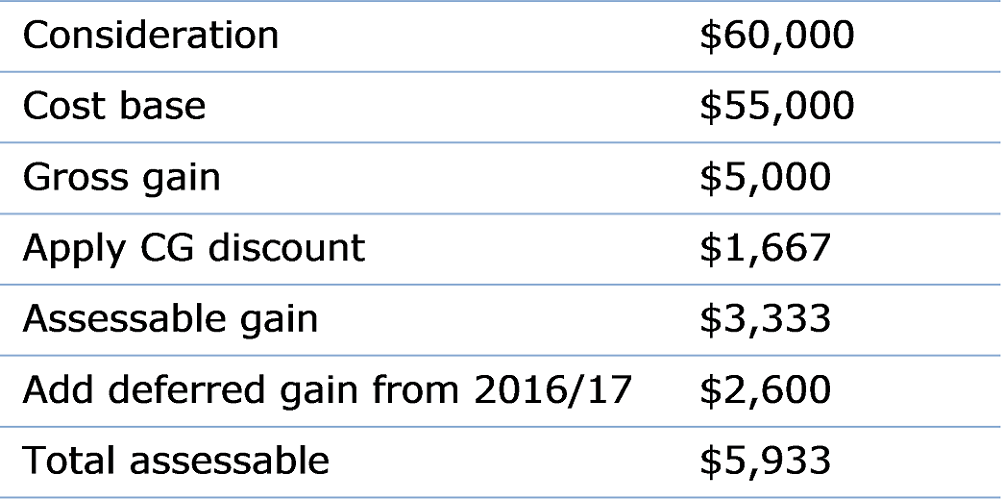
In this example, by applying the CGT relief and deferring the notional assessable gain in 2016/17, the SMSF saved $919 in fund income tax for this asset.

Is the SMSF a 100% TTR pension fund? Watch out for the trap!

For SMSFs wholly consisting of TTR pensions, there is a trap that can prevent the fund from applying the CGT relief rules.

Such funds are by default segregated funds. For the CGT relief rules to apply the fund must either transfer assets from the segregated current pension asset pool to the segregated non-current asset pool or change to the unsegregated method, on or before 30 June 2017. In practical terms, this would require the SMSF to have at least one member accumulation account on or before 30 June 2017. This could be achieved by either a member or their employer, making a contribution or a member effecting a partial or full commutation of a pension, with the commuted amount being retained in their accumulation account.

However, be mindful of the ATO’s comments in relation to application of Part IVA to schemes or arrangements designed to trigger access to the CGT relief rules. For example, a member making a $1 contribution would warrant ATO scrutiny as opposed to a fund that received an SG contribution from a member’s employer or where the member partially or fully commuted a pension.


Mark Ellem is Executive Manager, SMSF Technical Services at SuperConcepts, a leading provider of innovative SMSF services, training and administration. This article is for general information only and does not consider the circumstances of any individual.

  •   9 March 2017
  • 1
  •      
  •   

RELATED ARTICLES

Five things SMSF trustees should consider right now

Meg on SMSFs: The CGT changes don’t impact super but what about Div 296 tax decisions?

How to prevent excessive superannuation balances

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.